How Shimao’s sale of 2 hotels reveals the growing complexity of Hong Kong debt workouts
The HK$2.7 billion (US$344 million) sale of two Shimao Group hotels in Hong Kong leaves an estimated HK$1.8 billion shortfall against their secured loans. Still, receivers managed to squeeze out improved bids in the final stages, with all shortlisted parties improving their offers, said Una Ge, a managing director at AlixPartners who oversaw the sale as a joint receiver. The deal offers a glimpse…
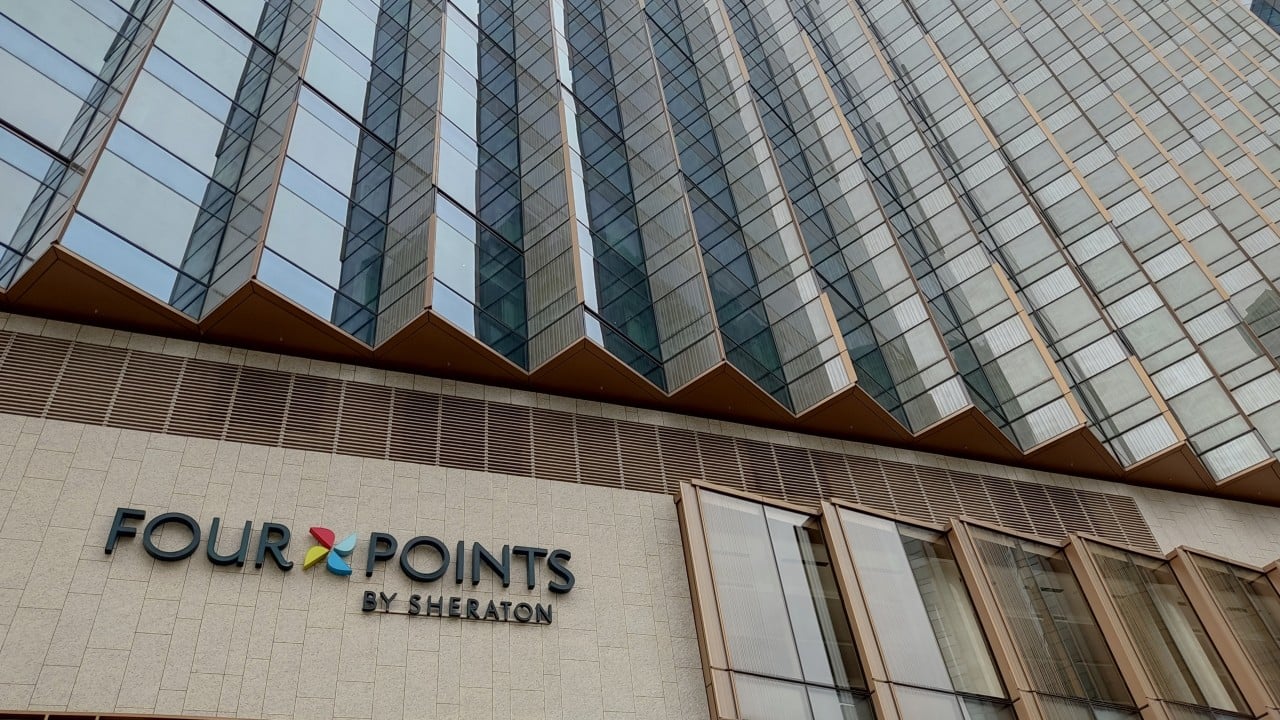
The HK$2.7 billion (US$344 million) sale of two Shimao Group hotels in Hong Kong reveals a complex scenario for resolving debt issues in the region. Despite a HK$1.8 billion shortfall on secured loans, the final bid from the shortlisted parties improved, with all parties increasing their offers, according to Una Ge, a managing director at AlixPartners overseeing the deal as joint receivers.
This deal sheds light on the evolving landscape of Hong Kong’s restructuring industry, marked by larger debt burdens, cross-border risks, and more intricate creditor syndicates. Managing the sale of the 1,219-room Tung Chung complex required more than just selling real estate; it entailed dealing with over 1,000 contracts. AlixPartners was tasked with protecting the live hospitality business from liabilities linked to the distressed mainland Chinese developer, Shimao, while managing a transaction involving numerous contracts.
The Sheraton Hong Kong Tung Chung Hotel and Four Points by Sheraton were acquired by Oceanfront Hong Kong, a company controlled by Malaysian property developer ParkCity Group. Shimao had initially sought between HK$6 billion and HK$6.5 billion for the assets in 2023, but lowered its expectations to HK$4.5 billion by late 2023. The final sale price of HK$2.7 billion represents a 40% reduction from the HK$4.5 billion syndicated loan facility, highlighting the concessions banks are making to ease balance-sheet pressure and cut provisioning.
Preserving operating cash flow was crucial in the transaction, with AlixPartners working alongside Marriott International to ensure operational continuity before court orders were finalized. This operational stability was vital for prospective buyers and lenders considering support for the sale. Despite the challenges, Shimao cooperated throughout the receivership, providing necessary information and agreeing that the hotels would continue operating as usual.
This cooperation, rooted in its earlier efforts to reduce liabilities through other disposals, was key to maintaining customer confidence. The legal aspects of the deal were complex, involving the separation of physical assets from operating entities and the negotiation of over 1,000 commercial agreements. The receivers had to secure consents under Marriott’s long-term management contract to ensure day-to-day operations remained with the hotel brand.
Interest in the deal came from potential buyers in nine markets, including mainland China, Singapore, Malaysia, Japan, Australia, Europe, the Middle East, and the US. Receivers took direct management of the adjacent T Bay shopping mall, renegotiating retail leases, upgrading signage, and launching guest discount programs. Una Ge highlighted that while sunk costs often influence decisions, forward-looking decisions should prioritize execution certainty, financing commitments, and board approvals.
Property markets in Hong Kong show signs of stabilization, but commercial property values remain pressured. Lenders are increasingly relying on mortgagee sales to recover debt, and office buildings continue to trade at significant discounts.
Written by urgent.news from SCMP Business's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.
This story
This is one outlet's version. Read the fullest account.