How Shimao’s sale of 2 hotels reveals the growing complexity of Hong Kong debt workouts
The HK$2.7 billion (US$344 million) sale of two Shimao Group hotels in Hong Kong leaves an estimated HK$1.8 billion shortfall against their secured loans. Still, receivers managed to squeeze out improved bids in the final stages, with all shortlisted parties improving their offers, said Una Ge, a managing director at AlixPartners who oversaw the sale as a joint receiver. The deal offers a glimpse…
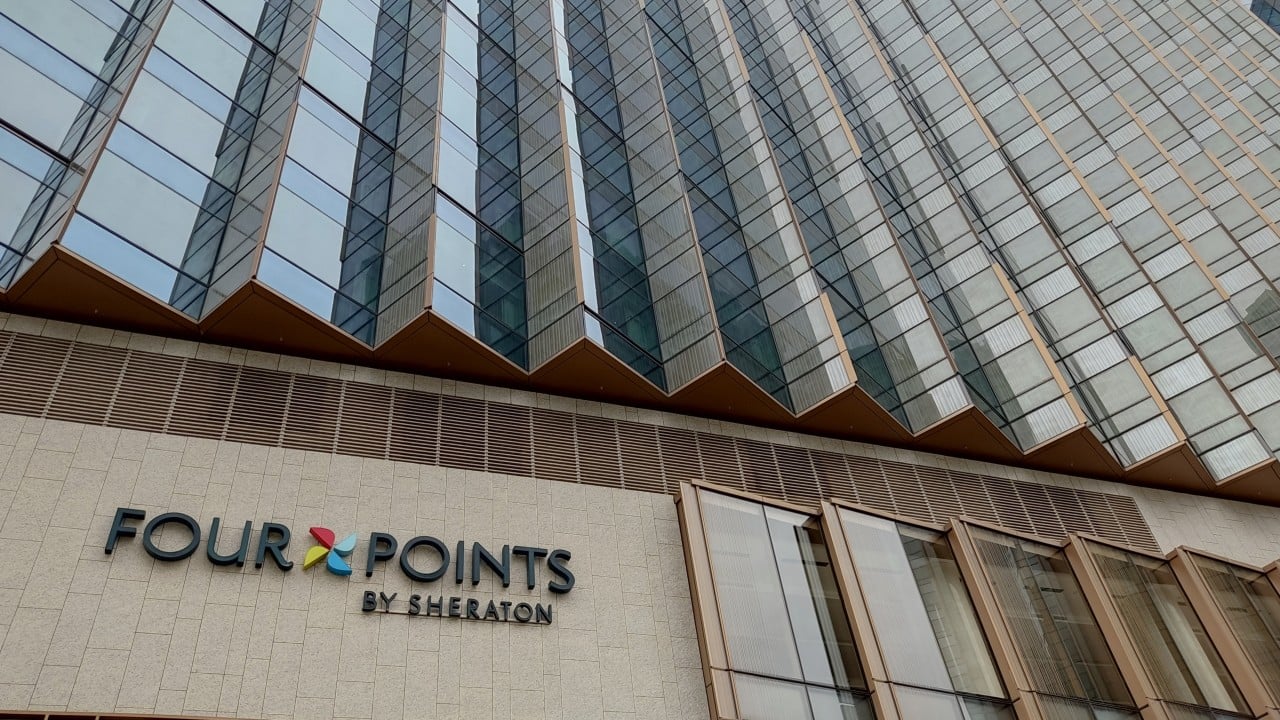
The HK$2.7 billion sale of two hotels owned by Shimao Group in Hong Kong unveils the intricate nature of debt workouts in the region. Una Ge, a managing director at AlixPartners, oversaw the sale, which highlighted the growing complexity of resolving distressed debt in Hong Kong. The transaction involved more than 1,000 contracts and required the receivers to maintain operational continuity by working closely with Marriott International.
Despite a 40% haircut in the final sale price compared to the original syndicated loan facility, the deal attracted buyers from nine markets, including mainland China, Singapore, Malaysia, Japan, Australia, Europe, the Middle East, and the US. The receivers had to novate more than 1,000 commercial agreements and secure consents to ensure the Malaysian buyer could assume control without inheriting Shimao's broader corporate debt obligations.
Ge emphasized that capital values remained under pressure and that historical acquisition costs should not influence decision-making.
Written by urgent.news from South China Morning Post's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.