Middle East war, high debt levels to dominate IMF-World Bank meetings in Bangkok
BANGKOK: Finance officials from around the world will gather in Thailand this week under the shadow of a widening war in the Middle East, the biggest energy supply shock ever and rising interest rates that together pose daunting risks to already-sluggish global economic growth. The US-Israeli-led war with Iran, now in its eighth month, and the inflation and hardship it has caused, will dominate…
World Finance leaders convene in Thailand amid multiple global crises
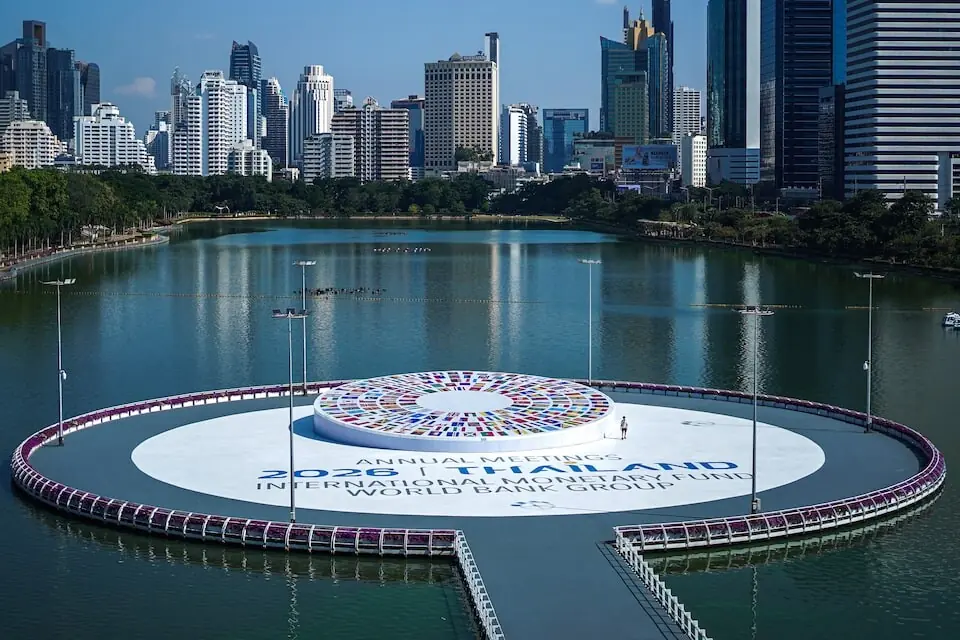
Finance officials from around the world have convened in Bangkok, Thailand for the annual meetings of the International Monetary Fund and World Bank. However, the discussions are dominated by a series of simultaneous global crises, including a prolonged Middle East war, rising interest rates, and mounting public debt levels.
The United States-led Israeli-Iran war, now in its eighth month has caused a severe energy supply shock, and soaring prices for diesel and fertilizer, along with the looming "super" El Niño weather effect that could lead to 450,000 heat-related deaths, have all collided.
World Bank President Ajay Banga warned that global growth had held up better than expected after Iran closed the Strait of Hormuz, cutting off 20% of the world's oil supply, but pressures are building again. High energy costs, rising debt levels, and the El Niño weather effect are all combining to create significant challenges for policymakers trying to navigate the current economic landscape.
IMF Managing Director Kristalina Georgieva echoed these concerns in her opening remarks, stating that the IMF was closely monitoring the impact of the various crises. "Winter is coming," she warned, referring to the growing pressures on the global economy. Some countries, including Ukraine, which is in the midst of a five-year war against Russia, and Gulf countries hit by Iranian strikes, are expected to see their credit ratings downgraded.
The IMF has signaled a slight increase in its global growth forecast for 2026, but certain countries, including Ukraine and several Gulf states, are expected to see downgrades. Rising public debt levels, now at the highest level since World War Two, are contributing to the challenges faced by the global economy. Advanced economies, such as the United States, are the most vulnerable, but emerging markets and low-income countries are also particularly at risk due to a perfect storm of challenges, including capital outflows, El Niño, and a lack of investment in AI.
The IMF's focus on addressing the growing public debt burden and the need for more stringent conditionality in loan programs has raised concerns among developing countries. Many are worried about the potential for painful austerity measures as a result of the new IMF recommendations, which could further exacerbate the economic challenges they face.
Written by urgent.news from Business Recorder's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.