Do Term Spread Inversions Help Predict Australian Recessions?
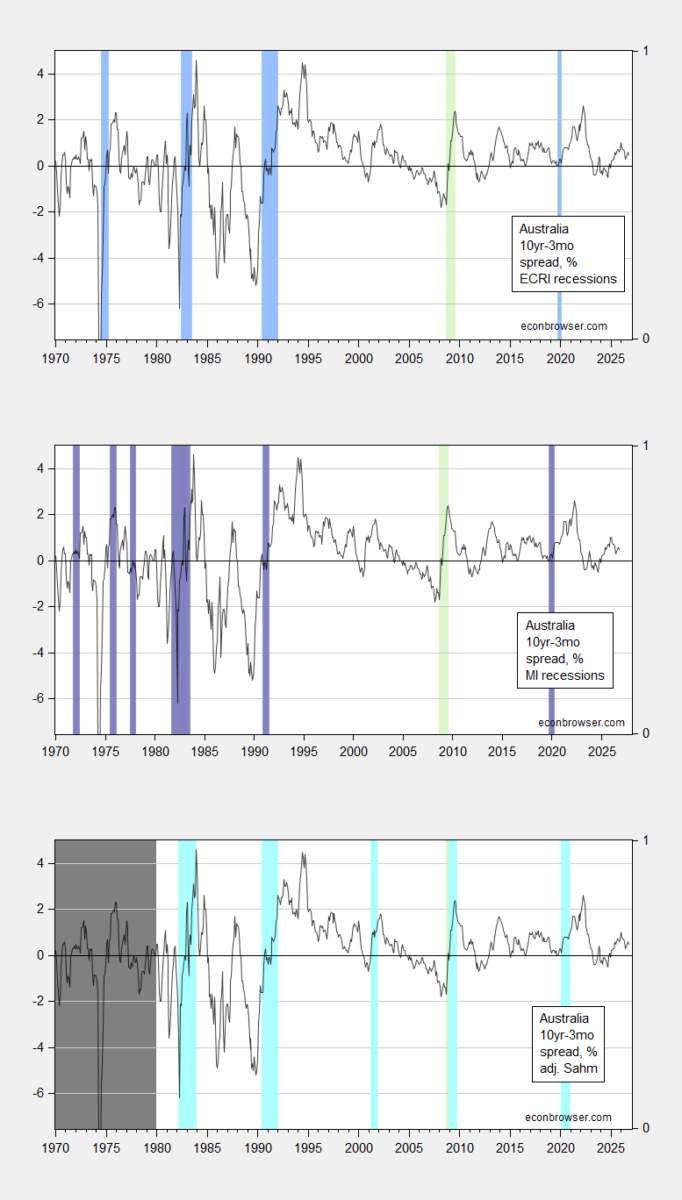
Not really, even using alternative recession chronologies. Figure 1: Top panel, Australia10 year-3 month term spread, %, and ECRI defined peak-to-trough recession dates shaded light blue, Middle panel, Light green denotes trough to peak unemployment rate defined dates. Melbourne Institute defined recession dates shaded light violet, Bottom panel, modified Sahm rule peak to trough (+0.75 […]
Term spread inversions, or the phenomenon where the yield on long-term bonds falls below the yield on short-term bonds, have been examined as a potential predictor of Australian recessions. However, the results do not support this hypothesis, even when using alternative recession chronologies.
Figure 1 illustrates the relationships between the Australia 10-year-3-month term spread, unemployment rate, and recession dates defined by different sources. The Melbourne Institute and ECRI largely agree on the recessions in the mid-1980s and 1990-91 periods, as well as the absence of a recession in 2009. However, they disagree on the recessions in the 1970s.
When using the Sahm rule with a 75 basis point threshold, the Sahm rule would have indicated recessions in 2001 and 2009. Yet, employment and GDP did not experience sustained declines during these periods, and none of the recessions were successfully predicted with a pseudo-R2 greater than 0.14 over the 1986-2026 period. The coefficient on the spread was also found to be opposite of what would be expected.
Restricting the sample to the pre-pandemic period improved the pseudo-R2 to up to 50% for the ECRI and Melbourne Institute chronologies. However, the term spread still retained the "wrong" sign, indicating that it is not a reliable predictor of Australian recessions.
Rewritten by urgent.news; may contain errors — check the original.