Equities Held by Households, 2000 and Now
Estimates for 2026Q2, Q3, compared to 2000. Figure 1: PCE deflated equities and mutual funds held by households, in logs 1995Q3=0 (blue, left scale), equities and mutual funds held by households as a share of net worth (red, right scale). NBER defined peak-to-trough recession dates shaded gray. Source: Board of Governors of Federal Reserve, Flow […]
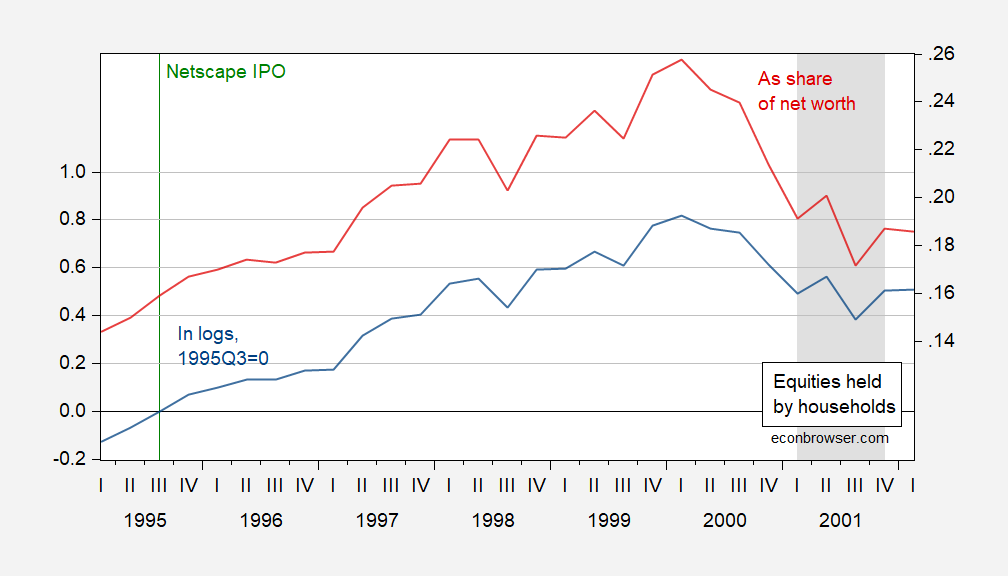
As of 2026Q2 and Q3, estimates suggest that equities and mutual funds held by households have risen by approximately 40%, compared to the 60% increase experienced in the 2000 peak. However, the share of household net worth represented by these investments is currently higher at 31% compared to 26% in 2000.
The impact of this shift on consumption is a matter of some debate. Historically, analysts have made a distinction between paper wealth (e.g., equities and mutual funds) and real wealth (such as real estate). Beach, Gamber, and Moran (2025) have noted that the marginal propensity to consume (MPC) out of wealth has declined over time due to increasing wealth heterogeneity and concentration. They estimate that the MPC in 2000 was around 3.4 cents for every dollar of wealth, whereas it was approximately 2.6 cents in 2019.
To put this in perspective, a $3 trillion reduction in wealth—roughly the magnitude of wealth lost last week—would translate to a $80 billion reduction in consumption. Q3 nominal consumption stood at about $22.5 trillion (at a seasonally adjusted annual rate), making this a relatively modest decrease on its own.
However, if this trend were to persist, the reduction in consumption could become more pronounced. For instance, a one-time drop in wealth could lead to a noticeable decline in overall consumption, demonstrating the importance of understanding the interplay between wealth trends and spending behavior.
Written by urgent.news from Econbrowser's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.