Does home insurance cover storm damage?
Home insurance will typically cover various types of storm damage, but you may face exclusions for flooding or sewer backup damage without added coverage.
Standard homeowners insurance typically provides coverage for various types of storm damage, including wind, hail, lightning, and fire. This coverage extends to both the structure of the home and personal belongings. However, certain types of damage, such as flooding, earth movement, and sewer backups, are not covered by standard policies and may require additional endorsements or separate policies. Some policies also exclude particular types of windstorm damage, particularly in hurricane-prone or coastal regions.
When it comes to storm damage caused by wind, standard homeowners insurance usually covers it, including damage from tornadoes, hurricanes, and winter storms. However, coastal states may have separate deductibles for hurricane or windstorm claims, which can lead to higher costs depending on the insurer and location. Hail damage is also typically covered by home insurance, whether it's causing damage to the roof, siding, or other structures.
Lightning damage leads to fire, smoke, or power surge, and home insurance generally covers such incidents.
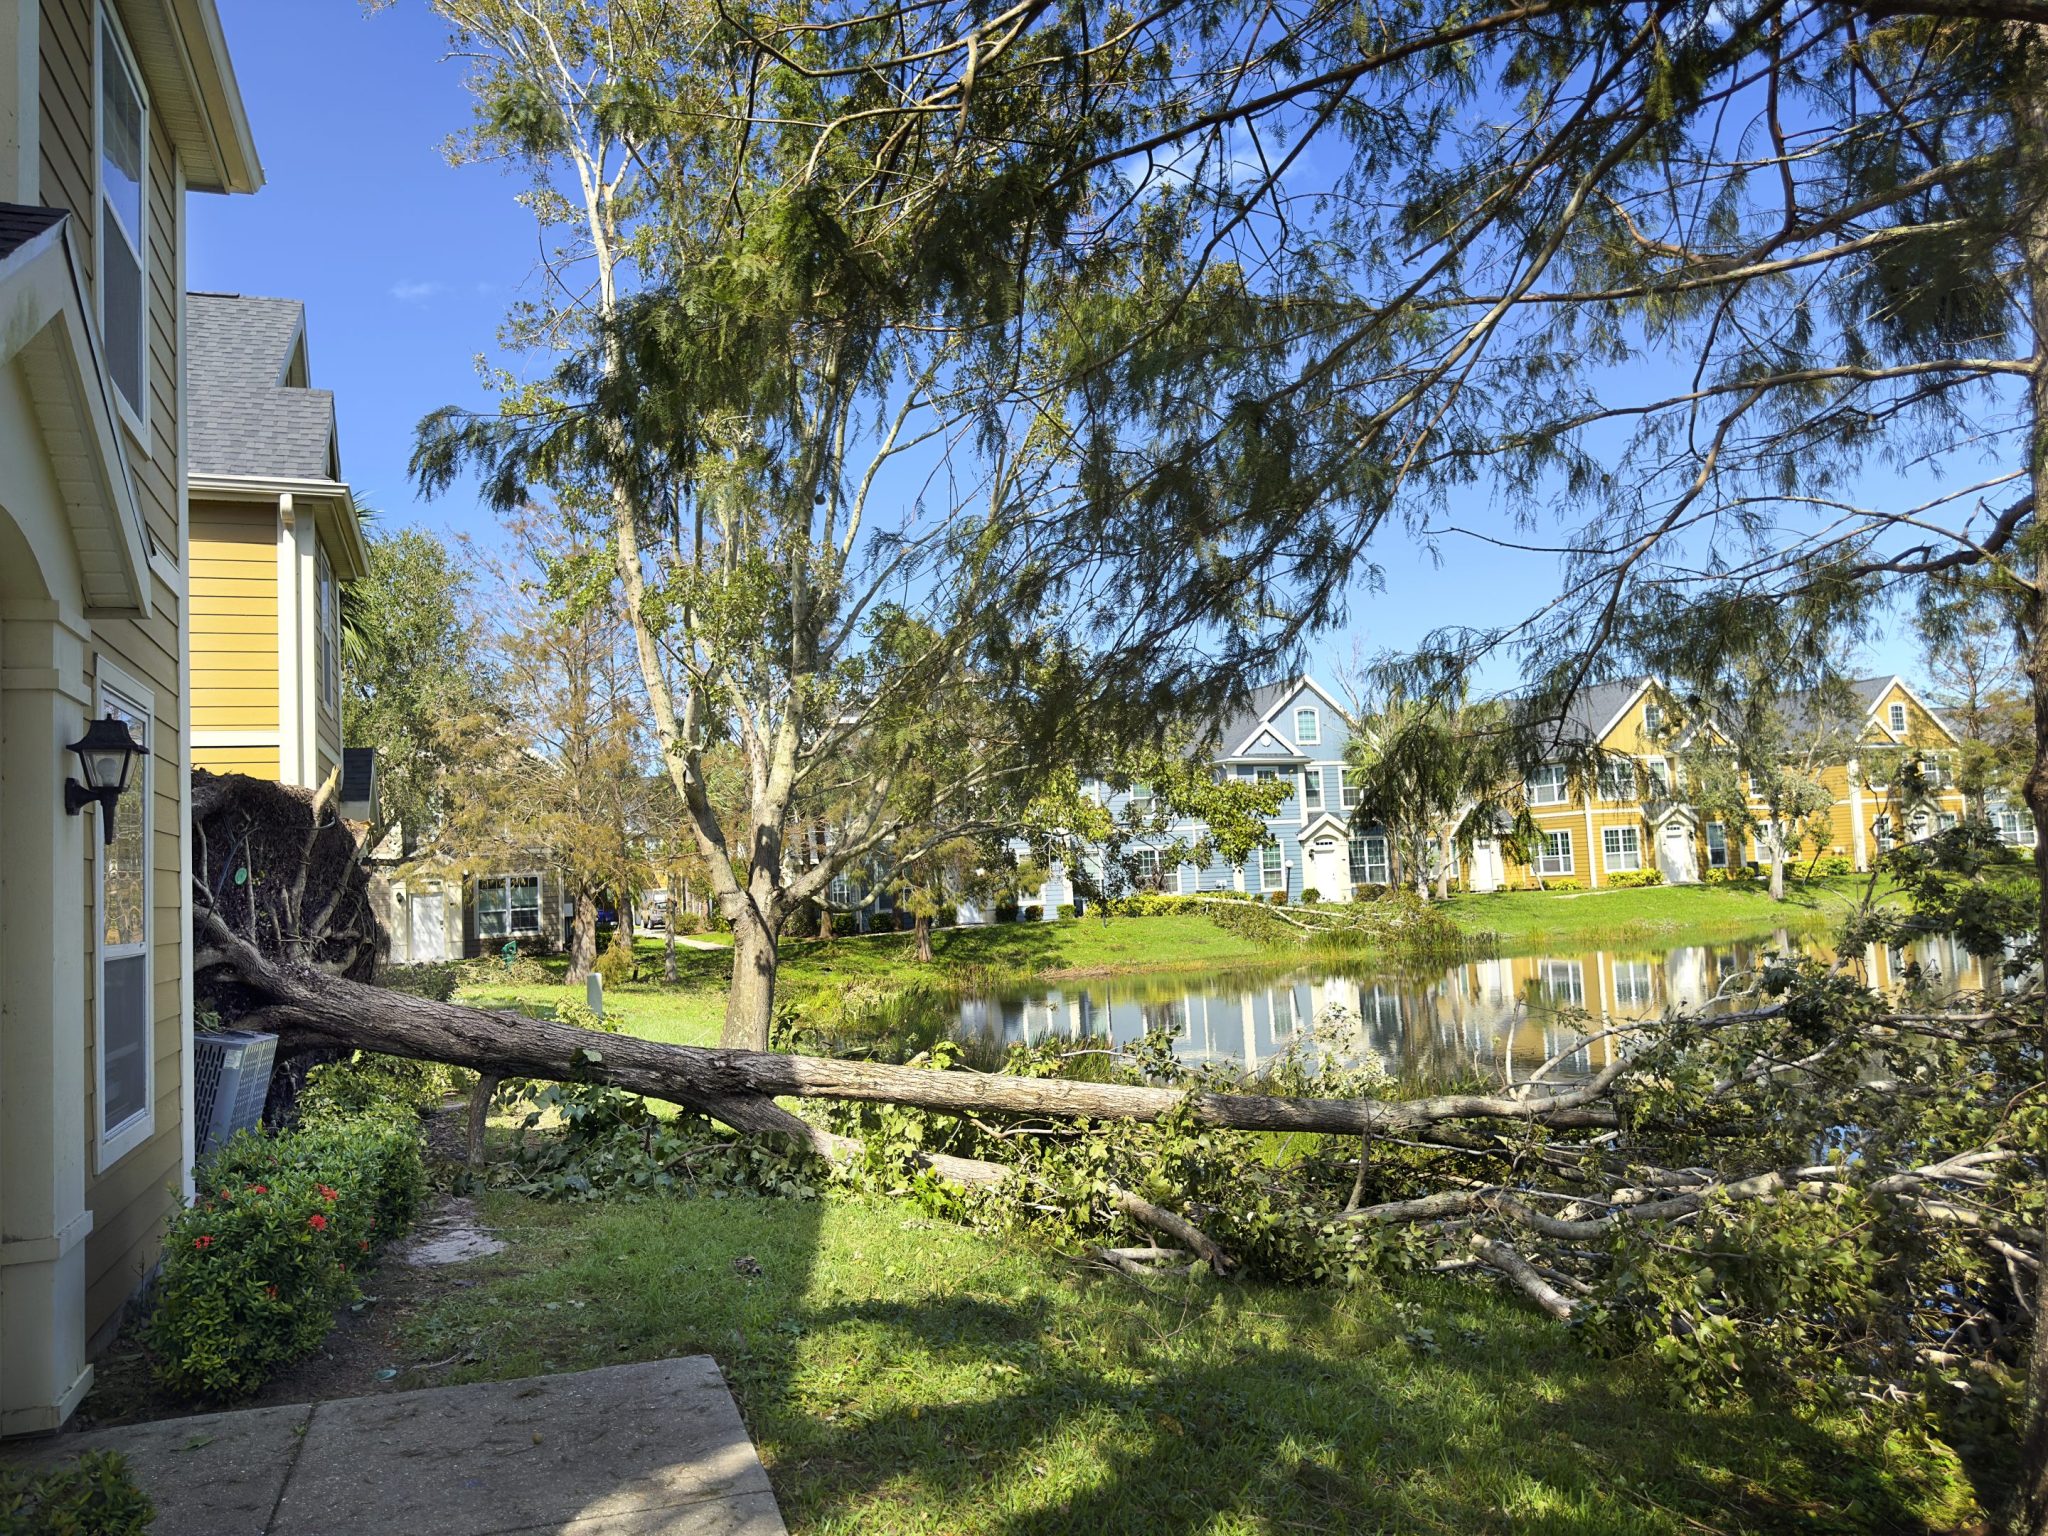
Tree damage is another aspect of storm coverage. If a storm with heavy winds or lightning causes a healthy tree or its branches to fall on the property, the home insurance policy generally covers the damage. However, this coverage doesn't extend to dead or rotting trees that the homeowner is responsible for managing. In the case of snow and ice, home insurance typically covers damage caused by these elements, such as a collapsed roof due to heavy snow or burst pipes from ice accumulation.
On the other hand, there are certain types of storm damage that standard homeowners insurance does not cover. Flood damage, for instance, is not included in a typical policy. Those living in flood-prone areas can obtain separate flood insurance through the National Flood Insurance Program (NFIP) or private insurers. Similarly, sewer backup damage, which can occur due to heavy rainfall during storms, is not covered by standard homeowners insurance.
An endorsement to the policy can provide coverage for such incidents. Earth movement, such as landslides caused by storms, is also generally excluded from home insurance. Lastly, damage resulting from gradual wear and tear or poor maintenance is typically not covered by homeowners insurance.
Written by urgent.news from Fortune's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.