BIMB Securities sees 58pct upside in MTT Shipping, initiates 'Buy' call
KUALA LUMPUR: BIMB Securities Research has initiated a “Buy” recommendation on MTT Shipping and Logistics Bhd with a target price of RM1.90, implying a 58 per cent upside from its last price of RM1.20.
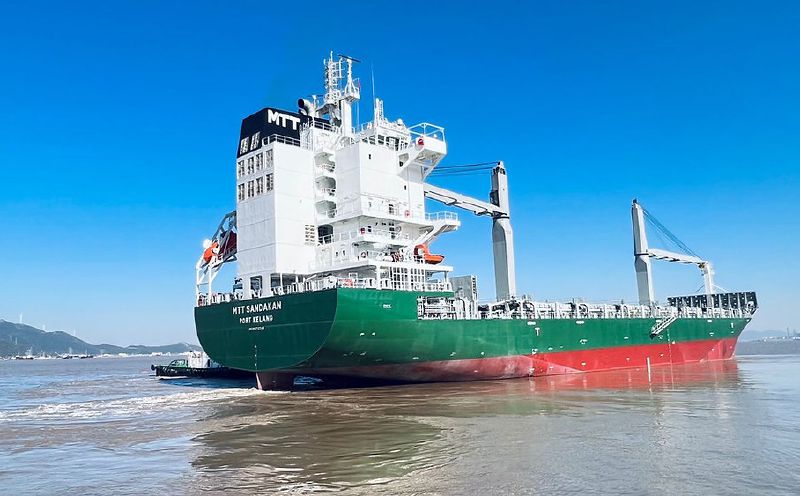
KUALA LUMPUR: BIMB Securities Research has upgraded its stance on MTT Shipping and Logistics Bhd, launching a Buy recommendation. The firm now anticipates a 58% upside potential from the stock's current price of RM1.20, with a target price of RM1.90. This optimistic outlook is driven by stronger earnings prospects, rising charter rates, and a tight supply in the small and mid-sized container shipping market.
Two upcoming charter rollovers for MTT Samalaju and MTT Sainusee have already shown rates 19% higher than previous charters, indicating the increasing scarcity of vessels in the sub-4,000 TEU segment. Additionally, the firm expects four container vessels to join the fleet in FY27, prompting a revision of charter expectations. BIMB Securities reported a 61.6% gross margin for the charter segment in the first half of FY26, an improvement from 57.8% in FY25.
Assuming gross margins stay below 60%, the firm projects MTT Shipping's net profit to exceed RM400 million by FY27, representing a 33% growth in FY26 and a 9% increase in FY27. The staggered arrival of the new vessels is expected to further fuel earnings growth over the next three years, with net profit projected to grow at a compound annual rate of 21% between FY25 and FY28.
MTT Shipping's earnings are anticipated to be less volatile than those of most shipping companies, bolstered by its domestic liner business and charter operations. The domestic liner business benefits from stable and growing volumes, supported by the company's 46% market share in the domestic segment, which is protected under the cabotage policy.
Meanwhile, the charter operations offer higher margins of around 60%, compared to 27% for liner operations. While BIMB Securities acknowledges that its target price implies a relatively high valuation of 12 times FY27 earnings, compared to the sector's peers trading at 5.6 times trailing 12-month earnings, they believe this is justified by MTT Shipping's superior growth outlook and higher profitability.
The firm projects a return on equity of 18% in FY27, compared to the 10-11% range for peers. Additionally, the company's improving relationship with institutional investors could enhance its market visibility and attract more investor interest in the shipping sector.
Written by urgent.news from New Straits Times's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.