El BCE vislumbra nuevas inyecciones de liquidez a la banca para 2027
El exceso de liquidez del sistema ha caído en más de dos billones de euros y los bancos han disparado su recurso a la barra libre de Fráncfort en los últimos meses. A diferencia de en el pasado, no se espera que las nuevas operaciones tengan condiciones superventajosas para las entidades. Leer
The European Central Bank (ECB) anticipates fresh liquidity injections to the banking sector by 2027. Excess liquidity in the system has fallen to over 2.7 billion euros, and banks have increased their reliance on the Frankfurt free bar in recent months. Unlike previous instances, the new operations are not expected to have advantageous conditions for the entities.
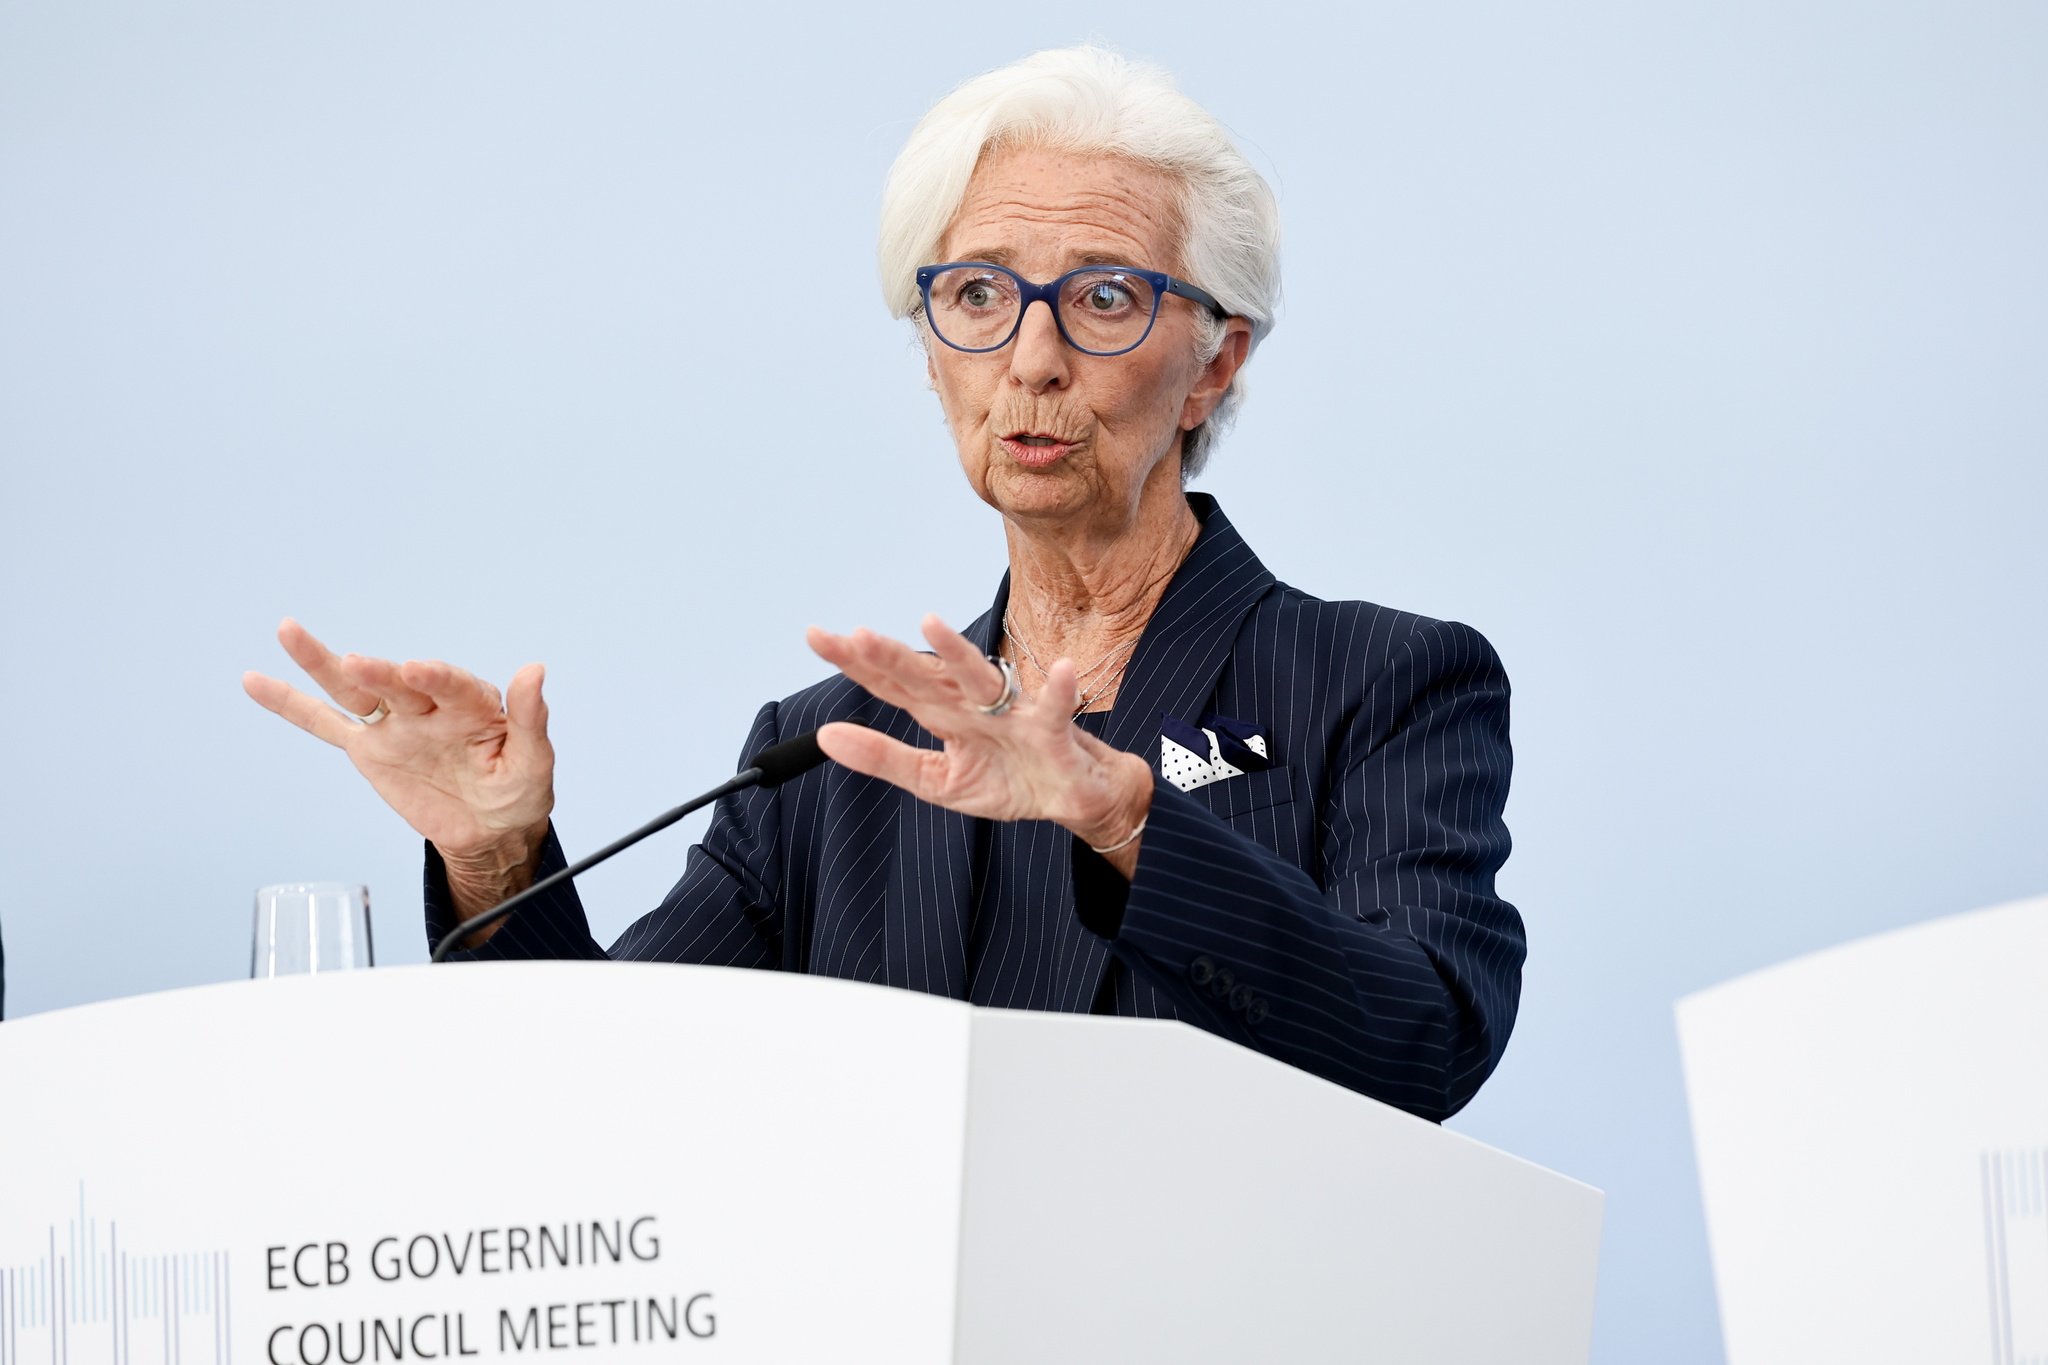
The ECB continues to normalize its monetary policy years after the sudden shift following the pandemic and interest rate hikes. However, this process may be nearing a turning point. Different sources close to the institution's governance council presided over by Christine Lagarde indicate that 2027 might be the year the ECB lifts the curtain on its new long-term refinancing operations for banks.
There are serious possibilities that structural liquidity injections could commence in 2027, given the conditions. A spokesperson for the ECB declined to comment on this matter. Nobody dares to predict the exact nature of these fresh money injections at the moment. Nevertheless, several members of the central bank hint at certain consensus elements they believe will characterize the upcoming operations.
One of them is their typology. The new operations will be Long-Term Refinancing Operations (LTRO), meaning liquidity injections with maturities significantly longer than the usual weekly free bar that the ECB holds. This format also does not carry any attached conditions, unlike the targeted long-term refinancing operations (TLTRO) the Frankfurt-based institution launched under highly favorable conditions to encourage banks to stimulate credit for families and businesses during the worst years of the coronavirus crisis and the European debt crisis.
The aim is to provide the necessary liquidity for the system to operate, not to introduce new stimulus, according to sources close to the central bank who assure these operations should not be seen in the framework of an expansive monetary policy as in the past. Regarding the term, both the market and central bankers understand that it should be longer than six months.
This is the time from which banks can compute these resources for their most relevant liquidity ratios, the Net Stable Funding Ratio (NSFR), which measures whether a bank has sufficient long-term financing to support its assets for a year. This would be the key difference compared to the weekly auction the ECB already conducts or the regular three-month term operations.
However, neither very long maturities nor excessively favorable conditions are expected to avoid granting excessive regulatory advantages that might generate a dependency of the banking sector on this type of resources. Additionally, for the ECB, it is easier to adjust liquidity in the system if there are no long-term locked resources.
The ECB has already adjusted the term of the loans granted to banks in the past. Only in exceptional circumstances, such as in response to the sovereign debt crisis or the pandemic, did the term of these operations exceed a year, as pointed out by Isabel Schnabel, member of the ECB Executive Board responsible for Market Operations, in a speech in November of the previous year, hinting at these future operations without specifying the conditions for activating them.
Liquidity injections are part of the operational framework the ECB updated in March 2024 to adapt its monetary policy to the new reality of higher interest rates and the end of extraordinary debt purchases. At that time, the authority indicated that the time would come when the excess liquidity of eurozone banks would normalize, and structural long-term refinancing operations would be introduced.
Now, that situation has changed. According to the ECB's calculations, excess liquidity fell to 2.7 billion euros in July, reaching a peak of 4.7 billion in April. While there are doubts about the floor for the excess liquidity leading to a fully normalized monetary policy, various market estimates point to the range of 1.8 to 1.4 billion euros.
This suggests that levels are approaching a point where liquidity is no longer excessive in the system and all means should be considered to achieve it, as recognized by market participants for months to the ECB. However, for Frankfurt to seriously consider launching new structural liquidity operations for banks, it first had to detect persistent use of standard refinancing operations before launching structural ones.
As reported by EXPANSIÓN in September, banks have doubled their weekly liquidity requests at the monetary authority since interest rates began to rise again. As of the first half of the year, liquidity provided by the monetary authority has already reached 500 billion euros, figures that, if maintained, would meet the requirement of persistent use of this tool before enabling new operations.
Written by urgent.news from Expansion ES's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.