Euro slides as concerns about French debt mount
NEW YORK, Oct 6 — The euro slid yesterday to its lowest level against the dollar in 17 months on worries about Fra...
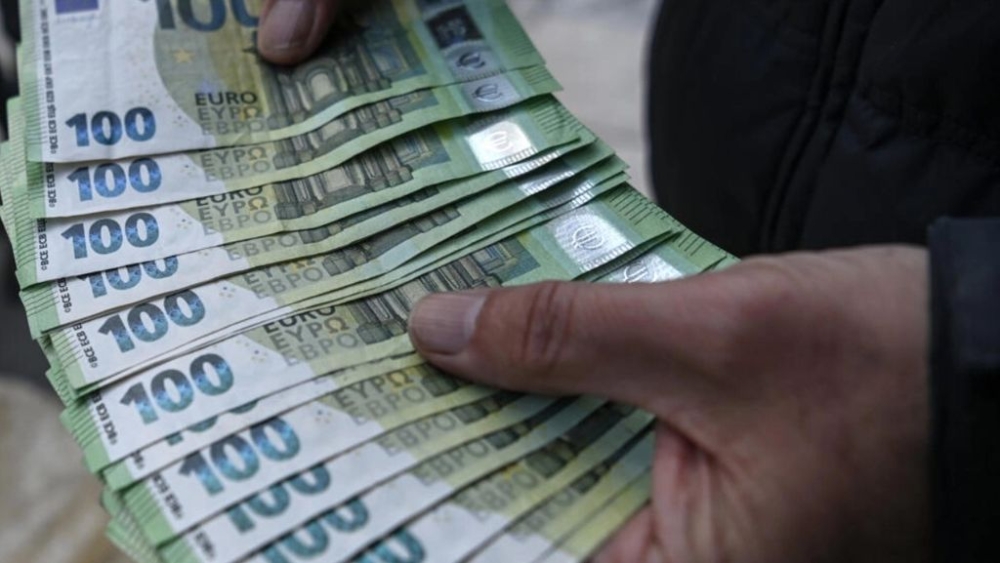
The euro experienced a significant drop to its lowest level against the dollar in 17 months due to concerns over France's high debt and deficits, which have led to soaring government bond yields. Despite the pressure from elevated bond yields, equities generally traded higher, with the Nasdaq hitting a new record in New York. This comes after an underwhelming 2027 budget plan was unveiled, further fueling concerns about French government spending remaining high ahead of next year's presidential elections.
The far-right Marine Le Pen, seen as a fiscal populist, stands a chance of winning, rattling bond investors at a time when interest rates and borrowing costs are rising worldwide to combat inflation. French debt is projected to increase to nearly 122% of the country's GDP next year, despite planned spending cuts, with the 10-year government bond yield reaching 4.8%, the highest since 2011.
Additionally, Prime Minister Pedro Sanchez of Spain called for snap elections, surprising investors after lawmakers rejected a housing relief bill. Patrick Munnelly, a market strategist, stated that France's fiscal credibility and political stability have already been under pressure, and Spain adds another layer of uncertainty, weighing on Europe's political risk.
Stocks in general advanced, with the tech-focused Nasdaq closing at a new record, driven by gains in AI-related stocks. However, analysts are concerned that the market gains are being driven by a narrow slice of stocks. Paris faced additional downward pressure due to bond yields and a nearly 10% drop in Schneider Electric shares following the company's announcement of a $22.6 billion all-cash deal to purchase US engineering software specialist PTC.
Oil prices ended lower after an agreement among G7 countries to release 100 million barrels of diesel and crude oil to alleviate supply concerns caused by the US-Iran war. Saudi Aramco CEO Amin Nasser described oil stockpiles as "scarily thin" as the European winter approaches. Despite increased oil exports, supplies of some products like diesel remain tight due to damaged refineries from the conflict in the Middle East and Ukrainian strikes on Russian energy facilities.
Written by urgent.news from Malay Mail's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.