Insured, but Still on the Hook: Who Bears the Most Risk in Homeowner’s Insurance?
In an April post , using millions of homeowners' insurance contracts matched with property-level exposure and disaster risk, we showed that although households are insured, they are still "on the hook” because deductibles and coverage limits leave homeowners responsible for part of a loss. Because insurers cannot perfectly observe how well homeowners maintain or protect their properties (a…
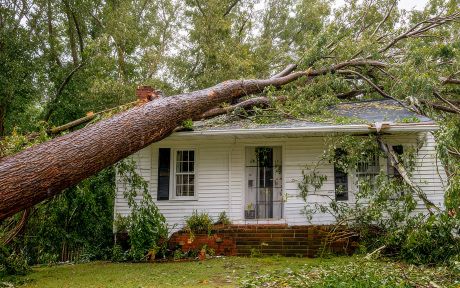
A new analysis of millions of homeowner's insurance contracts, matched with property-level exposure and disaster risk, shows that while households obtain insurance, they still bear a significant portion of the loss. This occurs because deductibles and coverage limits leave homeowners responsible for part of a loss, a phenomenon known as moral hazard.
Insurers incorporate contract terms such as deductibles and coverage limits to balance risk sharing and create incentives for policyholders to take actions that reduce damage risk.
The study reveals that although insurers incur relatively little cost from moral hazard, households retain substantial risk, especially those with limited financial resources. On average, lower FICO score borrowers are estimated to be more risk-averse, pay higher risk premia, face higher costs associated with moral hazard, and retain more uninsured exposure. Even though the direct cost of moral hazard is small, households are left with 29 percent of expected losses, highlighting the substantial residual exposure.
Residual exposure is also higher in properties located in areas facing greater tail disaster risk. These patterns, while correlations, suggest that financially constrained households and properties in high-risk areas bear more of the loss despite having insurance. Insurer financial conditions also play a role, with more financially constrained insurers tending to insure riskier properties and collect higher risk premia, though the premium as a share of the total premium remains relatively flat across insurer financial constraints.
Written by urgent.news from Liberty Street Economics's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.
Read the original at libertystreeteconomics.newyorkfed.org →