Ukraine’s steel output fell 57% and may hit zero next month. Expert says saving it comes down to four steps, and they’re Brussels’ to make
Steel is Ukraine's second-largest foreign-currency earner, employing more than 70,000 people directly and another 250,000 in related industries.
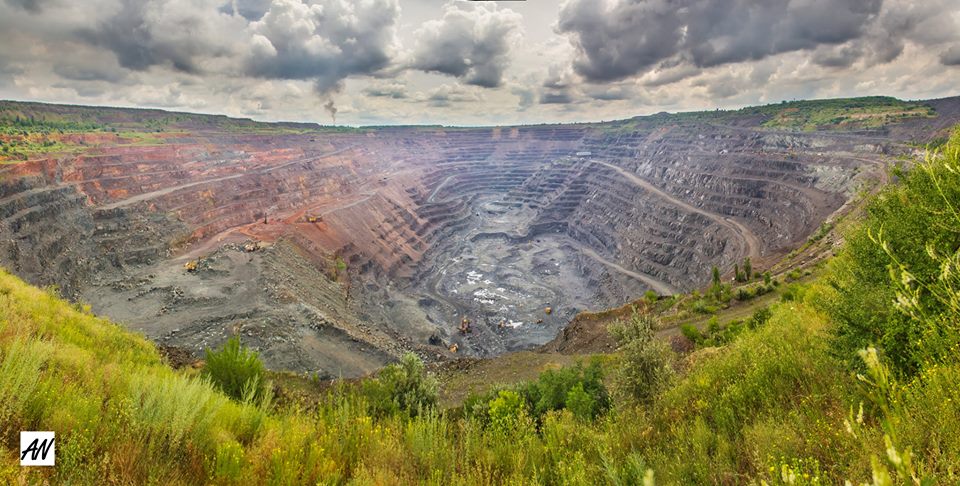
Ukraine's steel output plummeted 57.3% in August and may reach zero by October, according to Stanislav Zinchenko, director of the GMK Center. The industry, a crucial pillar of the wartime economy, saw production drop to 277,000 tonnes and pig iron production decline by 65.6% over eight months. Zinchenko attributes the industry's dire situation to a perfect storm of Russian strikes, an energy crisis, and EU competition.
Steel, Ukraine's second-largest foreign-currency earner, employs over 70,000 people and generates almost $1 billion in taxes annually. The sector is responsible for 6% of Ukraine's GDP and 13% of its foreign-currency earnings.
To save the industry, Zinchenko proposes four steps that fall under Brussels' jurisdiction. First, frontline rail access for steelmakers to facilitate the movement of products out of the conflict zones. Second, energy parity by relaxing the rule that forces industry to import 80% of its electricity at European prices. Third, market protection through tax measures on scrap-metal exports and curbing Turkish imports that undercut Ukrainian steel.
Lastly, a dedicated recovery fund modeled on those established for Ukraine's energy sector, as well as a safe sea corridor to reduce export costs, removal of EU quotas and tariffs on Ukrainian metal, and an exemption from the EU's carbon border levy during the war and reconstruction period. If these measures are implemented, Zinchenko believes the plants could return to baseline within three to six months, with a full rebuild taking one to two years.
Written by urgent.news from Euromaidan Press's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.