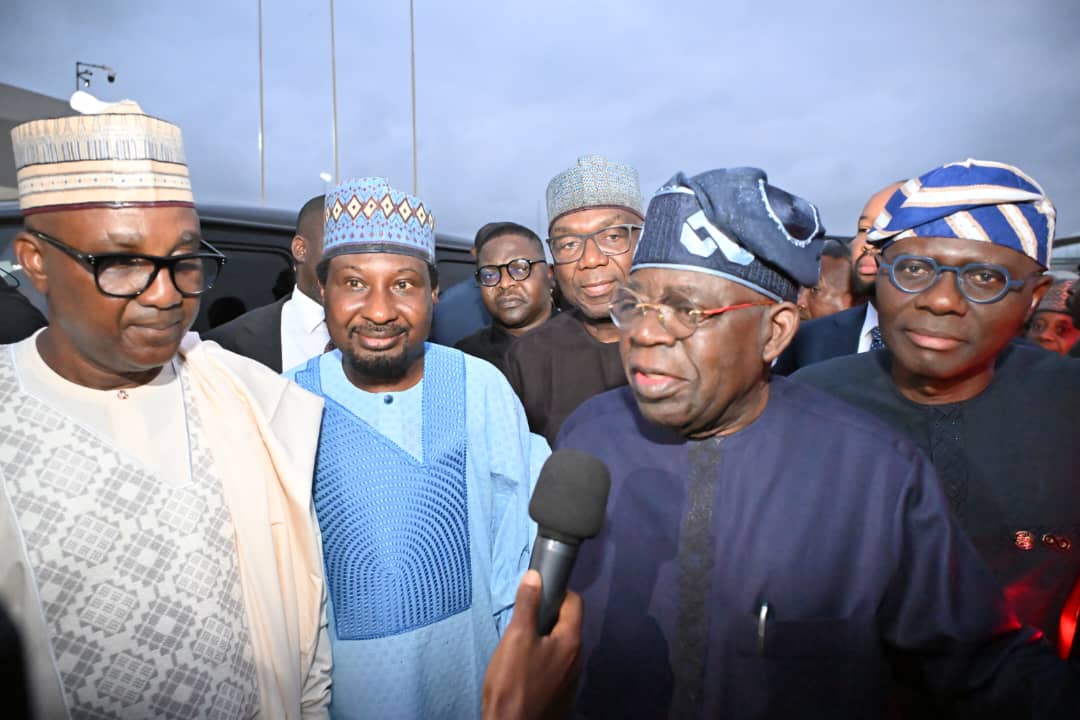
Tinubu returns to Nigeria after four weeks abroad
Mr Tinubu left Nigeria on 30 August, first to the UK and later to France, from where he returned on Tuesday. The post Tinubu returns to Nigeria after four weeks abroad appeared first on Premium Times Nigeria .
The Allied Peoples Movement (APM) has criticized the President Bola Tinubu-led administration for lacking a clear plan to repay Nigeria's mounting debt. The party urged international lenders, including the World Bank and the International Monetary Fund (IMF), to cease extending new loans to the federal government, warning that continued borrowing could increase financial strain on Nigerians.
This was stated in a statement by APM's National Publicity Secretary, Abubakar Yusuf, in response to reports of negotiations between the federal government and the World Bank over three proposed financing facilities amounting to $1.5 billion.
The APM questioned the government's capacity to manage additional debt, pointing out that there has been no clear strategy presented for repaying the loans taken on during Tinubu's administration. Yusuf condemned the administration's plan to secure a further $1.5 billion credit from the World Bank, stating, "The APM condemns the attempt by President Tinubu to further mortgage the future of millions of Nigerians with a fresh $1.5bn credit from the World Bank."
The party also criticized the ongoing borrowing despite the government's revenue increase following the removal of the petrol subsidy.
Yusuf highlighted the consequences of these policies, noting that they have contributed to higher costs of essential goods and services, including food, electricity, transportation, healthcare, and other necessities. He also pointed out the struggles of millions of Nigerians with food insecurity amid rising living costs. The APM called on the World Bank, IMF, and other international lenders, including China and the United States, to refrain from providing additional credit to Nigeria.
They argued that Nigeria requires greater transparency, fiscal discipline, and investment in productive sectors instead of continued reliance on borrowing.
Written by urgent.news from Daily Post Nigeria's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.
This story
This is one outlet's version. Read the fullest account.