Steuern: Steuerfalle Wiesn – Chef-Runden im Bierzelt können teuer werden
Wenn Mitarbeiter auf Firmenkosten feiern, zählt das als geldwerter Vorteil. Der Fiskus gewährt hier einen Rabatt. Der gilt seit 2026 aber nicht mehr, wenn Führungskräfte allein feiern.
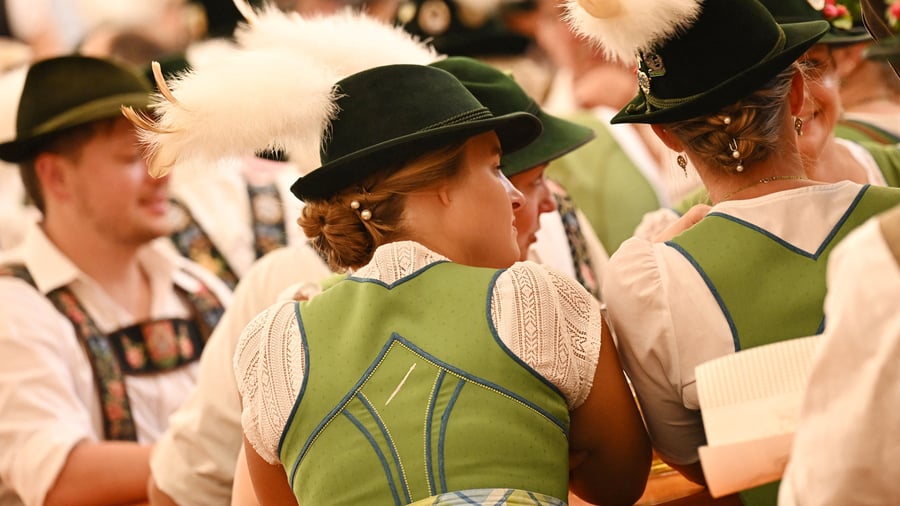
The biggest tax trap at Oktoberfest company outings is the guest list. Whether a celebration receives a tax benefit depends on who is invited. For exclusive events with executives, stricter rules have been in place since this year. If the boss spends on his employees, a taxable wage income, known as the "monetary advantage," quickly arises.
This means that the invitation is treated like wages for tax purposes. However, the government also recognizes that company parties can boost team spirit and therefore offers a tax advantage for such gatherings twice a year. Up to 110 euros per employee per event is tax-free for expenses related to food, venue rental, or even paying for the Ferris wheel.
Despite this, the state knows that company parties can strengthen team cohesion and therefore provides a tax benefit. Two times a year, employees can be invited if the improvement of workplace atmosphere is the main focus. Expenses of 110 euros gross per person are then tax-free per occasion. However, absentees can jeopardize the tax benefit.
Companies should not plan too tightly, as the total costs of a company party are not based on the invited, but on the actual attendees. If a person cancels at short notice, the per capita amount for those present increases. The 110 euros can also include travel costs. If the party is held outside the workplace, the costs incurred are either covered by the company's travel arrangement or hotel quota, which is included in the 110 euros.
Only individually arranged trips and overnight stays can be tax-free. If the amount exceeds this, the employee must pay social security on their own party. The company usually deducts 25 percent social security for such events, making the employee unaware of the incurred costs. The 110-euro rule can only be used if the event is open to all employees.
However, exclusive events with executives where only executives are invited do not qualify for the tax advantage. This was established in the 2026 annual tax law, despite the federal tax court previously deciding differently (case VI R 5/22). According to the legislator, a tax benefit granted to exclusive executives' gatherings violates the general principle of equality.
In such cases, the entire monetary advantage is subject to taxation. Companies also commonly deduct 30 percent social security for exclusive events, rather than the usual 25 percent. If customers are also present, the nature of the gathering determines the tax treatment. If employees are working at the event (for example, in customer service, booth service, or organization), no taxable wage income arises.
Written by urgent.news from Handelsblatt's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.
This story
This is one outlet's version. Read the fullest account.