August dip masks resilient auto market as EV demand accelerates
KUALA LUMPUR: Malaysia’s automotive sales momentum is expected to remain positive in the second half of 2026, supported by year-end promotions, stronger seasonal demand and continued electric vehicle (EV) adoption, said CGS International Securities Malaysia Sdn Bhd.
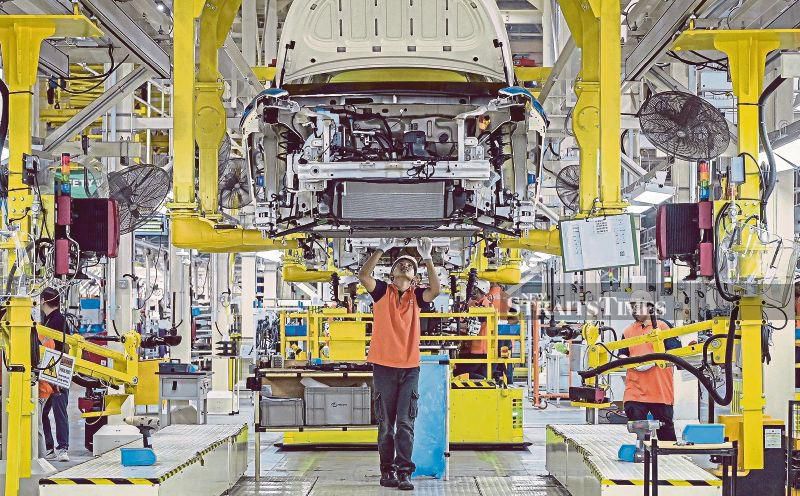
KUALA LUMPUR: Malaysia's automotive industry is anticipated to maintain positive growth in the second half of 2026, fueled by year-end promotions, heightened seasonal demand, and the increasing adoption of electric vehicles (EVs), according to CGS International Securities Malaysia Sdn Bhd. In August, total industry volume (TIV) reached 71,428 units, a three percent decrease compared to the previous month and a two percent drop year-on-year, primarily due to a high sales base from July and August of the previous year.
Despite the decline, August was the third-strongest month of the year, with monthly TIV surpassing 70,000 units. CGS International noted the nationwide decline affected major brands, though it was somewhat offset by stronger sales from Proton, Jaecoo, and Jetour. Proton sales increased 18 percent month-on-month in August, while Jaecoo and Jetour saw growth of 15 percent and two percent, respectively.
For the first eight months of 2026, TIV rose two percent year-on-year to 530,396 units, boosted by Proton, Mazda, BYD, and Jetour. The firm attributed this growth to promotional campaigns, new model launches, including Proton e.MAS and Saga, Mazda 3, and Proton S70 facelifts. EV demand remained robust, with Malaysia's EV market share reaching nine percent for the January-August period, up from 7.3 percent in the first seven months, fueled mainly by Proton and Tesla sales.
CGS International projected 2026 TIV at 780,000 units, a five percent decline from 2025, attributing this to the Kuala Lumpur International Mobility Show held in June and some demand forward-moving. However, they anticipate positive TIV momentum in the second half, with growth of about two percent year-on-year, supported by year-end promotions and increased car sales.
The extension of fuel subsidies to 300 liters could also bolster consumer sentiment and vehicle purchases. CGS International keeps an overweight position on the automotive sector, citing resilient consumer demand, sustained EV adoption, and sector-specific earnings catalysts. They cited potential triggers for sector re-rating as stronger-than-expected second-half TIV, sustained EV adoption, and resilient consumer demand, while weaker consumer demand and mounting price competition pose risks.
Within the sector, Sime Darby Bhd was their top pick, with an 'Add' recommendation and a target price of RM2.80, citing post-war reconstruction, industrial capacity rebuilding, and potential EV market demand in Australasia over 2027 and 2028. CGS International also maintained a cautiously optimistic outlook on Sime Darby's China automotive business, anticipating a gradual recovery in 2027, driven by BMW China rebates and the launch of BMW's Neue Klasse models.
Written by urgent.news from New Straits Times's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.