Alliance Bank's dividend outlook holds: Kenanga Research
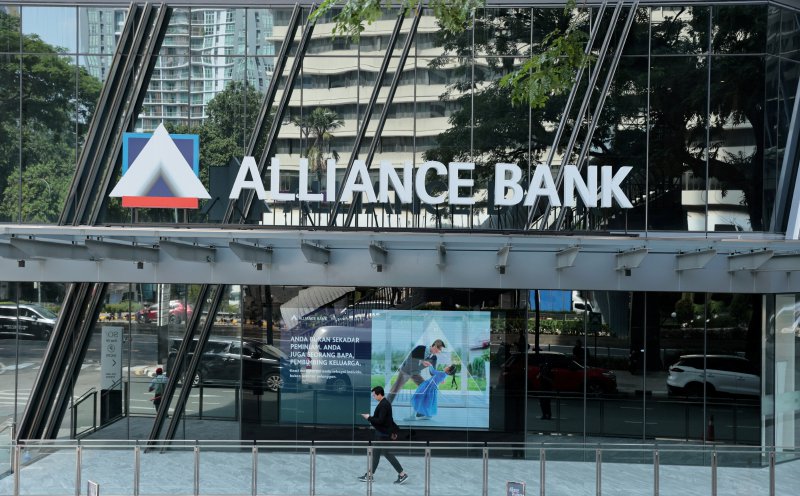
KUALA LUMPUR: Alliance Bank Malaysia Bhd’s dividend outlook remains intact despite higher bond yields, with the potential earnings impact from its fixed-income securities expected to be limited.
KUALA LUMPUR: Despite higher bond yields, Alliance Bank Malaysia Bhd's dividend outlook remains unchanged, according to Kenanga Research. The potential earnings impact from fixed income securities is estimated to be limited, with an increase in bond yields in the third quarter of 2026 expected to have a 1% effect on earnings only if those securities are classified as FVTPL.
However, the impact should be relatively small compared to other banks, as about 98% of required fixed income securities are in the FVOCI category, which are revalued through reserves rather than marked-to-market. With CET1 levels of 13.4%, the rise in Malaysian Government Securities (MGS) rates by 50 basis points since June still allows the bank to maintain a CET1 ratio above 13%, ensuring dividends are not at risk.
Alliance Bank also benefits from an additional 60-70 basis points of capital from the adoption of Basel III reforms. The bank's deposit competition remains, but its loan pipeline is favourable, with a loan-to-fund ratio of 87.7% as of June-end, providing room for improvement. This ratio is expected to approach the industry average of 82.3% as the bank increasingly relies on short-term wholesale funding, which may be less expensive than promotional fixed deposit rates.
Kenanga Research believes Alliance Bank's exposure to fixed income investment securities, revalued for profit and loss, offers a higher degree of earnings protection in the near term. The firm has maintained its Outperform rating for Alliance Bank with a target price of RM5.50 for its small-cap bank pick.
Written by urgent.news from New Straits Times's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.