Dangote’s refinery IPO deserves applause...and then some caution
Africa’s biggest initial public offering is attached to one of the continent’s greatest industrial achievements. After reading the 195-page prospectus, the company’s own disclosures give investors several reasons to slow down before paying ₦525 (~5 GHS) a share.
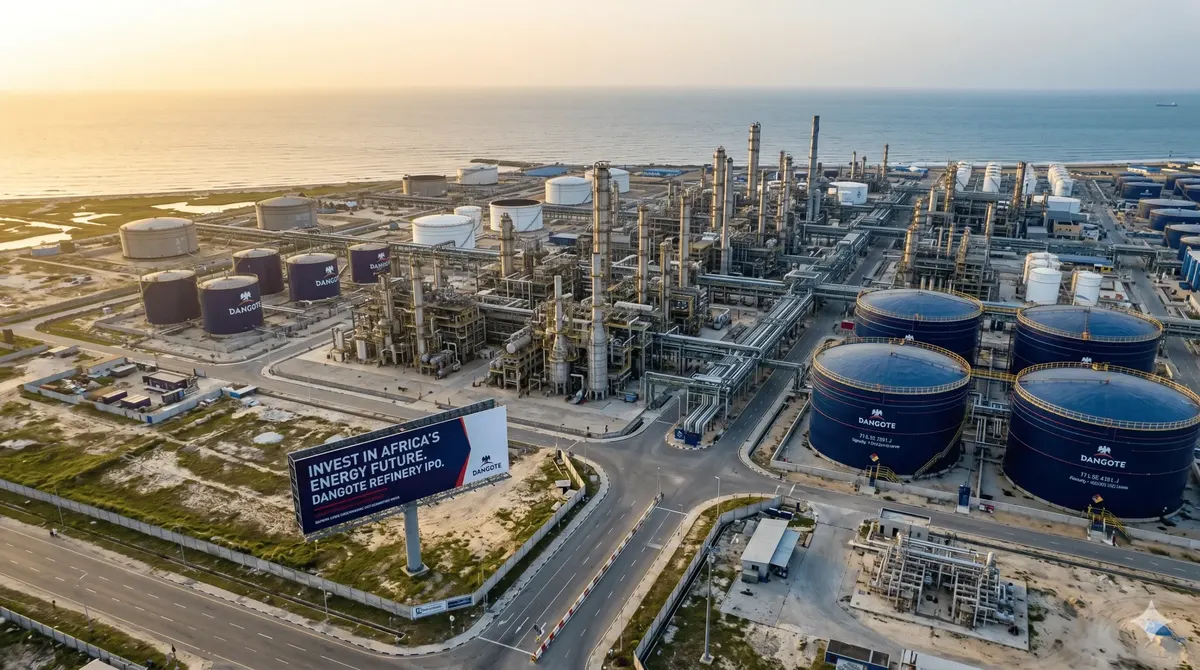
The Dangote Petroleum Refinery's initial public offering (IPO) is generating significant attention, with many viewing it as Africa's largest IPO. The refinery is a major African-owned project that has transformed crude from the continent into petrol, diesel, jet fuel, and petrochemicals on an unprecedented scale. Its IPO is widely praised, yet the valuation deserves a closer examination.
The 195-page prospectus, released on 7 September 2026, includes 22 pages of risk factors that provide a balanced view of the refinery's operations. The prospectus highlights several key risks, including the refinery's limited operating history, concentration at a single site, exposure to volatile margins, dependence on reliable crude and marine logistics, and the uncertainty surrounding the availability of an active market for its shares.
Additionally, the prospectus warns that dividends are not guaranteed and that offshore investors may face challenges with foreign exchange conversion and repatriation.
Despite these risks, the IPO has raised ₦2.1525 trillion, with net proceeds of approximately ₦2.111 trillion allocated to growth capital expenditure for the refinery's expansion. This allocation is a significant step towards reversing the traditional pattern of African businesses extracting value from the continent while building their deep capacity elsewhere.
The Dangote Refinery offers a tangible demonstration of African industrial ambition, moving from a country that imports refined products to one that can refine at scale.
However, the celebration of this industrial achievement should be tempered with a more cautious evaluation of the investment decision. The IPO price of ₦525 per share implies a market capitalisation of ₦65.22 trillion at listing. While the refinery's financial performance has improved, reporting a profit after tax of ₦2.50 billion in the first half of 2026, the company still reported a loss after tax of ₦723.06 billion in 2025.
The prospectus notes that commercial operations began in January 2024, and the refinery achieved full production levels only in June 2026. This limited history at operating levels raises questions about the sustainability of the recent earnings improvements.
Additionally, the prospectus highlights the cyclical nature of refining margins, which are heavily influenced by crude prices, product demand, global refining capacity, shipping routes, wars, and government policies. These factors introduce significant volatility into the refining business, making it challenging to predict future earnings with certainty. The company's reliance on free-zone incentives, which may become fully subject to Nigerian taxes from 1 January 2028, adds another layer of financial risk to consider.
Written by urgent.news from 3News's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.
This story
This is one outlet's version. Read the fullest account.