77% Would Choose Their Existing Financial App for a Digital Asset Wallet
Digital assets may reach the checkout faster by asking consumers to change less about how they pay. The July 2026 Payments Innovation Tracker, “From Asset to Everyday Money: Making Digital Currencies Spendable,” says cryptocurrencies and stablecoins are moving beyond investment. Consumers want to use them for purchases and transfers, but merchant acceptance, trust and fragmented […] The post 77%…
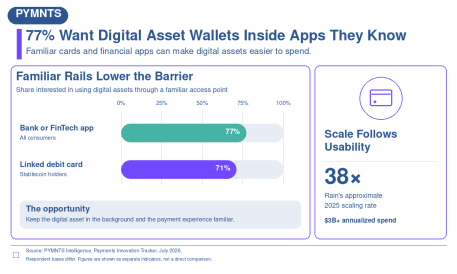
A July 2026 report highlights the potential for digital assets to transition from investments to everyday use. While consumers are eager to use cryptocurrencies and stablecoins for purchases and transfers, barriers like merchant acceptance and fragmented experiences hinder adoption. However, a third key finding offers a promising solution: linked cards, real-time conversion, and modern issuer-processing platforms can integrate digital assets into existing payment habits.
The report suggests that familiar apps, such as consumers' existing banking or FinTech apps, could make the switch to a crypto or stablecoin wallet more appealing. In fact, 77% of respondents say they would open a digital currency wallet through their current financial technology (FinTech) app if available. This advantage lies in the fact that banks and FinTechs already provide a login, customer relationship, and familiar interface that can make digital money feel less unfamiliar.
Linked debit cards can further facilitate acceptance, with 71% of stablecoin holders indicating they would use such a card to spend their assets. These cards function as a translator at checkout, converting digital assets at the point of sale, enabling transaction processing across existing payment rails, and allowing merchants to receive payments through familiar systems.
Modern processing technologies can streamline this process, turning interest into scale. Notably, Rain, a digital asset issuer, experienced significant growth after securing direct Visa network membership, scaling roughly 38-fold in 2025 and reaching over $3 billion in annualized spending. The report also emphasizes the importance of infrastructure to support wider reach and faster program development.
Looking beyond consumer cards, the report notes that business-to-business cross-border transfers already dominate global stablecoin payment volume, driven by faster settlement, lower costs, and access to dollar-linked value in volatile markets. However, consumer demand for using digital assets for major purchases remains high, with 42% of stablecoin holders expressing this desire, while 28% already do so.
Limited merchant acceptance continues to be a significant barrier, cited by nearly half of stablecoin holders as a reason for not using digital assets. Regulation may play a crucial role in bridging this gap. Europe's Markets in Crypto-Assets (MiCA) rules and the United States' GENIUS Act have established clearer standards for issuers and service providers.
The next step is to provide consumers with a trusted and seamless way to spend digital assets without requiring them to learn a new payment system.
Written by urgent.news from PYMNTS's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.