Lowe’s Companies (LOW) Shows Profit Resilience, But Housing Headwinds Persist
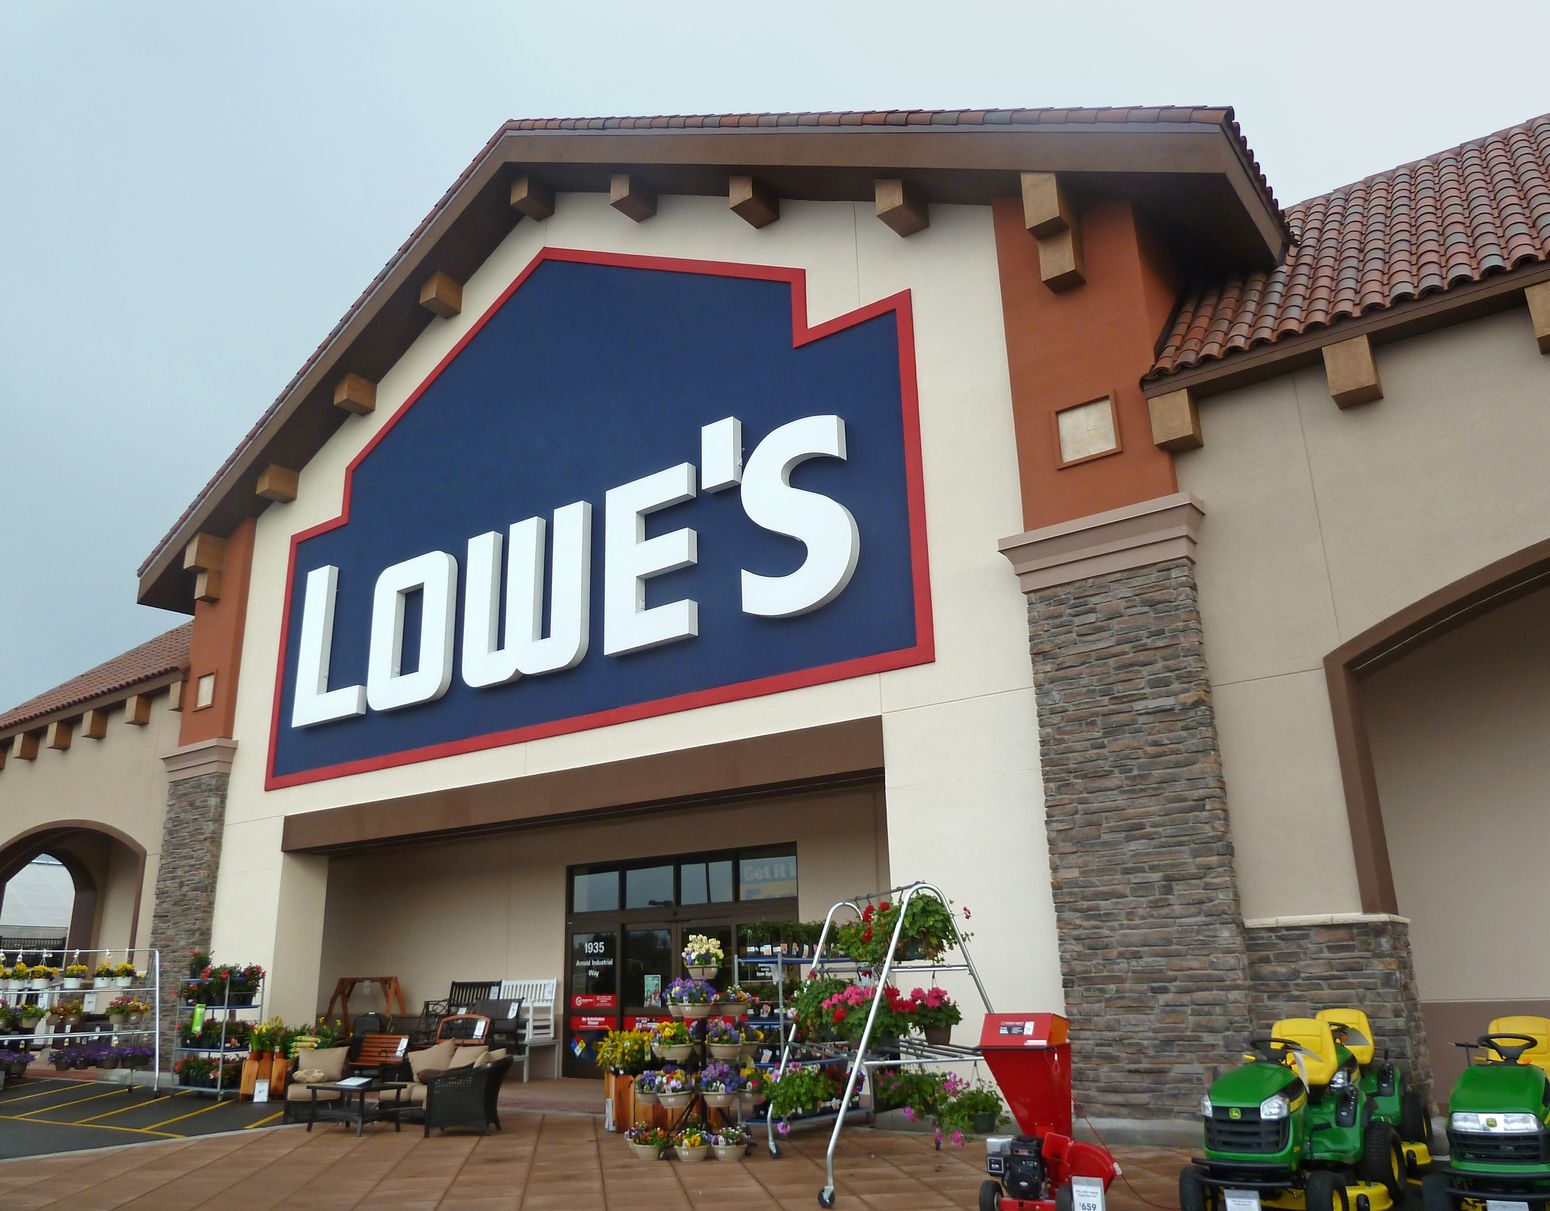
Lowe's Companies, Inc. (NYSE:LOW) reported mixed second-quarter results, with earnings per share (EPS) beating expectations, but sales falling short of estimates. The company's EPS stood at $4.27, surpassing the $4.22 consensus. Meanwhile, sales for the quarter totaled $25.96 billion, falling below the anticipated $26.16 billion. Comparable sales also experienced a slowdown, rising by only 0.2% against the predicted 0.8%.
The disappointing sales figure is attributed more to cautious consumer behavior and broader housing market conditions rather than a significant execution issue at Lowe's. The company is witnessing improved momentum from professional customers, home services, and online sales, as homeowners continue to invest in necessary repairs despite postponing larger remodeling projects. This suggests that Lowe's has a relatively defensive source of demand, with customers still willing to spend on essential repairs.
One promising aspect of the quarter is Lowe's continued growth with professional customers, who generally make larger and more frequent purchases than DIY shoppers. This trend bodes well for the company's long-term prospects, as expanding its presence among professional customers could offset some of the weakness experienced among ordinary homeowners.
Lowe's has also been investing in its Pro offering, including its recent acquisition of Foundation Building Materials, aimed at expanding its presence among professional customers.
Despite the sales miss and lower guidance, Lowe's shares experienced a 4% initial rise following the results, indicating that investors may have anticipated a challenging quarter. However, the earnings beat should not overshadow the fact that sales fell short of expectations. While Lowe's has managed to maintain its margins and generate solid earnings, sustained sales growth remains crucial for driving long-term earnings growth, especially given the prevailing housing and interest-rate environment.
The company's expectations for comparable sales have now been revised to flat, reflecting management's belief that demand conditions are unlikely to improve significantly in the near term. This downgrade comes in the wake of a quarter where Home Depot managed to meet its full-year targets, adding to the challenge for Lowe's in comparing its performance. The professional customer segment is providing some relief, but Lowe's still needs its large base of DIY shoppers to recover for the company's long-term growth.
One notable point is that Lowe's accounted for tariff refunds recognized during the quarter, which could prove useful for investors in distinguishing between sustainable operational improvements and one-off or unusual items. If sales remain weak, Lowe's will eventually require genuine productivity and market-share gains to support earnings, rather than relying solely on favorable adjustments or refunds.
Comparing Lowe's results to those of its larger rival, Home Depot, which beat quarterly expectations and maintained its full-year targets, raises questions about Lowe's execution relative to the competitor. While Lowe's is showing better profitability than sales performance, the company will need to focus on genuine productivity and market-share gains to sustain earnings growth in the face of ongoing housing and interest-rate pressures.
Written by urgent.news from Yahoo Finance's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.