Tata Motors PV Shares Fall 4.5% After Q1 Profit Plunges 80%
Shares of Tata Motors Passenger Vehicles Ltd declined 4.5% in early trading on Friday, making it the biggest loser on the Nifty 50 after the company reported a sharp decline in Q1 FY27 profit and continued pressure on margins. The stock traded near Rs 334 after closing at Rs 349.60 on Thursday. It has fallen around 9% so far in 2026, compared with a 6.7% decline in the benchmark Nifty 50. Tata…
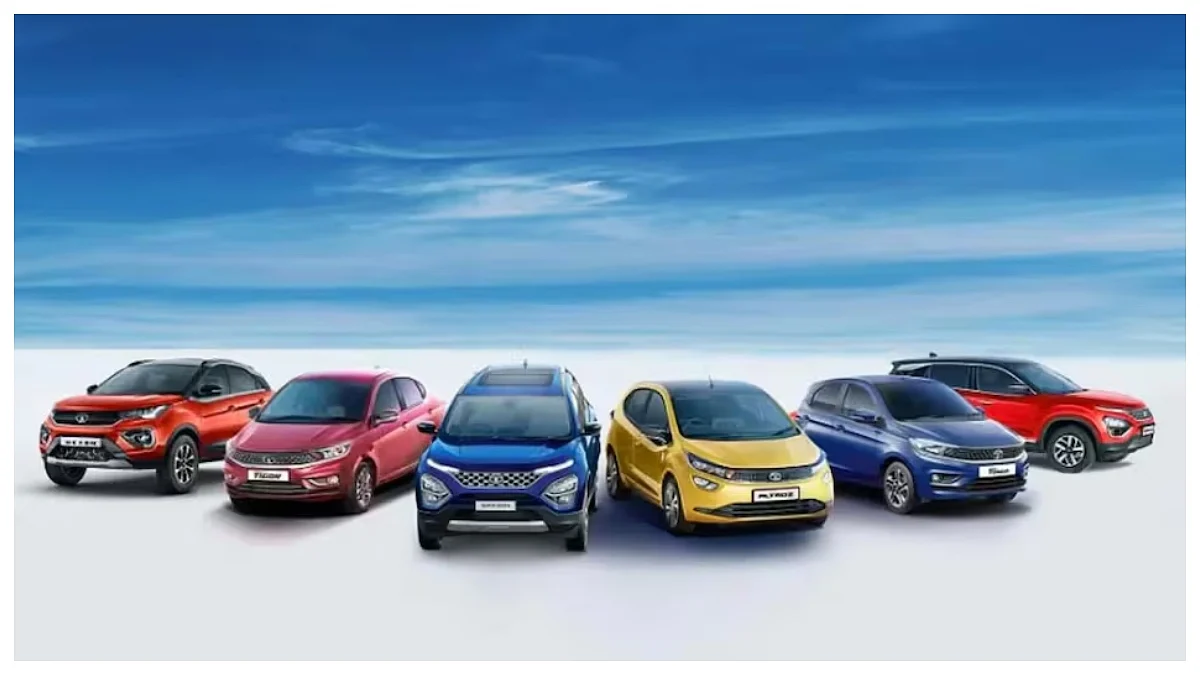
Tata Motors Passenger Vehicles Ltd shares plummeted 4.5% in early trading on Friday, marking the biggest decline among Nifty 50 stocks. This dramatic drop followed the company's announcement of an 80% plunge in Q1 FY27 profit and ongoing pressure on margins. As of Thursday's close, the stock was trading at Rs 349.60, a level slightly below the Rs 334 range it had been hovering in earlier.
Over the past year, Tata Motors PV shares have lost around 9%, trailing the broader Nifty 50's 6.7% decline. The company disclosed an 80% year-over-year dip in consolidated net profit attributable to shareholders, settling at Rs 775 crore. In contrast, revenue from operations rose a modest 9.2% to Rs 95,799 crore. Profit before exceptional items and taxes fell by 59% to Rs 1,606 crore.
Tata Motors PV's domestic passenger vehicle division saw a 65% revenue increase, but the company attributed its profitability woes to surging commodity costs and unfavorable foreign-exchange movements. The firm's consolidated free cash flow turned negative at Rs 11,800 crore, largely due to seasonal working capital needs. Market analysts have varying views on Tata Motors PV's future trajectory.
CLSA remains optimistic, maintaining an 'Outperform' rating and a target price of Rs 452, suggesting potential upside of more than 29%. They credit JLR's EBIT margin beating expectations, despite domestic PV EBITDA underperforming forecasts. CLSA expects strong demand for JLR vehicles, projecting monthly dispatches of 65,000-70,000 units as inventory builds up for the festive season.
Nomura holds a neutral stance with a Rs 389 price target, citing robust domestic demand but significant cost pressures. HSBC keeps a 'Hold' rating while lowering its target to Rs 360, warning that ongoing commodity-related margin pressure could persist into the next quarter. Citi remains bearish, retaining its 'Sell' rating with a Rs 305 target, noting that Q1 performance fell significantly short of expectations across both JLR and the India Passenger Vehicle segment.
JLR's wholesale sales dropped 9.2% due to supply chain disruptions, the Middle East conflict, and plans for a Jaguar wind-down. However, management remains confident about robust domestic volume growth and double-digit JLR revenue expansion, buoyed by upcoming model launches.
Written by urgent.news from Free Press Journal's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.
This story
This is one outlet's version. Read the fullest account.
- Tata Motors PV shares fall 5% after weak Q1 results. What are Morgan Stanley, Nomura, others saying? economictimes.indiatimes.com