Woman’s Rs 25,000 rebate denied under new regime for capital gains; what ITAT said
A woman filed her income tax return for assessment year 2025-26, declaring a total income of Rs 6,77,511. This included short-term capital gains of Rs 3,97,511 arising from the transfer of listed equity shares. Such gains are taxable u/s 111A of the Act at a special rate of tax. She opted for the new tax regime under Section 115BAC(1A) and claimed a rebate of Rs 25,000 under Section 87A.
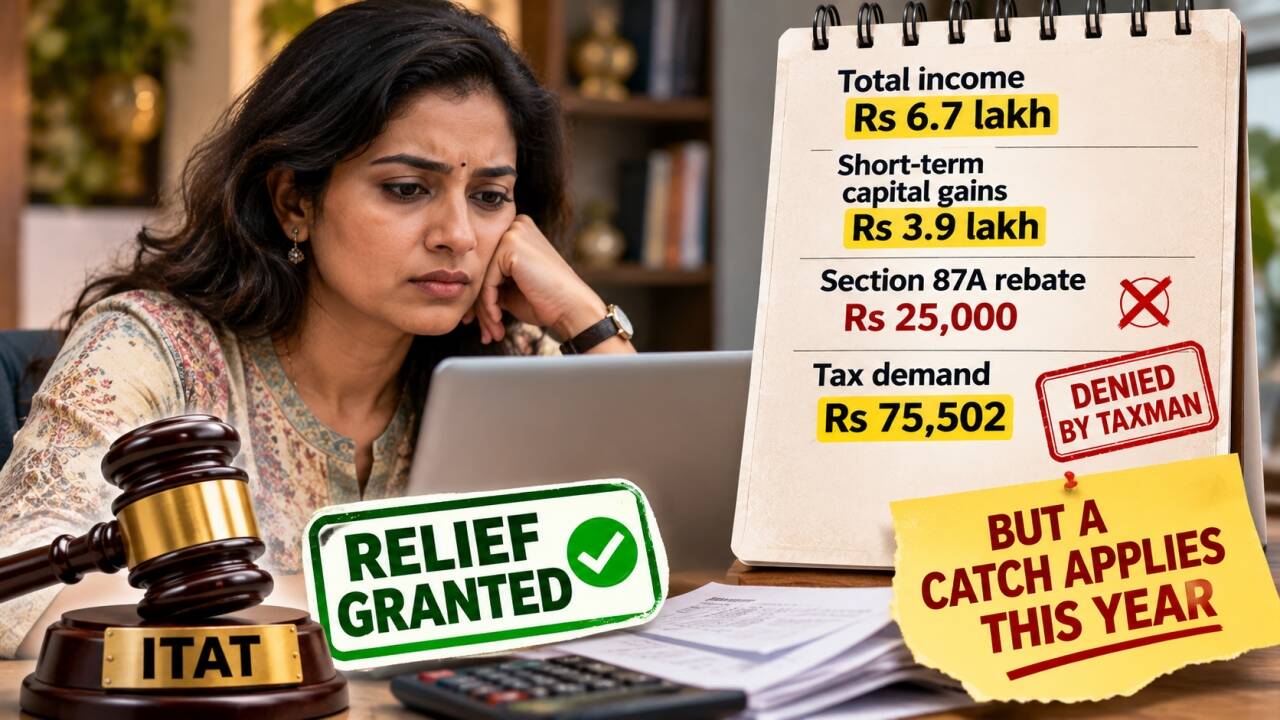
A woman successfully challenged the denial of a Rs 25,000 income tax rebate for her short-term capital gains, despite her overall income falling below the Rs 12 lakh threshold. The Income Tax Appellate Tribunal (ITAT) in Hyderabad ruled in her favor, holding that Section 87A of the Income Tax Act, 1961, does not prohibit the rebate when income includes short-term capital gains taxable under Section 111A of the Act at a special rate.
The case centered around the woman's filing of an income tax return for assessment year 2025-26, with a total income of Rs 6,77,511, including Rs 3,97,511 in short-term capital gains. She opted for the new tax regime under Section 115BAC(1A) and claimed the rebate under Section 87A, but the Centralised Processing Centre (CPC) determined a tax payable of Rs 75,502 without allowing the rebate.
The taxpayer appealed this decision, and the ITAT held that the rebate should be allowed, citing earlier tribunal decisions and the plain language of the statute. The ruling is significant for taxpayers, particularly for earlier assessment years, and underscores the principle that a circular cannot override provisions of the Act.
However, it is important to note that this rebate is no longer available from FY 2025-26 onward, as the Finance Act, 2025 has expressly restricted the Section 87A rebate to tax calculated at specified slab rates.
Written by urgent.news from Times of India's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.