Does Options Delta Really Predict the Probability of Expiring In the Money?
Is a 30-delta option a 30% chance? Black-Scholes math and four real option chains show when delta works as odds and when it is far off.
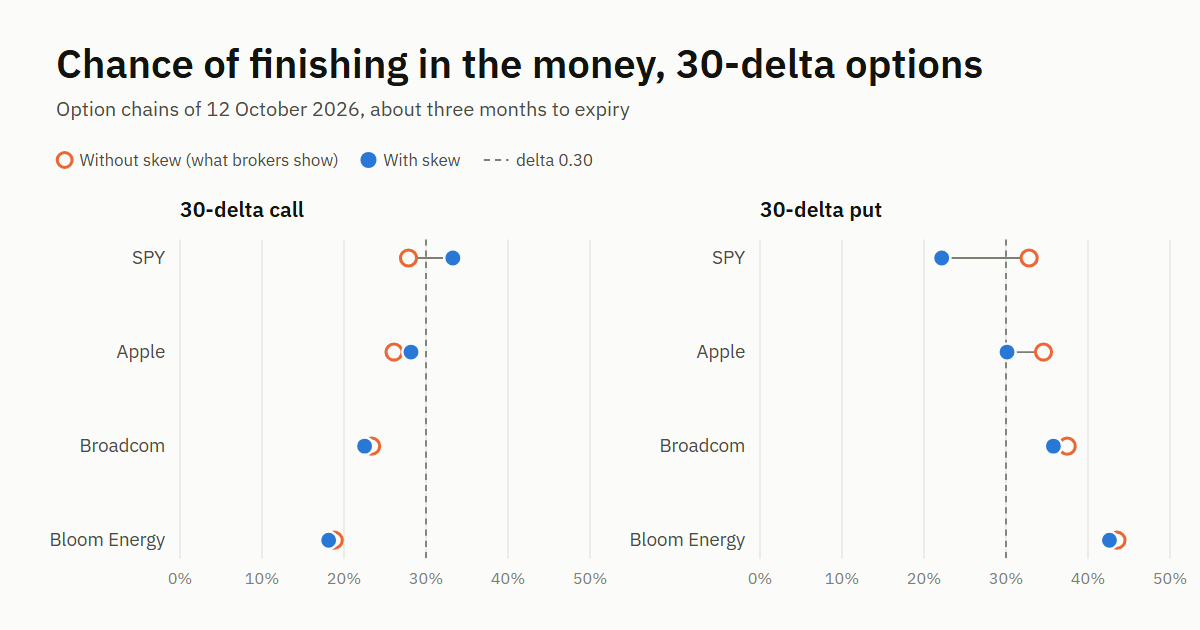
Delta is a measure of how much an option's price moves when the underlying stock moves by one dollar. It is not a probability and runs from 0 to 1 for calls and from 0 to -1 for puts. In the Black-Scholes model, call delta equals the standard normal distribution N(d1), while probability of finishing in the money for calls equals N(d2).
For puts, the probability ends up above delta, and for calls, below. Delta and probability differ because the textbook model assumes one volatility for all strikes, while real option chains have different implied volatilities for each strike, known as the volatility skew. This skew affects the odds, with steep skew pushing put probabilities below delta and call probabilities above delta, while high volatility and long expiries push them the other way.
Written by urgent.news from HackerNoon's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.