Chart Crimes: HELOC Edition
Got home last night at midnight cause the Amtrak from Philly was a disaster (I’ll ignore the coincidences for now)1. So the longer discussion on Biases, Filter Bubbles ,and Investing Errors will have to wait. Right on cue, this beauty popped up. The problem is less about the chart itself than it is… Read More The post Chart Crimes: HELOC Edition appeared first on The Big Picture .
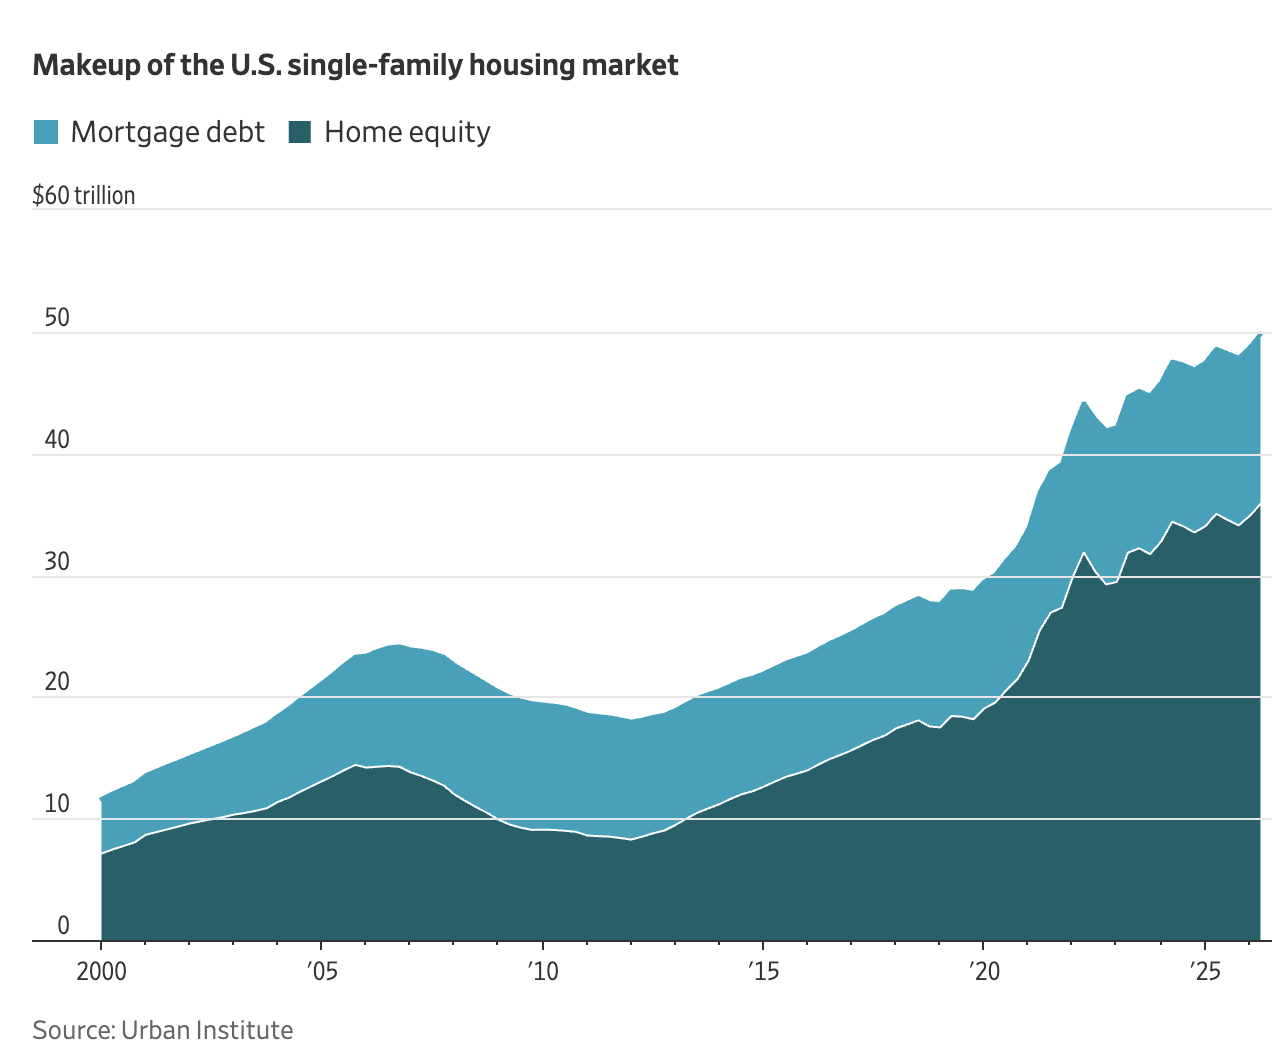
A recent article from the Wall Street Journal titled "These Charts Show How More People Are Pulling Cash Out of Their Homes" indicates that people are increasingly using home equity lines of credit (HELOCs). The article's author argues that HELOCs are becoming popular once again as people seek to avoid giving up their low-rate primary mortgages. However, the author of this report believes the headline is misleading.
The chart that the article begins with appears to show that home equity has closely tracked the value of mortgage debt, which in turn tracks the value of residential real estate. In 2022, home equity reached its peak at 72% of total value, equal to the $32 trillion mark. In 2019, it stood at 63%, while in 2012, it dipped to 46%. Mortgage debt increased from approximately $12 trillion to $14 trillion since 2022, growing by about 14%. Similarly, the total housing value rose by around the same 14%.
This growth in mortgage debt can be attributed to an increase in the value of homes. Therefore, higher home equity is not surprising, as it is a natural consequence of this growth. The loan-to-value ratio remains flat at around 28%, suggesting that the percentage of home equity is not growing at a faster rate than the underlying value of homes.
The author draws a comparison to the NYSE margin panic that occurred in 2015. At that time, the percentage of margin debt was rising, but it was not considered alarming because it was in line with the overall growth of the economy and inflation. Similarly, in this case, the increase in home equity may not be newsworthy since it is growing in line with the overall housing market growth and inflation.
The report concludes by referencing a previous piece titled "Margin Debt Hits an All-Time High. . . So What?" (April 29, 2015), emphasizing that rising percentages or numbers in isolation do not necessarily warrant alarm. Instead, one must look at the percentage of home equity increasing faster than the underlying value of homes to identify a real problem.
Written by urgent.news from The Big Picture's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.