RHB keeps "Buy" on Johor Plantations, cuts target price to RM2.00
KUALA LUMPUR: RHB Research has maintained its ‘Buy’ recommendation on Johor Plantations Group Bhd (JPG), lowering its target price to RM2.00 from RM2.20 following its third-quarter earnings recovery.
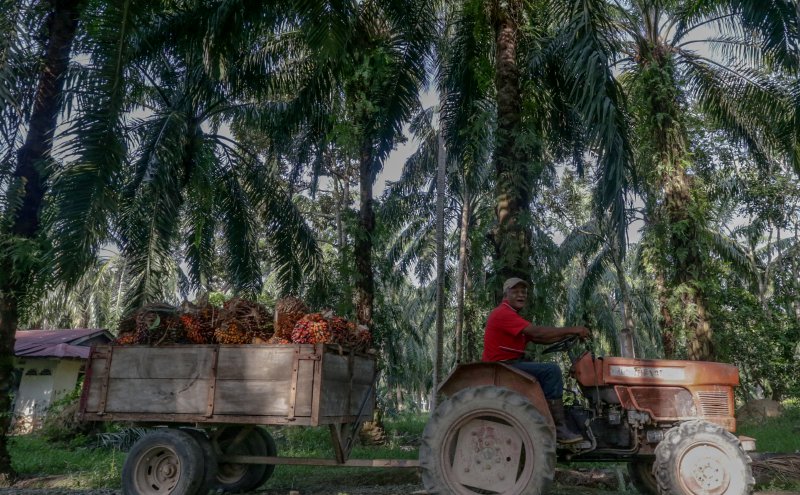
RHB Research has kept its Buy rating on Johor Plantations Group Bhd (JPG) while cutting its target price to RM2.00 from RM2.20. This reduction comes following the company's strong third-quarter earnings recovery. The revised price represents an upside potential of 11.1% from the current market price of RM1.80.
In its note, RHB Research highlighted that JPG's Q2FY2026 core profit had doubled quarter-on-quarter, driven by higher fresh fruit bunch (FFB) production and lower unit costs. However, core profit declined 13% year-on-year, representing 70% and 63% of RHB Research's full-year and consensus estimates, respectively. The firm expects a seasonal recovery in Q4FY2026 FFB output, partially offset by weaker CPO average selling prices.
FFB production rose 35.6% QoQ, while the 12.6% YoY decline was attributed to the seasonal crop cycle. The research firm noted that improved weather conditions contributed to the profit recovery, although overall production remained weaker, with nine-month FY2026 FFB output down 11.8% YoY. Despite this, management remains confident that FY2026 FFB output will exceed the 1 million tonnes mark.
JPG recorded a CPO average selling price (ASP) of RM4,683 per tonne in Q2FY2026, up 0.8% QoQ and 6.6% YoY. The company secured premium pricing for its entire FY2026 output, with 70% under identity preserved at RM200 to RM250 per tonne and the remaining 30% under mass balance at a premium of RM100 to RM150 per tonne. However, CPO unit costs increased 10.9% YoY to RM2,557 per tonne due to higher input costs.
RHB Research has adjusted its FY2026 to FY2028 earnings estimates by 2.9%, 8.4%, and 6.4% after accounting for higher unit costs and lower palm kernel ASP premium. Despite these adjustments, the firm maintains that JPG's strong environmental, social, and governance credentials support its ability to command premium selling prices. Additionally, the upcoming Integrated Sustainable Palm Oil Complex should bolster JPG's downstream operations and aid its transition into a fully integrated plantation group.
Written by urgent.news from New Straits Times's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.