Flowers Foods Feels the Squeeze As Americans Put Affordability First
Flowers Foods, Inc. (NYSE:FLO) stock is trading lower during Friday’s premarket session after the company reported weaker-than-expected third-quarter results and lowered its full-year 2026 outlook . The company produces packaged bakery foods and operates brands including Nature’s Own, Dave’s Killer Bread, Canyon Bakehouse, Simple Mills, Wonder, and Tastykake. Chairman and CEO Ryals McMullian…
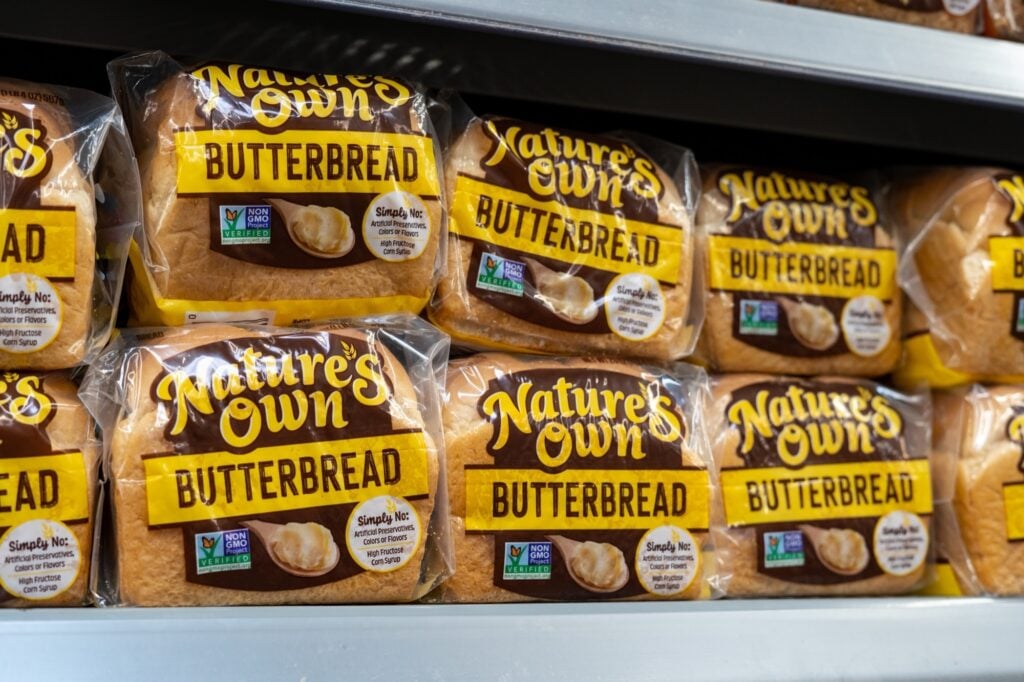
Flowers Foods, a major producer of packaged bakery foods with brands such as Nature's Own and Wonder, experienced a decline in its stock price on Friday after the company reported disappointing third-quarter results and revised its full-year 2026 outlook. The company's Chairman and CEO, Ryals McMullian, attributed the underperformance to consumer budget constraints, shifting consumer behavior, and increased promotional competition.
Consumers are increasingly opting for smaller loaves and alternative products, while aggressive promotions are intensifying market competition. Despite the launch of a relaunched Nature's Own brand featuring fewer ingredients and new product introductions, Flowers Foods acknowledged that the earlier pricing adjustments and brand relaunch have not produced the anticipated improvements, particularly in traditional loaf bread, a category facing ongoing challenges.
The company's financial performance fell short of expectations, with adjusted earnings per share at 10 cents, falling short of the analyst estimate of 15 cents, and revenue dropping 4.7% year-over-year to $1.169 billion, below the projected $1.180 billion. Net sales decline was mainly due to a 7.0% decrease in volume, despite a 2.3% favorable price/mix. Branded retail sales fell 5.1% to $772.1 million, as lower volumes couldn't offset the positive impact of pricing/mix.
Adjusted EBITDA fell 33.2% to $78.9 million, with the adjusted EBITDA margin decreasing by 280 basis points to 6.8%. Net income plunged 63.6% to $14.4 million, primarily due to reduced sales volumes, higher marketing expenses, increased logistics costs, and greater purchases of outside products. To some extent, lower incentive compensation, ingredient costs, and distributor fees offset these challenges.
For the fiscal year 2026, Flowers Foods revised its revenue forecast to $5.016 billion-$5.063 billion, down from the previous range of $5.070 billion-$5.142 billion, which was below the analyst's estimate of $5.086 billion. They also adjusted their earnings projection to $63 cents-$68 cents per share from the earlier estimate of $75 cents-$85 cents, missing Wall Street's expected 77 cents.
The company expects near-term market conditions to remain difficult but remains optimistic about long-term opportunities in fresh packaged bread, cakes, better-for-you snacks, and foodservice.
Written by urgent.news from Benzinga's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.