Monzo ofrece un 4% por el ahorro para competir con la banca tradicional
El neobanco de origen británico se estrena hoy en el mercado doméstico con una estrategia centrada en el pasivo y el objetivo de captar clientes de la banca tradicional. Leer
The British neobank Monzo Bank is launching its services in the Spanish domestic market with a focus on passive income and the goal of attracting customers from traditional banking. Digital banking is already a well-established reality in the financial system, with Spain being a good example. Around thirty neobanks and digital platforms offer their services in the Iberian market to a clientele that is increasingly perceiving these entities as an alternative to traditional banking.
Today, the list of digital banks grows. Monzo Bank, a British neobank, officially starts its operations in Spain with the ambition to replicate the success that has made it one of the most recognized financial brands in the United Kingdom. In its native market, Monzo Bank has over 16 million customers, half of whom use it as their primary bank.
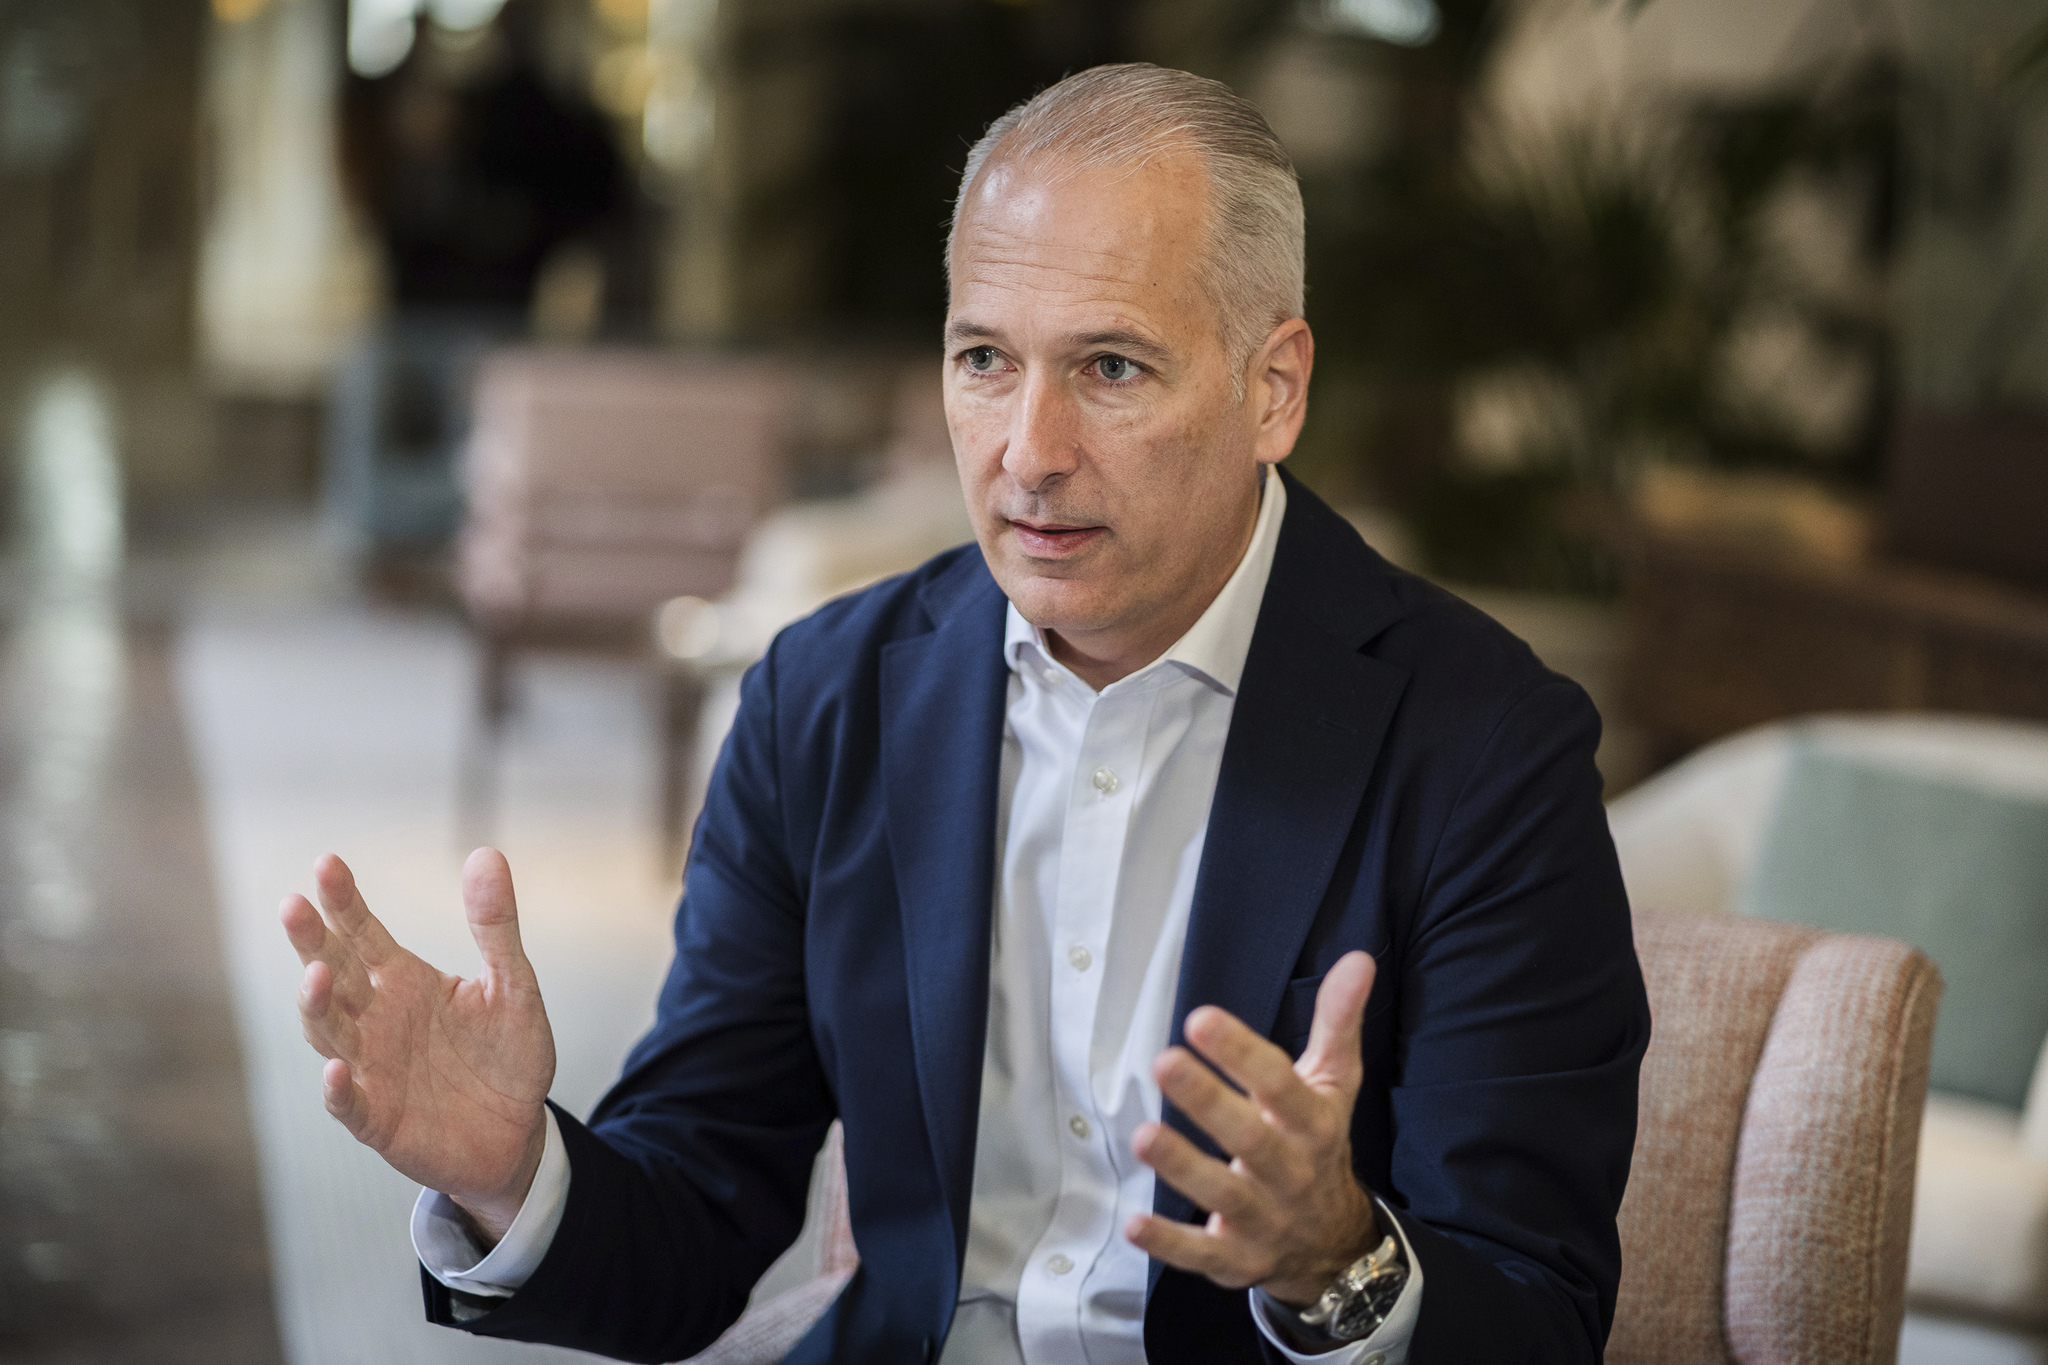
Francisco Sierra, the general director of Monzo Bank in Spain, assures in an interview with EXPANSIÓN, the first since assuming the position, that the ambition remains the same as in the United Kingdom: to be the leading bank in terms of the number of clients and activity. To achieve this, the neobank is presenting the market with an account that pays 4% on the first 5,000 euros for the first year, and 2.5% for the rest of the savings.
The account has a Spanish IBAN and Bizum from the first moment. Monzo starts by setting up machines in the banking pole that bets on passive income. Sierra assures that there is not a totally defined niche of clients. We are focusing on individuals, families, and businesses. These are the three segments we care about, those centered on day-to-day, what we call daily banking, which is everything related to accounts, cards, transfers, and savings.
The online firm detects a growth opportunity in the world of payments. According to Sierra, a bank is leading when a client uses it for daily transactions, such as clearing checks, making transfers or Bizums, or depositing any expense. Our goal is to start with a product so that we use it. Monzo is in an exploratory phase to see what other products could fit in its catalog.
The starting point is to capture enough customers to, in the medium-long term, be able to listen to their requests and know the type of products they require. The neobank will not initially offer credit. It is a capital-demanding business that could not be profitable in the first months of operation in Spain. However, Sierra does not close the door to this part of the business.
We are not launching credit, but we are exploring for when we are established, to see how we can reach that market. Similarly, the general director does not rule out including mortgages in the catalog in the future. It is the banking product par excellence and an anchor to have clients in the long term. On the other hand, Monzo also studies the way to enter the investment business.
It is a market where demand has grown in recent years and very closely linked to neobanking, which tends to offer investment solutions and several tools at a reduced cost. Investment also forms part of our exploration. We are analyzing products, but after the first months, we want to launch the investment part, indicates Sierra.
Sierra does not set a moment when Monzo will be profitable in Spain. The director trusts that with the application of the strategy and all the resources it provides from the matrix, they will be able to grow quickly in the Iberian market. The general director believes there is enough space in the Spanish banking sector for a new digital competitor to develop a strategy from zero.
According to the director, Monzo competes against all entities, digital or traditional. For this reason, Sierra trusts in quickly capturing users from other banks, especially from traditional banking.
Written by urgent.news from Expansion ES's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.