A choice between debt and inflation: As protests rage, the French government has no good option for solving its financial problems
Protests in France have brought hundreds of thousands of people onto the streets demanding higher wages, lower inflation, and more funding for hostpitals and schools. The government, meanwhile, is trying to cut spending on benefits, pensions, and public-sector salaries as part of an effort to curb the growth of a record-high public debt that has already reached 119% of GDP. Borrowing costs are…
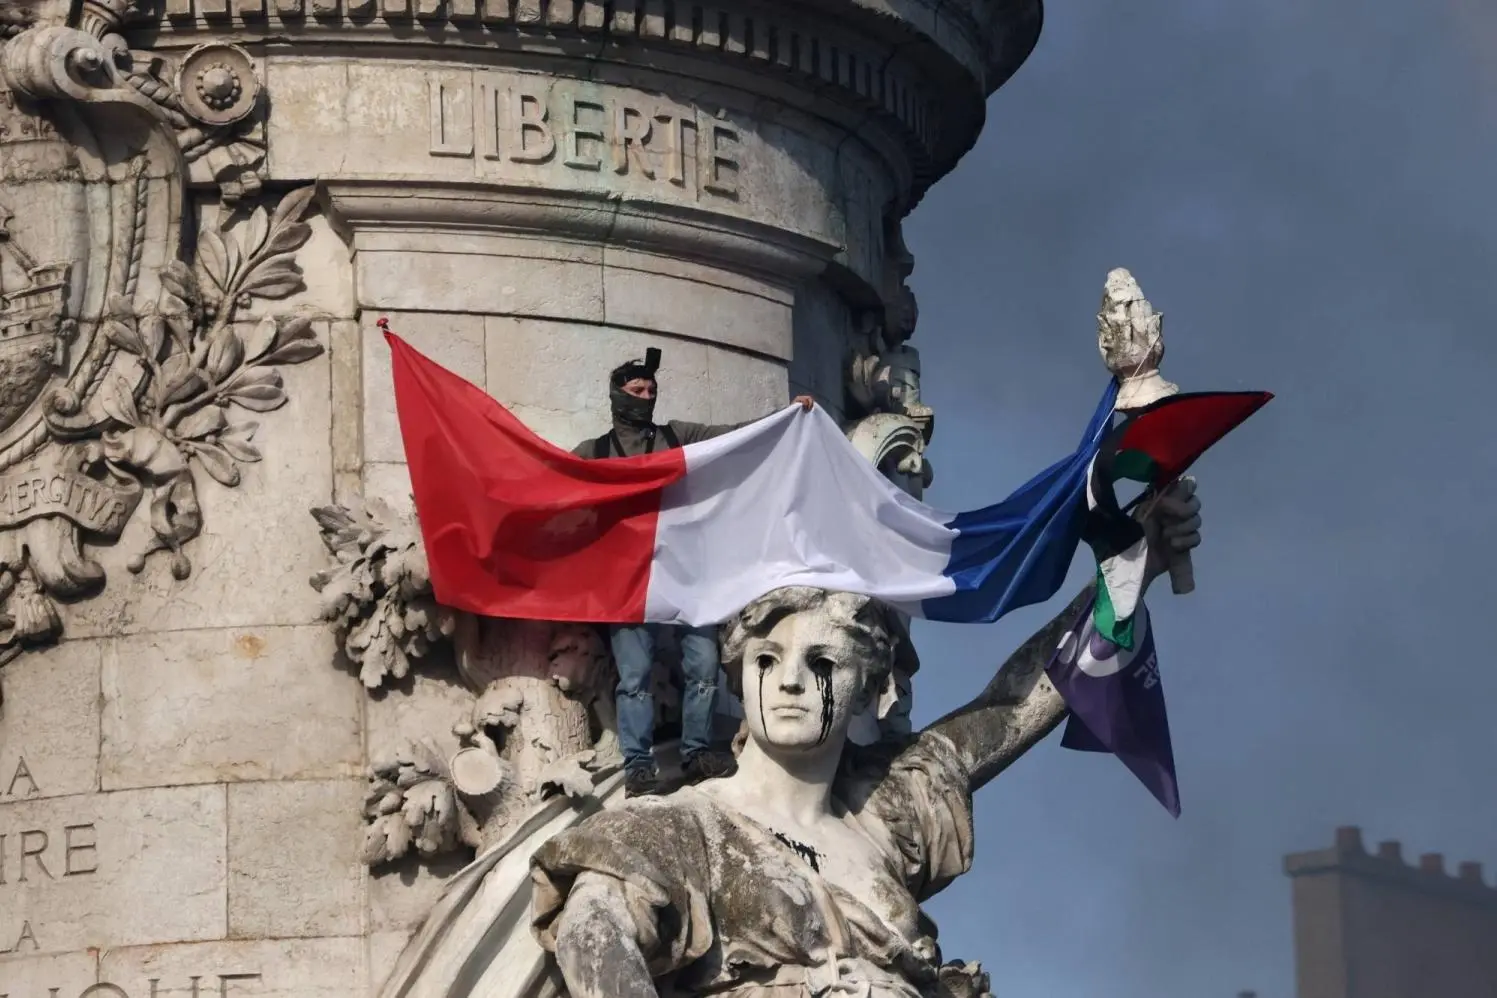
Parisians took to the streets in protest on October 17, depicting the growing discontent with the French government's financial situation. The Interior Ministry reported 550,000 protesters, while organizers claimed 800,000 participated. Public frustration escalated in late September after a blockade of a Paris high school, with students voicing concerns over teacher scarcity, overcrowded classrooms, and dilapidated schools.
As the protests expanded to include trade unions and the Yellow Vests, demands grew to encompass increased funding for hospitals, higher wages, lower fuel prices, and wealth redistribution.
In Limoges, the city hall was burned; in Marseille, protesters breached a government building; and in Paris, stores were looted. President Emmanuel Macron addressed the nation, acknowledging "anger and shame" but refraining from discussing financial solutions, as the 2027 budget was under debate and required France's creditors to trust the country's ability to control its growing debt.
France's public debt, currently at €3.6 trillion (119% of GDP), is an all-time high and accelerating. Debt servicing costs are soaring, with the public sector paying €91.2 billion in interest next year, up from €79.2 billion this year. Interest payments will surpass both defense (€64 billion) and education (€62.2 billion) expenditures.
Even excluding civil-service pensions, interest payments are now the government's largest spending category.
Bond yields for France peaked at 5% in October, the highest since 2002, more than 1.4% higher than Germany's 3.4% yield, a widening gap not seen since the 2012 eurozone crisis. French officials projected a 5% budget deficit in 2027, but without the measures implemented, the deficit could reach 6.4%. To maintain a stable debt-to-GDP ratio, France needs to cut its deficit by roughly 3.5 percentage points of GDP, according to Fitch.
This stark contrast with countries like Sweden, which manages a generous welfare state alongside low public debt, highlights the unique challenges facing France.
While France spends more on healthcare and education than other nations, its debt-to-GDP ratio remains disconcertingly high. The French economy grew more slowly in 2025 than its European counterparts, but expanded faster than Germany's. However, the growth trajectory is uncertain, with weak consumer spending, rising borrowing costs, and hesitancy among businesses impeding progress.
Energy price fluctuations from the Middle East conflict are exacerbating the situation, with the Bank of France predicting a 0.7% fall in purchasing power for wages in 2026 and unemployment reaching 8.4%. The economic slowdown is directly impacting public finances, with the 2026 budget deficit projected at 5.4% of GDP—exceeding the government's 5% target.
Fitch attributes the deficit to the economic slowdown and rising interest payments on debt. The French government's predicament reflects both a spending issue and a fiscal crisis.
Written by urgent.news from The Insider's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.