Income Tax Form 161 Revised, Taxpayers Must Pay Up To 120% Additional Tax For Penalty Waiver
New Delhi: The Central Board of Direct Taxes (CBDT) has revised Form 161, introducing fresh disclosure and payment requirements for taxpayers seeking a waiver of penalty under the Income-tax Act, 2025. The changes were notified on October 8 through the Income-tax (Sixth Amendment) Rules, 2026. The revised form applies to applications filed under Section 440(2) of the Act. What Has Changed? The…
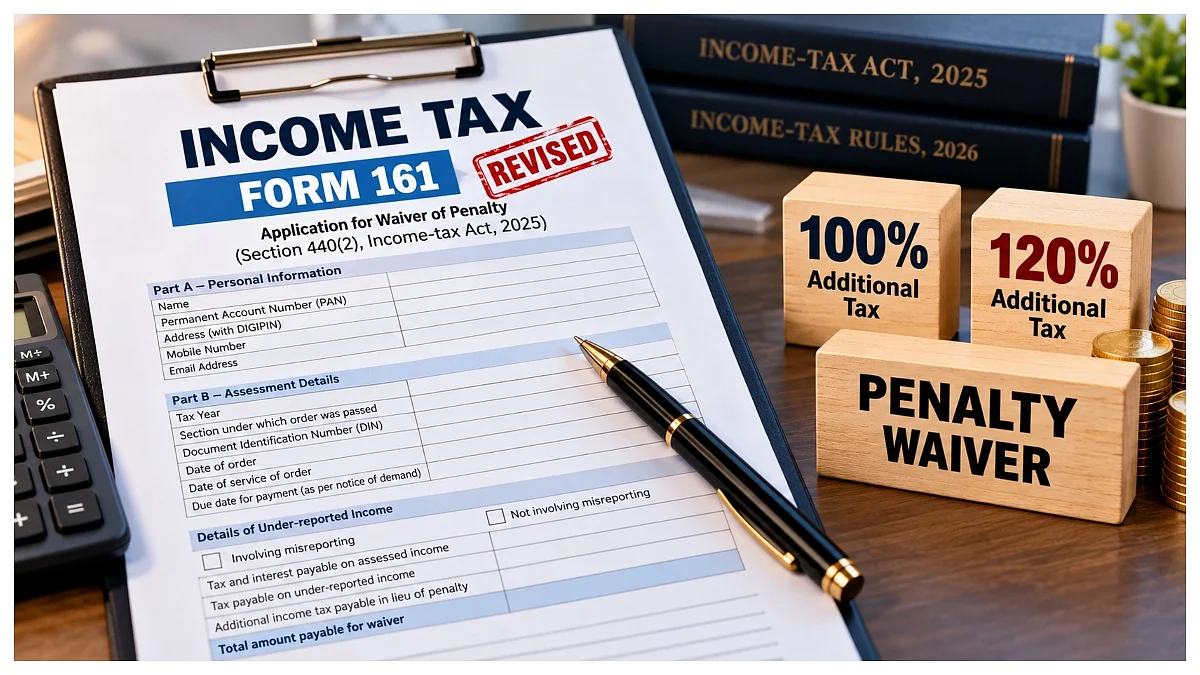
The Central Board of Direct Taxes (CBDT) has updated Form 161, implementing new requirements for taxpayers seeking a penalty waiver under the Income-tax Act, 2025. The modifications were officially announced on October 8 via the Income-tax (Sixth Amendment) Rules, 2026. This revision is applicable to applications submitted under Section 440(2) of the Act.
What Modifications Were Made? The amendment to Rule 231 of the Income-tax Rules, 2026, adds the words "or waiver" after "imposition." Furthermore, the original Form 161 has been replaced with a revised version that requests extensive information on assessment orders, under-reported earnings, outstanding taxes, and accrued interest.
The updated form consists of two segments. Section A requires fundamental taxpayer data, including their name, Permanent Account Number (PAN), residential address, mobile number, and email address. Section B addresses assessment-related particulars, encompassing the pertinent tax year, applicable section, Document Identification Number (DIN), order date, and payment deadline.
What Additional Tax Will Taxpayers Pay? The revised form outlines two rates of extra income tax payable instead of the penalty. Taxpayers who under-reported income due to misreporting under Section 439(11)(a) to (f) must pay an additional 100% of the relevant tax amount. Conversely, taxpayers covered under Section 439(11)(g) will owe 120% of the total tax.
This sum comprises tax, interest on assessed income, and the additional tax required for the waiver. Payment must be completed by the deadline stated in the notice of demand. What Information Should Taxpayers Submit? Applicants need to furnish payment details, including the bank's Basic Savings Bank Deposit (BSR) code, deposit date, challan serial number, and payment amount.
Multiple payment entries are accepted as needed. The verification section demands that applicants confirm the accuracy of the submitted information and affirm that no appeal has been lodged against the assessment order. They must also pledge not to file an appeal before the expiry of the period stipulated under Section 440(5). Filing Procedures Become More Digital-Friendly The revised form allows the use of a Digital Postal Index Number (DIGIPIN) in address details.
Additionally, the notification offers pre-filled information where feasible, potentially minimizing manual entries and streamlining the application process.
Written by urgent.news from Free Press Journal's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.