2027 Budget must make every ringgit count: Accountants group
KUALA LUMPUR: Malaysia enters 2027 Budget from a stronger fiscal position, but the next phase of consolidation will require greater focus on how revenue is raised and public funds are spent.
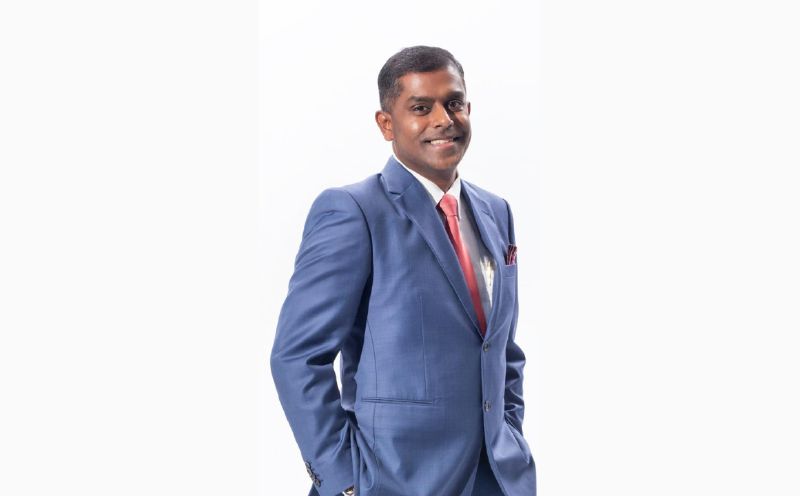
KUALA LUMPUR: Malaysia embarks on the 2027 Budget with a stronger fiscal foundation, yet the subsequent period of consolidation necessitates a heightened emphasis on revenue generation and public expenditures. According to Dr Abdul Ahad Mohd Salleh, president of the Malaysia Management Accountants Association, the fiscal deficit has decreased from 6.4% of gross domestic product (GDP) in 2021 to 3.7% in 2025.
However, the government must uphold fiscal prudence while households contend with cost pressures and businesses operate in an unpredictable global climate.
Increasing revenue is not a guarantee of success if the approach generates disproportionate costs elsewhere in the economy. Similarly, allocating larger sums does not automatically indicate a program's effectiveness. The 2027 Budget should prioritize outcome-based spending, with major initiatives explicitly connecting allocations to the issue being tackled, anticipated results, timelines, and the agencies accountable.
For instance, healthcare expenditure should be evaluated not solely by the amount allocated but also by advancements in access and waiting times, while business facilitation could be gauged through approval periods and reductions in administrative burdens.
Dr Abdul Ahad also cautioned regarding tax reform, suggesting that if the Sales and Service Tax (SST) persists, the government should scrutinize areas where tax cascading imposes unnecessary costs on businesses. Targeted credits, offsets, or business-to-business relief could be contemplated where they yield clear benefits without introducing excessive documentation, verification, or refund requirements.
He further advocated for a thorough examination of a potential SST-GST hybrid model, encompassing the implications for diverse sectors. One possibility might involve retaining SST for services while contemplating GST for manufacturing, enabling businesses to potentially recover input tax, thereby potentially benefiting consumers through lower selling prices.
In relation to e-Invoicing, Dr Abdul Ahad emphasized that the system should yield advantages beyond enforcement. With businesses earning less than RM3 million annually exempted, the government should leverage the structured data generated by e-Invoicing to streamline duplicate reporting, expedite legitimate verification, and enhance enforcement through a risk-based approach. Digitalization should ultimately result in better information for the government and less superfluous administration for compliant businesses.
Dr Abdul Ahad further contended that competitiveness should be evaluated beyond tax incentives, with businesses placing significance on policy predictability, approval periods, compliance costs, and ease of operating post-investment. The 2027 Budget could accordingly bolster competitiveness through clearer implementation timelines, reduced overlaps between agencies, and enhanced certainty regarding major policy modifications, alongside targeted incentives.
Household assistance should likewise become more targeted, as income alone does not entirely capture financial strain. Households with similar incomes can face vastly different costs contingent on housing, dependents, childcare, healthcare, and caregiving responsibilities. With improved data, assistance could be allocated according to where pressure is concentrated and which intervention is most suitable, rather than defaulting to broad-based support.
Dr Abdul Ahad also urged for greater medium-term visibility on tax reforms, spending priorities, and implementation schedules over the next three to five years. Although Malaysia presently possesses medium-term fiscal planning, clearer forward guidance would furnish businesses and households with greater certainty. The 2027 Budget will primarily be judged by its announcements; the more critical test lies in the outcomes these measures achieve.
Malaysia has made strides in restoring fiscal discipline. The ensuing stage should concentrate on enhancing the fiscal system, linking spending to outcomes, decreasing tax and administrative friction, precisely targeting support, and providing businesses and households with greater certainty about what lies ahead.
Rewritten by urgent.news; may contain errors — check the original.