Broker’s call: TajGVK Hotels (Buy)
Monarch Capital
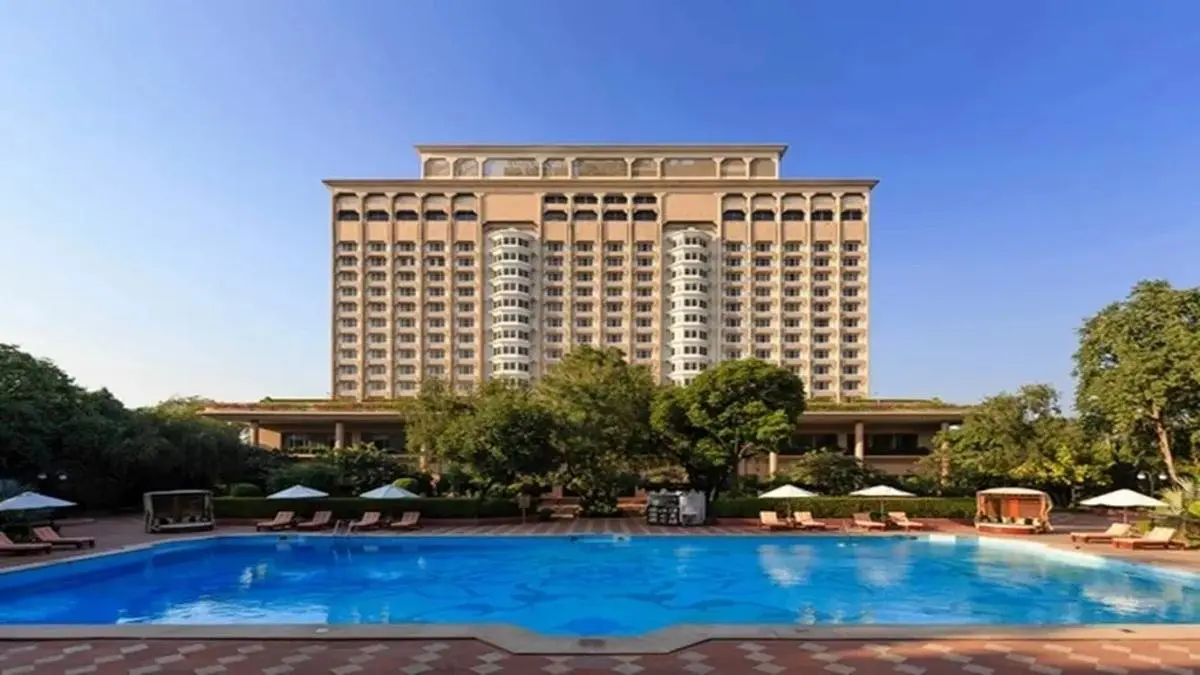
The brokerage firm has initiated coverage on TajGVK Hotels & Resorts, now known as Krishna GVK, with a BUY rating and a target price of ₹475 per share. The firm sees the company entering a phase of stronger growth, driven by its mix of premium hotel assets, Taj's operating expertise, and an expansion cycle. After years of modest asset additions, Krishna GVK is now embarking on a more aggressive growth phase, with a new hotel in Bengaluru slated for the second half of fiscal year 2027 and consolidation of Taj Santacruz in Mumbai.
The company also has a pipeline of organic and inorganic opportunities on the horizon. In the meantime, the strong occupancy rates across its current portfolio, especially in Hyderabad, offer a stable foundation for revenue growth driven by increasing room rates and premiumization through renovations. The brokerage expects revenue and EBITDA to expand at roughly 26.4% and 26.6% compound annual growth rates, respectively, over FY26-FY29E.
This suggests that the current valuation may be undervaluing the potential earnings boost from the company's forthcoming expansion. However, key risks include a heavy dependence on the Hyderabad market, potential slowdowns in travel and tourism, a possible cyclical downturn in the hospitality sector, a promoter share pledge, and the company's reliance on the Taj brand's reputation.
Written by urgent.news from Hindu BusinessLine's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.