Disputed amount under protest not admission of guilt: LHC
ISLAMABAD: The Lahore High Court (LHC) has ruled that payment of a disputed amount under protest cannot, by itself, be treated as an admission of guilt before the Federal Board of Revenue (FBR). It dismissed the Department’s Sales Tax Reference and confirmed the order passed by the Federal Tax Ombudsman (FTO) in favour of the taxpayer. Tax lawyer Waheed Shahzad Butt, who had represented the…
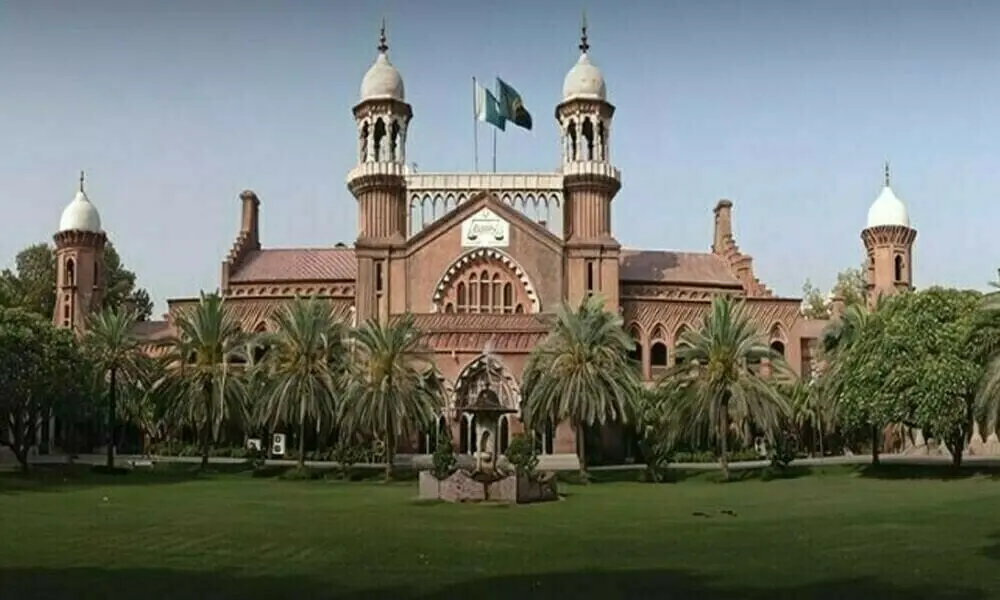
The Lahore High Court (LHC) has ruled that paying a disputed amount under protest does not equate to admitting guilt in the eyes of the Federal Board of Revenue (FBR). The court dismissed the Department's Sales Tax Reference and upheld the order made by the Federal Tax Ombudsman (FTO) in favor of the taxpayer. Waheed Shahzad Butt, the taxpayer's tax lawyer, explained that the LHC's divisional bench made both rulings in a single judgment.
The case stemmed from an FBR's Directorate General of Intelligence and Investigation investigation into a possible scam involving misuse of registration numbers of registered persons. The taxpayer was summoned under Section 37 and made a payment under protest. An Order-in-Original then requested the same amount, plus a 100 percent penalty and default surcharge.
The commissioner (Appeals) and the appellate tribunal inland revenue (ATIR) removed the penalty and surcharge. The FTO suggested a refund of the deposited amount under protest and the annulment of the order.
The court held that the payment under protest "cannot, by itself, be treated as an admission of guilt." It also stated that such a payment cannot be considered a confession or admission of the elements of an offence without supporting evidence. A taxpayer can pay to prevent coercive consequences while retaining the right to challenge liability.
Paying does not equate to confessing to a penal offence. The department must prove the elements of the offence independently. No evidence indicated that the taxpayer knowingly or fraudulently took part in the alleged scheme.
The court noted that liability cannot be imposed based on assumptions, and that output tax is the supplier's responsibility. The default surcharge under Section 34 is mandatory and does not require intent (mens rea). However, the department could not prove the underlying statutory default or the computation, so the surcharge could not be upheld. The LHC ordered this decision. Waheed Butt also emphasized that the FTO's order to refund the amount paid under protest was a significant victory.
Written by urgent.news from Business Recorder's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.