The Term Spread As Recession Predictor, Post-2024
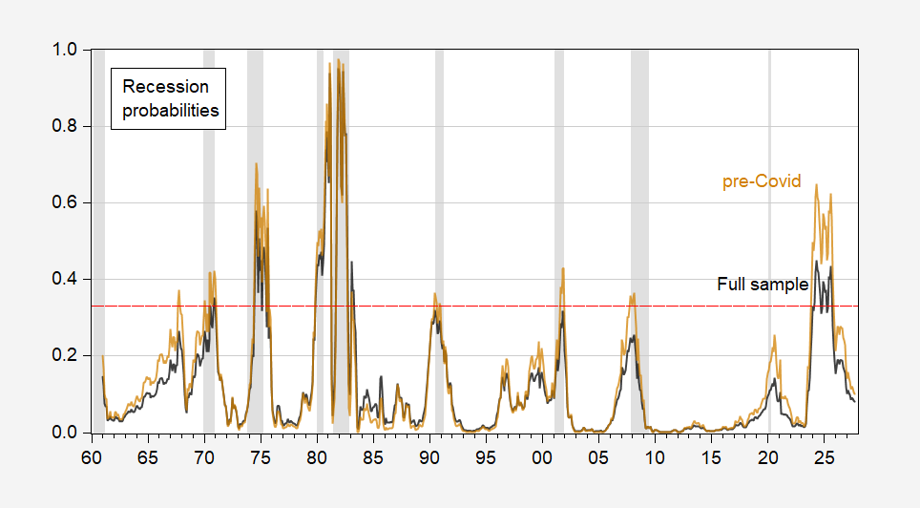
Using a plain vanilla term spread model (spread, short rate), what remains? From notes for tomorrow’s lecture. Figure 1: Estimated recession probabilities from probit on 10yr-3mo term spread, short rate over 1960-2018 (brown), over full sample (black). Red dashed line at 33%. NBER defined peak-to-trough recession dates shaded gray. Source: author’s calculations, NBER. Using a […]
We haven't written up this one. Econbrowser has the full story — the link below goes straight to it.