India needs to shift more household savings to long-term pension assets: CEA Nageswaran
India needs to encourage households to commit a larger share of their savings to long-term pension products as pension and insurance assets remain a relatively small part of household savings, Chief Economic Adviser V Anantha Nageswaran said, calling for simpler pension products, wider access and stronger retirement-income solutions.
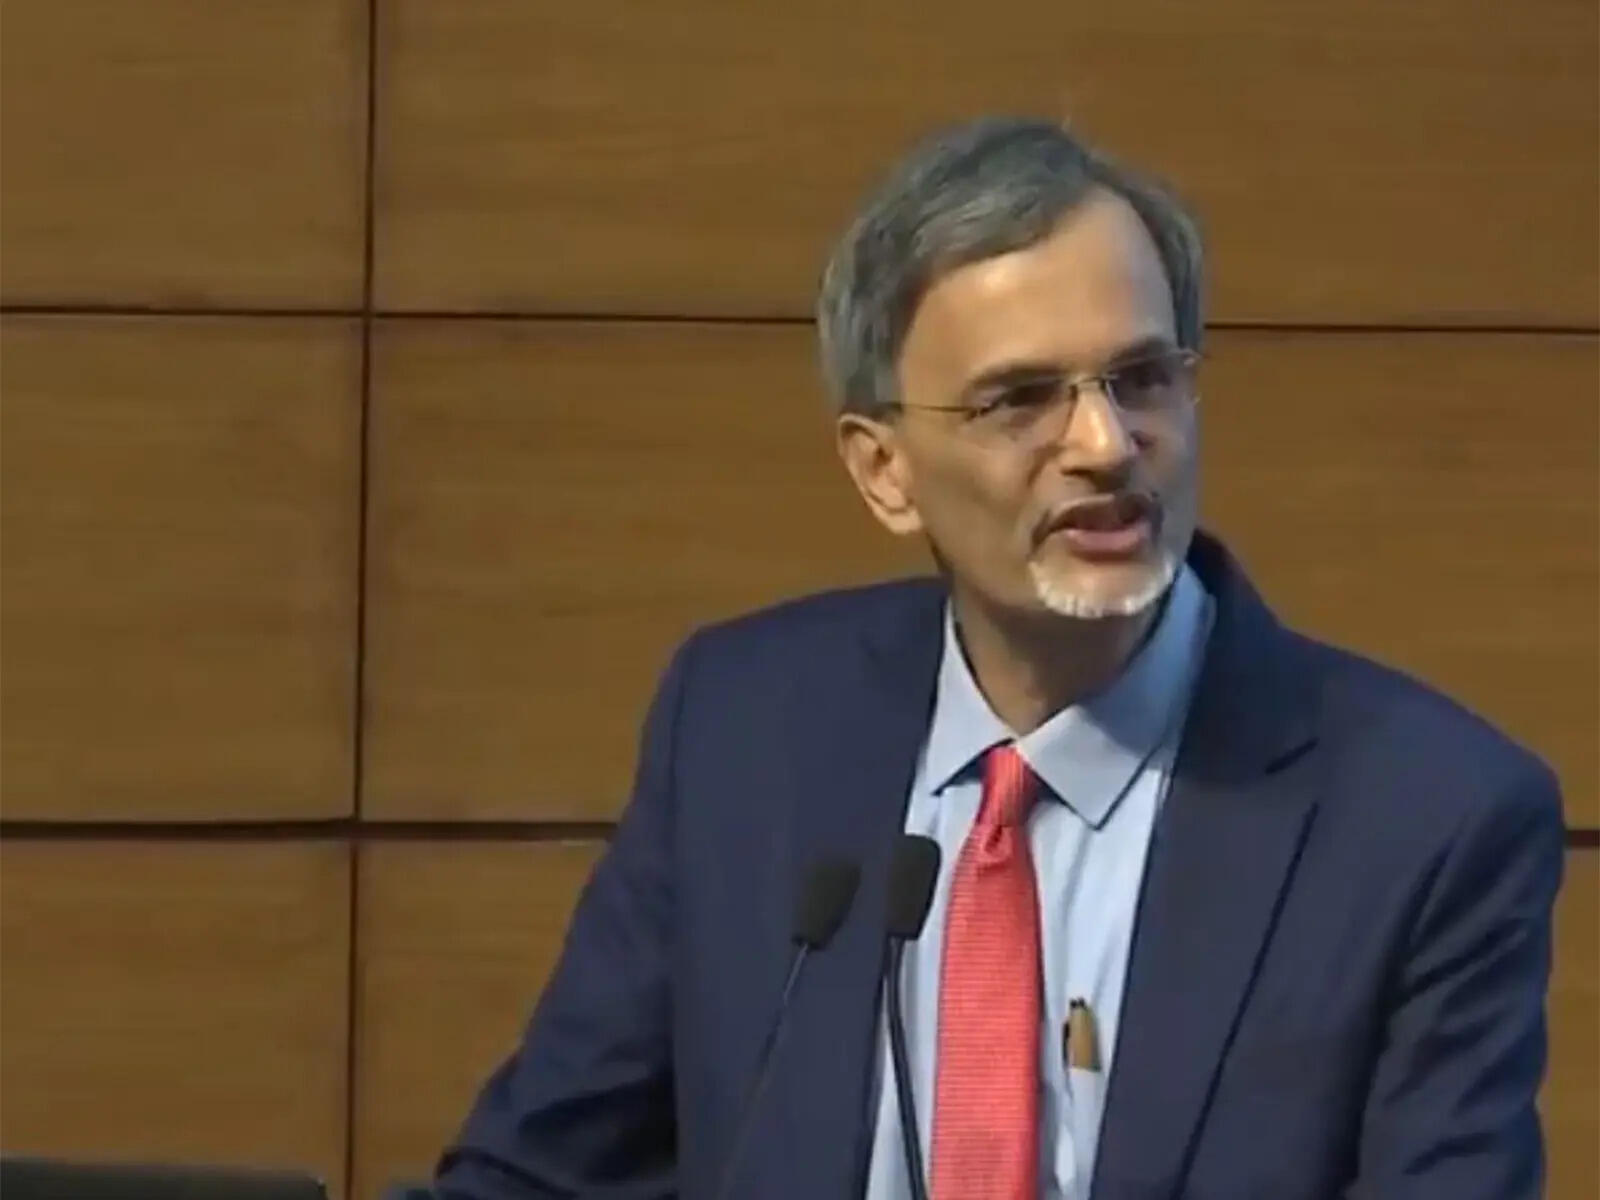
New Delhi: India must encourage households to allocate a greater portion of their savings towards long-term pension products, according to Chief Economic Adviser V Anantha Nageswaran. Addressing pension and insurance assets, which remain a small fraction of household savings, Nageswaran emphasized the need for simpler pension products, wider access, and stronger retirement-income solutions.
During an event marking NPS Diwas 2025-26, Nageswaran noted that while Indian households have increasingly turned to market-linked investments, pension savings have not grown at the same rate. He mentioned that while the Indian saver is willing to accept market risk, they have not yet committed savings for a longer tenure—a different decision since Indians generally do not prioritize long-term optimization.
Drawing on data from the Economic Survey, Nageswaran highlighted that the share of equity and mutual funds in annual household savings has risen from about 2% in 2011-12 to around 15% in 2024-25, while bank deposits have fallen from over 58% to about 35%. However, the share of pension and insurance assets in household savings has remained unchanged between 2018-19 and 2023-24.
Nageswaran cited India's total pension assets at about 17% of GDP, which is considerably lower than the 80% in OECD peer countries, signaling a significant opportunity for expansion. He suggested that technology and simpler products could address the coverage gap, drawing a parallel to the success of UPI in financial inclusion. Nageswaran pointed to features such as default schemes, small contributions via phone, and local agents as ways to enhance access.
Initiatives like Tatkal NPS and Pension Sakhis are moving in that direction. Lastly, Nageswaran stressed that building the pension corpus is only part of the solution; the system must also ensure reliable income during retirement, converting the corpus into a steady income that lasts for as long as the individual lives and keeps pace with inflation.
Written by urgent.news from The Economic Times - Economy's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.