HI Mobility 2H FY27 earnings to gain traction on bus deliveries, ridership
KUALA LUMPUR: HI Mobility Bhd's earnings are expected to remain firm in the second half of financial year 2027 (2H FY27), driven by higher commercial vehicle deliveries and stronger cross-border bus ridership during the holiday season.
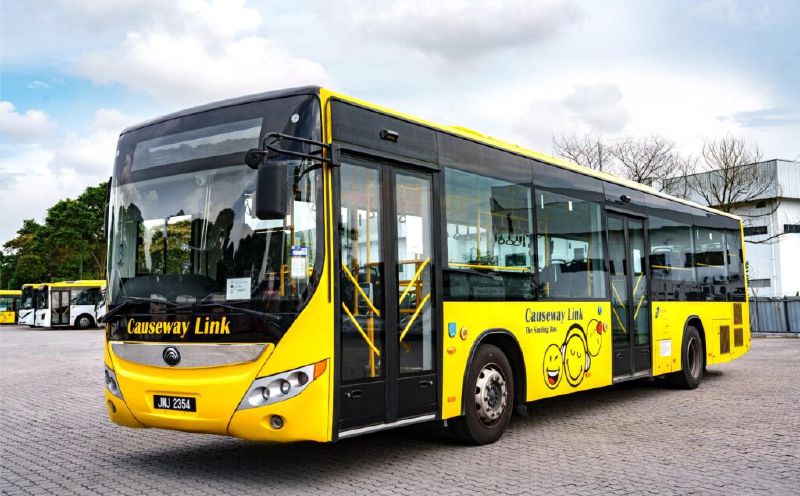
KUALA LUMPUR: Financial analysts predict HI Mobility Bhd's earnings for the second half of fiscal year 2027 (2H FY27) will benefit from increased commercial vehicle sales and growing cross-border bus ridership during the holiday season. According to CIMB Securities Sdn Bhd, the company is set to deliver 250 electric buses over the next nine months as part of a national operator's fleet modernization initiative to promote electric vehicle adoption amid rising fuel costs.
As of July 31, HI Mobility had an unbilled order book worth RM211 million, providing a clear picture of future earnings.
The firm anticipates that HI Mobility's earnings will remain robust due to stronger cross-border ridership during the Malaysian and Singaporean holidays, combined with higher bus deliveries. This outlook comes after a solid second quarter, where the company's core net profit grew 8.7% quarter-on-quarter to RM19 million, and revenue increased 7% to RM119.3 million.
This growth was primarily fueled by an 8.3% rise in scheduled bus services revenue, as cross-border passengers rose 17.7% to six million during the quarter. The increase was driven by contra-lane services that alleviated congestion along the Causeway and boosted bus trip frequency.
HI Mobility also announced an interim dividend of one sen per share, boosting its first-half dividend to two sen. For the first half of 2027, revenue surged 50.9% year-on-year to RM231 million, reflecting the integration of commercial vehicle manufacturing, assembly, and distribution businesses following the April 8 Acacia and Handal BCM acquisitions.
These acquisitions accounted for 28.1% of group revenue during the period. Scheduled bus services revenue grew 6.5%, supported by new intra-city contracts under the BAS Muafakat Johor program.
CIMB Securities maintains a Buy rating and a RM2.80 target price on HI Mobility. The stock closed at RM1.86 on the year, down 32.12% from its opening price of RM2.74. The year-to-date decline is partly attributed to delays in awarding the Johor-Singapore Rapid Transit System (RTS) Link dispersal bus contract. However, the firm did not factor in any contribution from this contract in its earnings forecasts.
CIMB Securities believes HI Mobility's strong track record in Johor and its existing presence under BAS Muafakat Johor will strengthen its position for the expanded Stage Bus Service Transformation (SBST) program. The upcoming SBST contract renewal could lead to a significant increase in both contract value and fleet size. Currently, HI Mobility holds a five-year RM282.5 million contract to operate Johor Bahru's SBST network from March 2022 to March 2027.
Written by urgent.news from New Straits Times's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.