Business Cycle Indicators: Real GDP, Personal Income Trajectory Revised Up
Q2 GDP growth revised up 0.7 ppts, path of personal income ex-transfers up due to revised deflator. Here are the key indicators followed by the NBER’s Business Cycle Dating Committee: Figure 1: NFP employment (bold blue), civilian employment with smoothed population controls (bold orange), industrial production (red), personal income excluding current transfers in Ch.2017$ (bold light […]
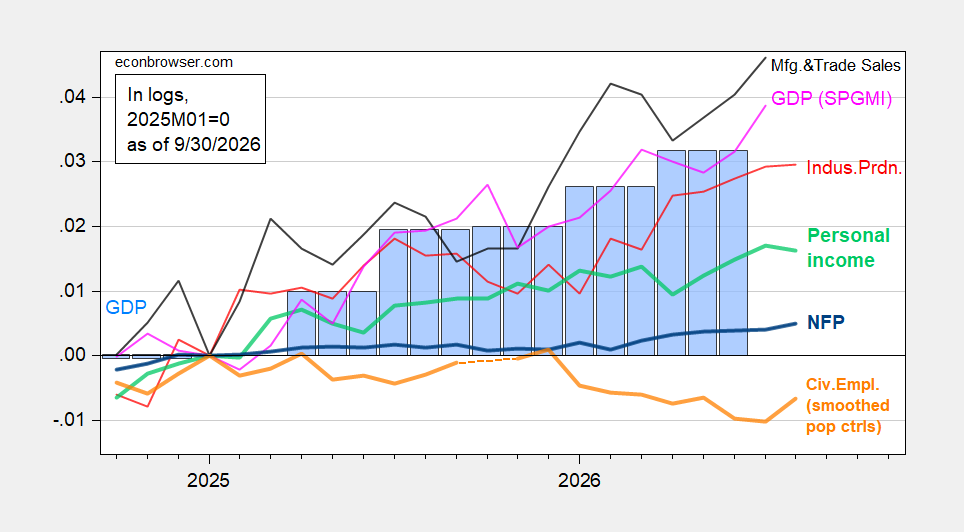
The latest revision to business cycle indicators reveals an upward adjustment to real GDP growth and a surge in personal income excluding current transfers. According to the NBER's Business Cycle Dating Committee, the GDP growth rate for Q2 was revised upward by 0.7 percentage points. This revised trajectory indicates a stronger economic performance than initially estimated.
Key indicators further support the argument for robust output growth. Civilian employment, adjusted for NFP concept and smoothed population controls, continues to rise. Manufacturing production, ADP private nonfarm payroll employment, real retail sales (CPI deflated), freight services indexes, and the coincident index are all showing positive trends when normalized to 2025M01=0.
The rise in consumption is particularly noteworthy. In August, consumption grew at an annualized rate of 6.6%, as preliminary figures suggest. This growth figure, though preliminary, bolsters the view that consumer sentiment, despite being currently low, does not accurately reflect the actual level of consumption.
Written by urgent.news from Econbrowser's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.