Broker’s Call: Elecon Engineering (Buy)
Axis Securities
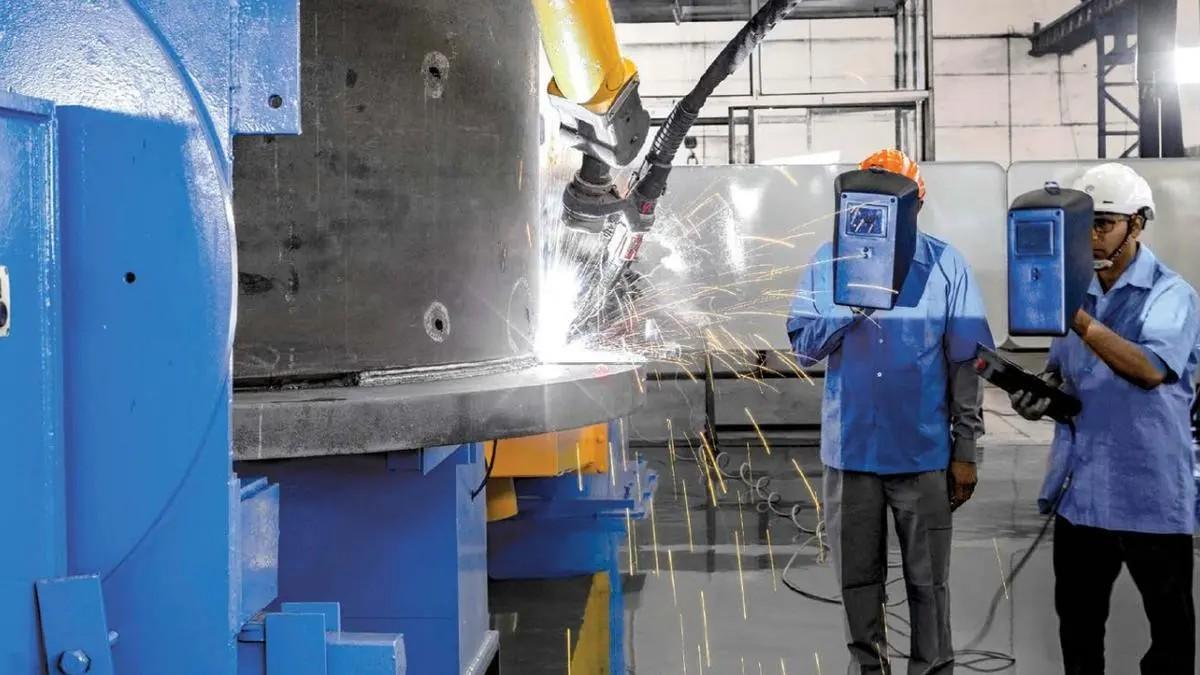
Elecon Engineering's consolidated order book reached a record ₹1,518 crore, with quarterly order inflows of ₹755 crore, marking a 23% increase year-over-year. Strong backlog exists in both Gear and MHE divisions, ensuring sustained execution. Significant export orders secured at the end of Q1FY27 are projected to boost revenue recognition from Q2FY27 onwards.
International sales outpaced domestic ones, growing 21.9% to ₹151 crore, accounting for 29% of the company's total revenue, up from 25% a year ago. This overseas growth was fueled by operational recovery in European subsidiaries and steady global demand. Recent international deals, such as a ₹21-crore port equipment order, emphasize Elecon's expanding presence in global industrial markets.
Despite short-term challenges, the company's robust order backlog and consistent order inflows signal promising medium-term earnings potential. Management anticipates significant improvements in project execution starting Q2FY27, with export revenue expected to grow further. The company's valuation is set at 22x FY28E EPS, with a recommendation to Buy at a target price of ₹505 per share.
Written by urgent.news from Hindu BusinessLine's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.