MONEY THOUGHTS: The person, the pool and the pipeline
IN my small professional practice, which provides holistic financial planning advice and services to a wide cross-section of English-speaking adults, different goals motivate people to reach out to me.
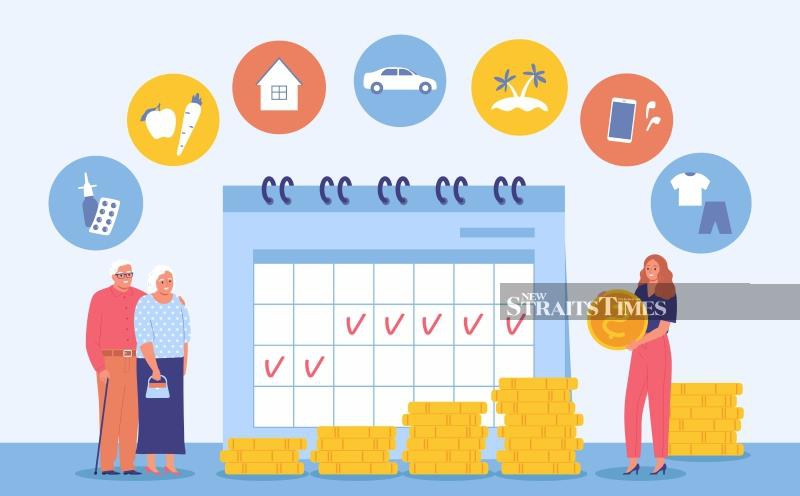
The story revolves around four primary goals that motivate individuals to seek financial advice: ensuring their children receive top-tier tertiary education, eliminating debt, saving for a robust retirement, and establishing legacy gifts for the next generation. These goals hinge on an active person increasing their income through work or business while being cautious not to spend all their earnings.
The difference between income and expenses can result in a surplus or deficit, and when these surpluses accumulate, they form a pool of capital for the individual.
Upon reaching the end of life, the leftover capital can be utilized for passing on gifts to children, grandchildren, religious organizations, or charities, as no one can take their wealth with them when they pass away. The critical aspect to remember is that a significant source of retirement stress stems from a dwindling pool of capital due to inflation and regular withdrawals for living expenses.
A proactive approach to addressing this issue is to work beyond the traditional retirement age, thereby shortening the overall retirement period.
To support this proactive strategy, the author provides an analysis of Malaysia's population. With a population of 34.4 million, this includes 31 million citizens and 3.4 million non-citizens. Of the 17 million working adults, approximately 1.7 million are government employees, many of whom will receive a government pension upon retirement.
Additionally, around 1 million non-working individuals receive some form of civil service pension. Consequently, a considerable portion of the workforce—around 15.3 million members—will not receive a government pension upon retirement.
For these growing numbers of individuals lacking public pensions, the author suggests two primary options: either create their own retirement funds or continue supporting non-earning family members. The recommended approach is to build capital pools and convert them into passive income streams, such as interest from savings, dividends from EPF and stocks, distributions from income-focused unit trusts, and rental income from real estate.
By establishing these passive income sources, individuals can ensure a more prosperous and less stressful retirement period.
Written by urgent.news from New Straits Times's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.