Broker’s call: SPR Auto (Buy)
Motilal Oswal Financial
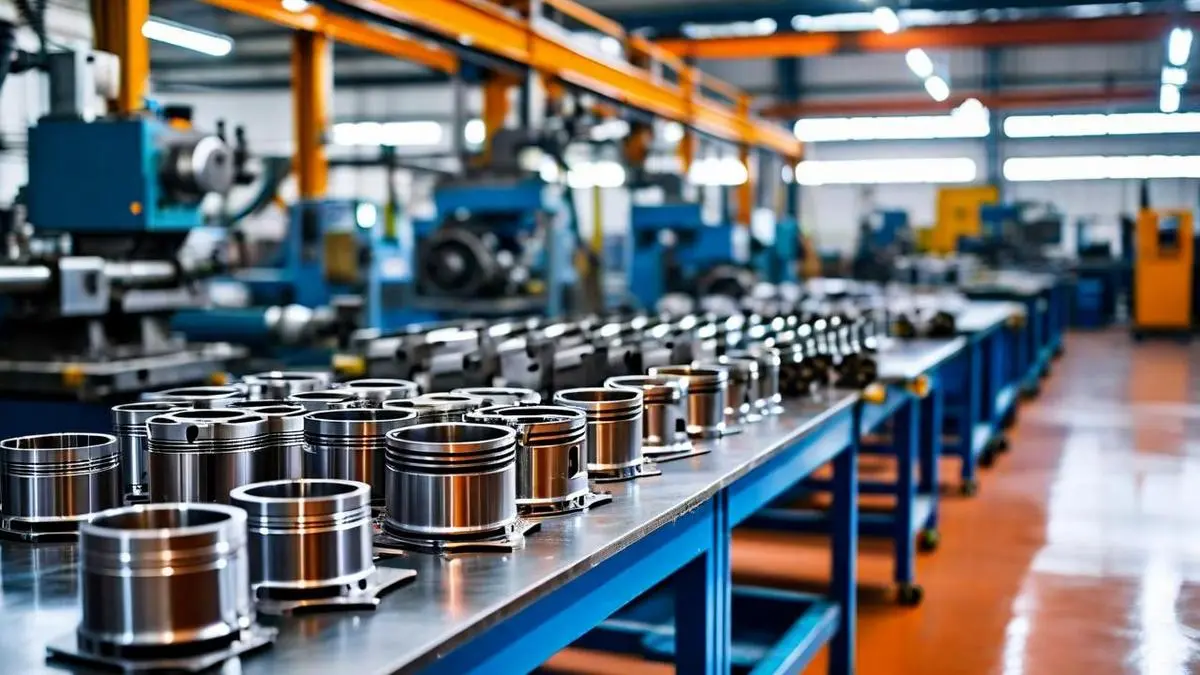
SPR Auto Technologies (SPR) is transitioning from a traditional piston manufacturer to a diversified, technology-driven mobility platform through strategic acquisitions. The piston business provides a strong cash-cow for SPR, boasting market leadership, significantly higher margins, and a core return on capital employed of over 50%.
SPR benefits from growing multi-fuel opportunities, which include CNG, ethanol, hydrogen, and hybrids, as well as strong aftermarket demand and the premature exit of global competitors from the internal combustion engine (ICE) ecosystem.
Leveraging its robust balance sheet and cash flow profile, SPR is reinvesting in acquisitions such as Antolin, Takahata, TGPEL, and EMFi, thereby expanding beyond powertrain-focused products to precision plastic molding components. This strategy aims to create a scalable auto component platform with balanced exposure across powertrains, potentially increasing estimated content per vehicle by over six times to more than ₹30,000.
To support its future organic and inorganic growth opportunities, SPR recently completed an INR10 billion qualified institutional placement (QIP), which could serve as a key catalyst for further upside.
The report initiates coverage of SPR with a Buy rating and a target price of ₹6,150, based on 30 times the September 2028 earnings per share (EPS). Key risks identified for SPR include increased competitive intensity, fluctuations in commodity prices, changes in technology, and potential loss of key customers.
Written by urgent.news from Hindu BusinessLine's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.