StubHub earns Moody’s upgrade to B2 as debt reduction efforts bear fruit
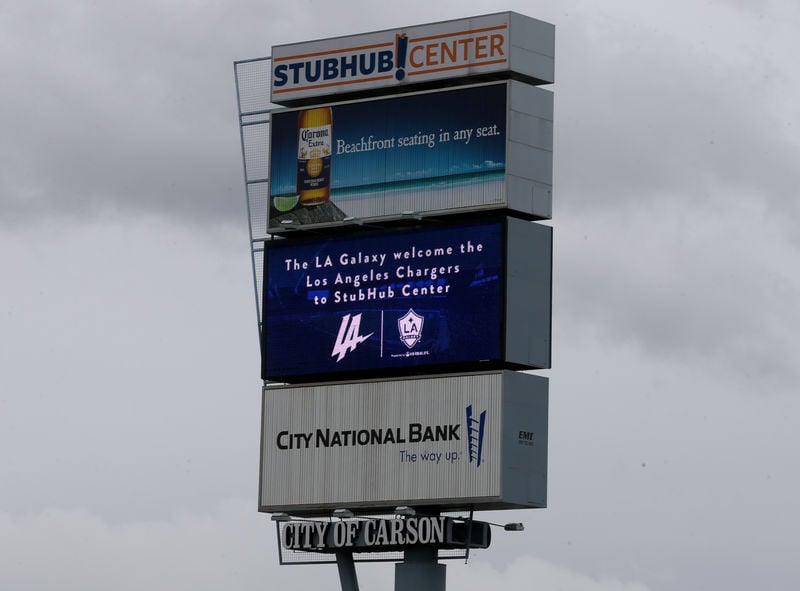
Moody's Ratings has upgraded StubHub Inc's Corporate Family Rating to B2 from B3, indicating confidence in the live-event ticketing marketplace's ongoing balance-sheet deleveraging. The agency also raised the company's Probability of Default Rating and senior secured bank credit facility ratings to B2 while maintaining a stable outlook.
This upgrade comes after StubHub experienced significant improvements in credit metrics, following heavy marketing expenses and one-time costs that compressed core profitability in 2024 and 2025. Although StubHub's leverage stood at 8.5x at the end of Q2, the agency projects it will fall to 5.7x by the end of 2026. This projection is driven by steady sales growth and margin expansion.
StubHub's market position as a premier secondary ticketing destination remains a cornerstone of its credit profile, providing operational flexibility amidst intense competition and promotional pressures. The company's strong internal cash generation and a $565 million senior secured revolving credit facility maturing in 2030 further bolster its liquidity position.
Moody's anticipates the business to generate $280 million to $300 million in annual free cash flow, freeing it from reliance on revolver borrowings before its 2030 term loan maturities. While the stable outlook suggests StubHub will maintain leverage below the 6x threshold and solid profitability, the agency cautioned that regulatory headwinds or market share loss could lead to future downgrades.
Further upgrades would require StubHub to maintain debt-to-EBITDA below 5x and adhere to a conservative financial policy.
Written by urgent.news from Investing.com's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.