General Mills beat earnings expectations but its stock slipped anyway
The cereal and snacks maker topped sales and profit estimates but reaffirmed a cautious full-year outlook as higher input costs squeezed margins
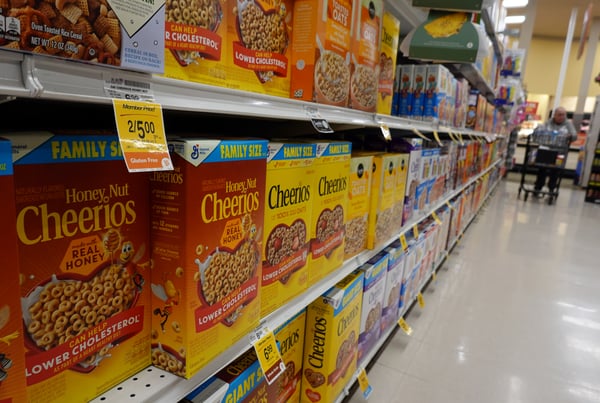
General Mills (GIS) reported stronger-than-expected earnings for Q1 FY2027, with adjusted EPS at $0.75 versus the estimated $0.72. The company's revenue also exceeded forecasts at $4.40B compared to the estimated $4.34B. Despite this positive performance, the stock is trading at $35.18, down 0.76% as of Sep 23, 12:37 PM EDT, indicating that investors are seeking more growth beyond respectable results.
Management reaffirmed its full-year FY2027 guidance, projecting organic net sales growth between -1.5% and +0.5%, adjusted operating profit declines between 8% and 13% in constant currency, and adjusted diluted EPS between $3.00 and $3.20. This reaffirms management's confidence heading into the year's tougher comparisons. The company remains committed to achieving $750M in cost savings for FY2027 as part of a larger $3B cumulative savings target by FY2030.
Management cited improving momentum in cereal, Pillsbury, and pet food cat segments as well as a shift in North America Retail base pound volume from down 10% to up 2% over the past year. However, Q4 FY2026's standout performance (17.3% EPS surprise, stock +7.96%) is significantly outpaced by this modest beat. Q1 FY2027's beat is far more modest, with organic net sales remaining flat, and volume recovery timeline remains the central issue.
North America Retail consumption saw a decline of 2% on a takeaway basis. UBS, maintaining a Sell with a $33 PT, suggests that a return to growth still seems unlikely at this stage. Challenges persist with Totino's and Blue Buffalo Wilderness, as execution issues and category pressure continue to weigh on the portfolio's overall narrative.
Inflation risks are also present, as costs are running toward the high end of the 4%–5% COGS inflation range, potentially squeezing the margin tailwind that helped Q4 FY2026 shine. The current consensus among analysts is favorable, with a mean PT price of $37.67, representing a 7% upside from the current stock price of $35.18. EPS revisions have been negative over the past 90 days (-9.7%), though the 30-day revision was slightly positive (+0.4%), indicating stabilization after the Q4 beat.
The stock is trading near its 52-week low zone ($31.75–$51.33 range) and offers a 6.9% dividend yield, making it an attractive option for income investors willing to wait for volume recovery. The central question remains whether this represents a patient value setup or a declining investment story.
Written by urgent.news from Investing.com's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.
This story
This is one outlet's version. Read the fullest account.