Does your parents’ financial advice still work?
Here's some financial advice that needs reworking.
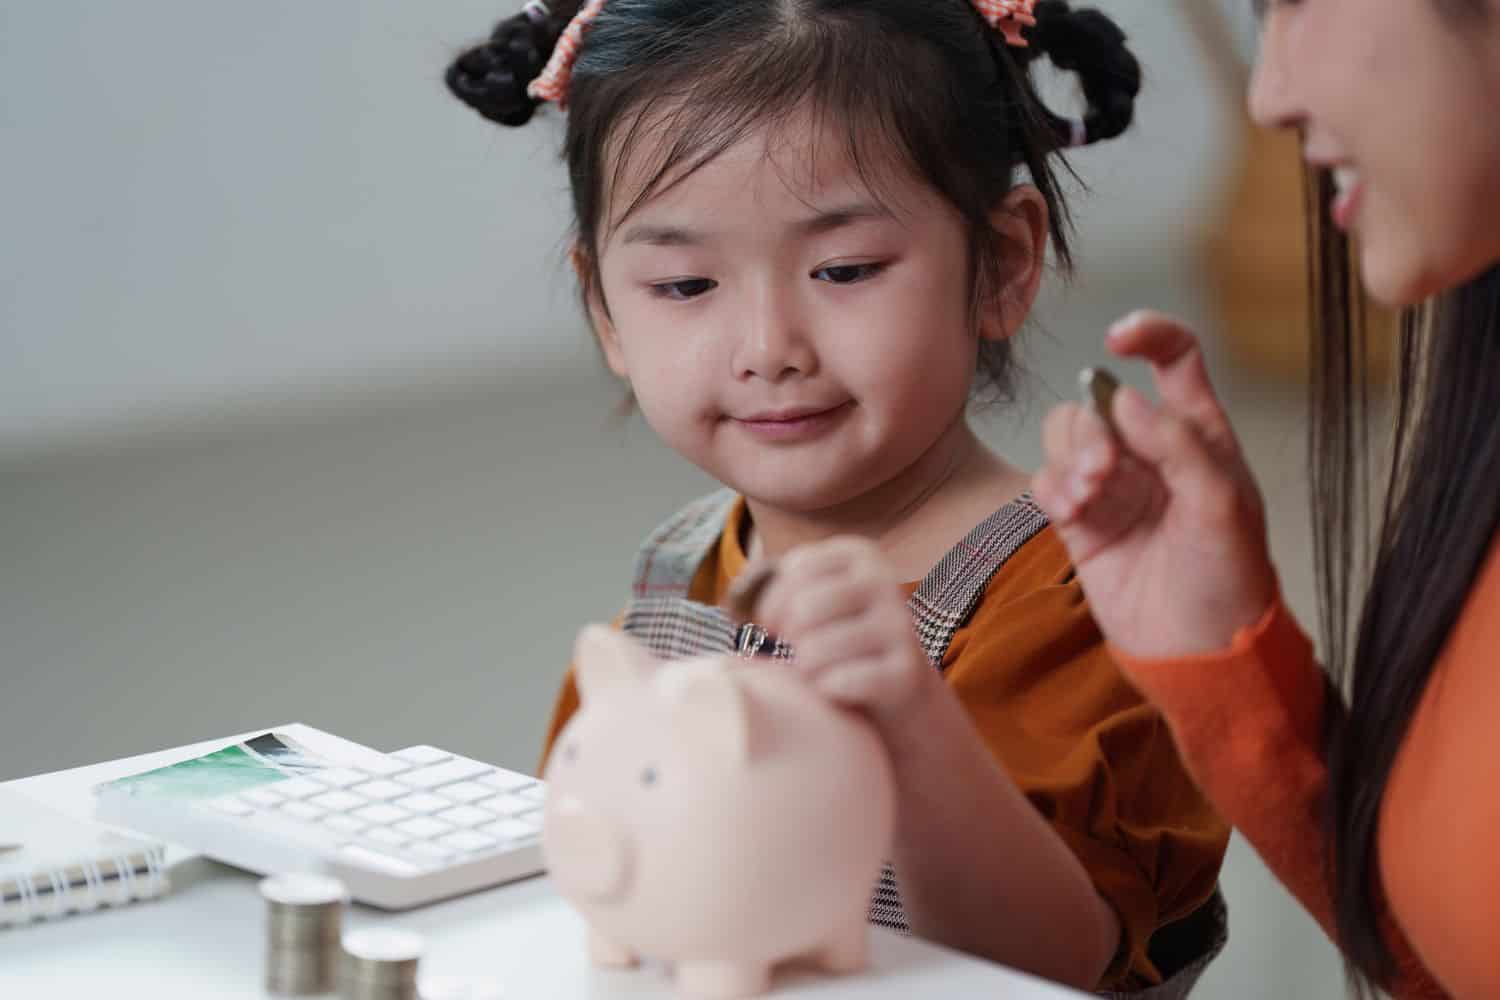
Old financial wisdom provided by parents may not be as applicable in today's world. Lee Hancox, head of channel and segment marketing at Sanlam, acknowledges that while some advice remains relevant, modern circumstances necessitate adjustments. Traditional paths, like staying with one company for decades, are less common, and property prices have become less affordable.
The advice "Avoid debt at all costs" has evolved into understanding the distinction between beneficial debt and detrimental debt. Hancox advises that debt should not be used to fund a lifestyle beyond one's means or to incur high-interest payments, but responsible debt, such as for education or property, can contribute to long-term wealth.
"Save every cent" is now complemented by the need to invest money, as opposed to merely saving. Inflation can diminish the value of cash savings over time, making investing essential for young people. Establishing an emergency fund is crucial for financial stability, regardless of income stability.
The idea of "Get one good job and stay there" has shifted towards embracing multiple income streams and career adaptability. Building diverse skills and creating multiple income sources is now the norm. However, irregular income requires disciplined financial habits, like saving and investing consistently, paying oneself first, and planning for taxes.
To update financial advice, Hancox suggests starting with a self-audit of money habits, followed by open discussions about finances with family members.
Written by urgent.news from The Citizen's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.