Indian rupee slips on-week, traders reckon 'line in sand' near 96/USD will hold
MUMBAI: The Indian rupee logged a weekly decline on Friday, hurt by expectations of higher global interest rates, while traders kept an eye on oil prices and said that central bank intervention would limit the currency’s downside around 96 per dollar. The Indian rupee ended at 95.8750 per dollar, up modestly on the day but logged a 0.3% week-on-week fall. The US Federal Reserve and the Bank of…
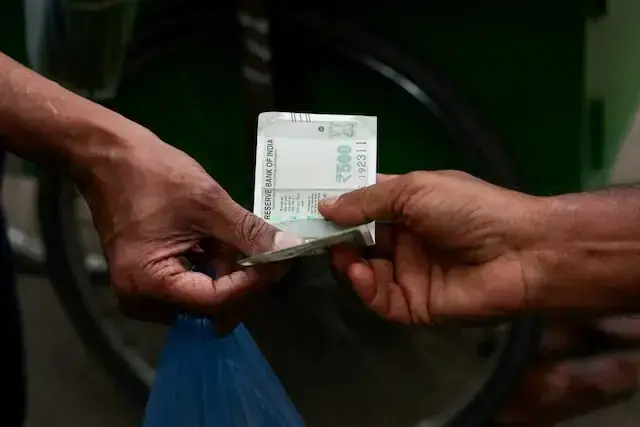
The Indian rupee experienced a weekly decline on Friday, with traders anticipating that the currency would remain near the 96/USD line, which they consider a critical support level. The rupee ended the week at 95.8750 per dollar, marking a 0.3% decrease on a week-on-week basis. This decline was attributed to expectations of higher global interest rates, particularly after the US Federal Reserve and the Bank of Japan raised interest rates this week.
The prospect of higher borrowing costs negatively impacted risk assets, including emerging market currencies and equities. Oil prices also rose to near four-month highs earlier in the week, but have since cooled following reports that Saudi Arabia was working to restore part of its East-West oil pipeline capacity. DBS noted that the next key question for investors is whether the Fed's policy stance will prompt a similar response from Asia, with India and the Philippines expected to raise rates in the coming quarter.
The Reserve Bank of India has been actively defending the 96/USD level, acting as a "line in the sand" for the currency for the time being.
Brief written by urgent.news from Business Recorder's own syndicated text. Machine-written — may contain errors; check the original before relying on it.