Digital Bank: Battle Cry from Revolut Chief: "We Want to Be Number One in Germany"
Nik Storonsky talks to Handelsblatt in an interview about Revolut's upcoming offensive in the Federal Republic, the fight for customer trust and plans for a mega IPO.
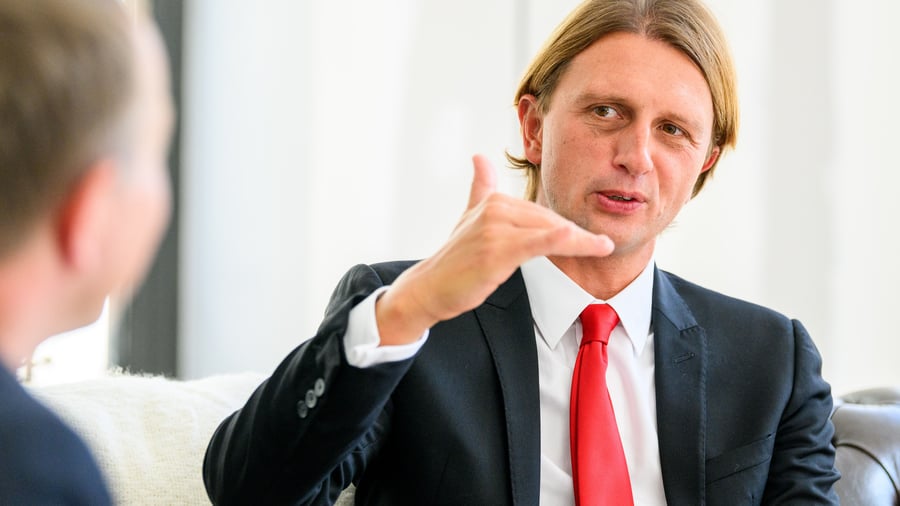
Revolut CEO Nik Storonsky received the Handelsblatt reporters at a construction site. Pipes and cables dangled from the ceiling, an assembly scaffold stood in the hallway, and the floor was covered in protective plates. The new European headquarters in Paris is yet to be ready for its grand opening in 2027. The office is situated between the stock exchange district, the historic center of French finance, and the Sentier district, home to many tech companies and startups.
This location is not just a statement but also a testament to the global expansion ambitions of Europe's most valuable fintech. Storonsky sits in a black suit with a red tie on the second floor, surprising those who meet him with his relaxed handshake, soft voice, and almost shy demeanor. However, during the conversation, it quickly became clear that the 42-year-old does not lack self-confidence.
In Germany, Storonsky has ambitious plans. Read the full interview with Nik Storonsky. Storonsky, you started Revolut in 2015 as a travel payment app. Today, the bank has 80 million customers and is the most valuable European fintech. What is your secret to success? It's similar to humanity's goal of building a city on Mars. It doesn't happen overnight, but it requires many small steps.
We have introduced many new products over the years, obtained more licenses, and entered more markets. There hasn't been one big breakthrough. Revolut started in Britain, where it now has 14 million customers, followed by France with eight million and Spain with six million customers. In Germany, you are relatively small with about three million customers.
What's the reason? In comparison to other Western European markets, Germany has the highest cash usage. People therefore use digital banks less. Additionally, German customers value German IBANs highly. We only offered these account numbers in early 2024 after opening a German branch. How do you plan to catch up in Germany? We have been working for years to tailor our offer more to the German market.
We have also simplified the account opening process. Initially, our customers had to undergo video identification with a staff member, which was not fully digital and could take up to seven hours. This was not a great user experience. We have since accelerated the process. We are currently advertising a promotion – 4.25 percent on savings for four months – to attract German customers.
Is this the beginning of a big offensive in Germany? Yes. We are still relatively small in the German market and want to change that in the coming years. Therefore, we are offering new savings and investment products. We are also investing heavily in marketing, both digital campaigns and traditional advertising. Since this year, we have sponsored Formula 1 team Audi.
We aim to be the market leader in each of the ten European core markets by 2028. In Germany, Revolut is currently far behind the savings banks, which hold around 38 million private current accounts. Is it realistic to become the market leader in Germany? We want to be the number one in Germany as soon as possible. We have been weaker than some competitors in the Federal Republic for a long time.
In this quarter, our app downloads have placed us for the first time in first place, ahead of the savings banks. Our growth in Germany is just beginning to attract attention. Perspectively, we want Germany to be our largest market in Europe. Why were you weaker than other competitors in the EU, especially in Germany, where experts attribute this to Revolut only having a license from Lithuania, which was systemically regulated by the European Central Bank (ECB)?
We should have explained this better. We were always double-regulated: by the Central Bank of Lithuania and the European Central Bank (ECB). Many overlooked this, including in the press. Since we were classified as systemically important, we have been supervised by the ECB since 2019, a top regulator. Consequently, it should not matter where the regulated bank is headquartered.
For many people, it apparently made a difference, especially in Germany. Revolut recently also obtained a banking license in France. With today's knowledge, would you have tried earlier to obtain a license in a large EU country? With today's knowledge, perhaps. But you must remember that we only had 100 employees and limited capital, management capacity, and few experienced bank managers in 2019.
Obtaining a license in Lithuania was logical because we could achieve the same result with fewer resources. Analysts point out that customers in the UK have less deposit money with you than with the big British banks because they do not trust Revolut as much. Is the lack of trust still a problem for Revolut in Germany? In many countries, we are the bank for about 20 percent of our active users.
This is less than established banks that have often been around for over 150 years and have built up a lot of trust over this time. We, on the other hand, are newcomers. But it's only a matter of time until customers trust us as much as established banks. What makes you so confident about this? In Ireland, where we grew quickly and early, 80 percent of our customers already use Revolut.
Written by urgent.news from Handelsblatt's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.