Your ML Model Doesn’t Compete With the Market. It Competes With Other Models
In financial markets, being right isn’t enough. Learn why ML models lose their edge when competitors discover and trade on the same signals.
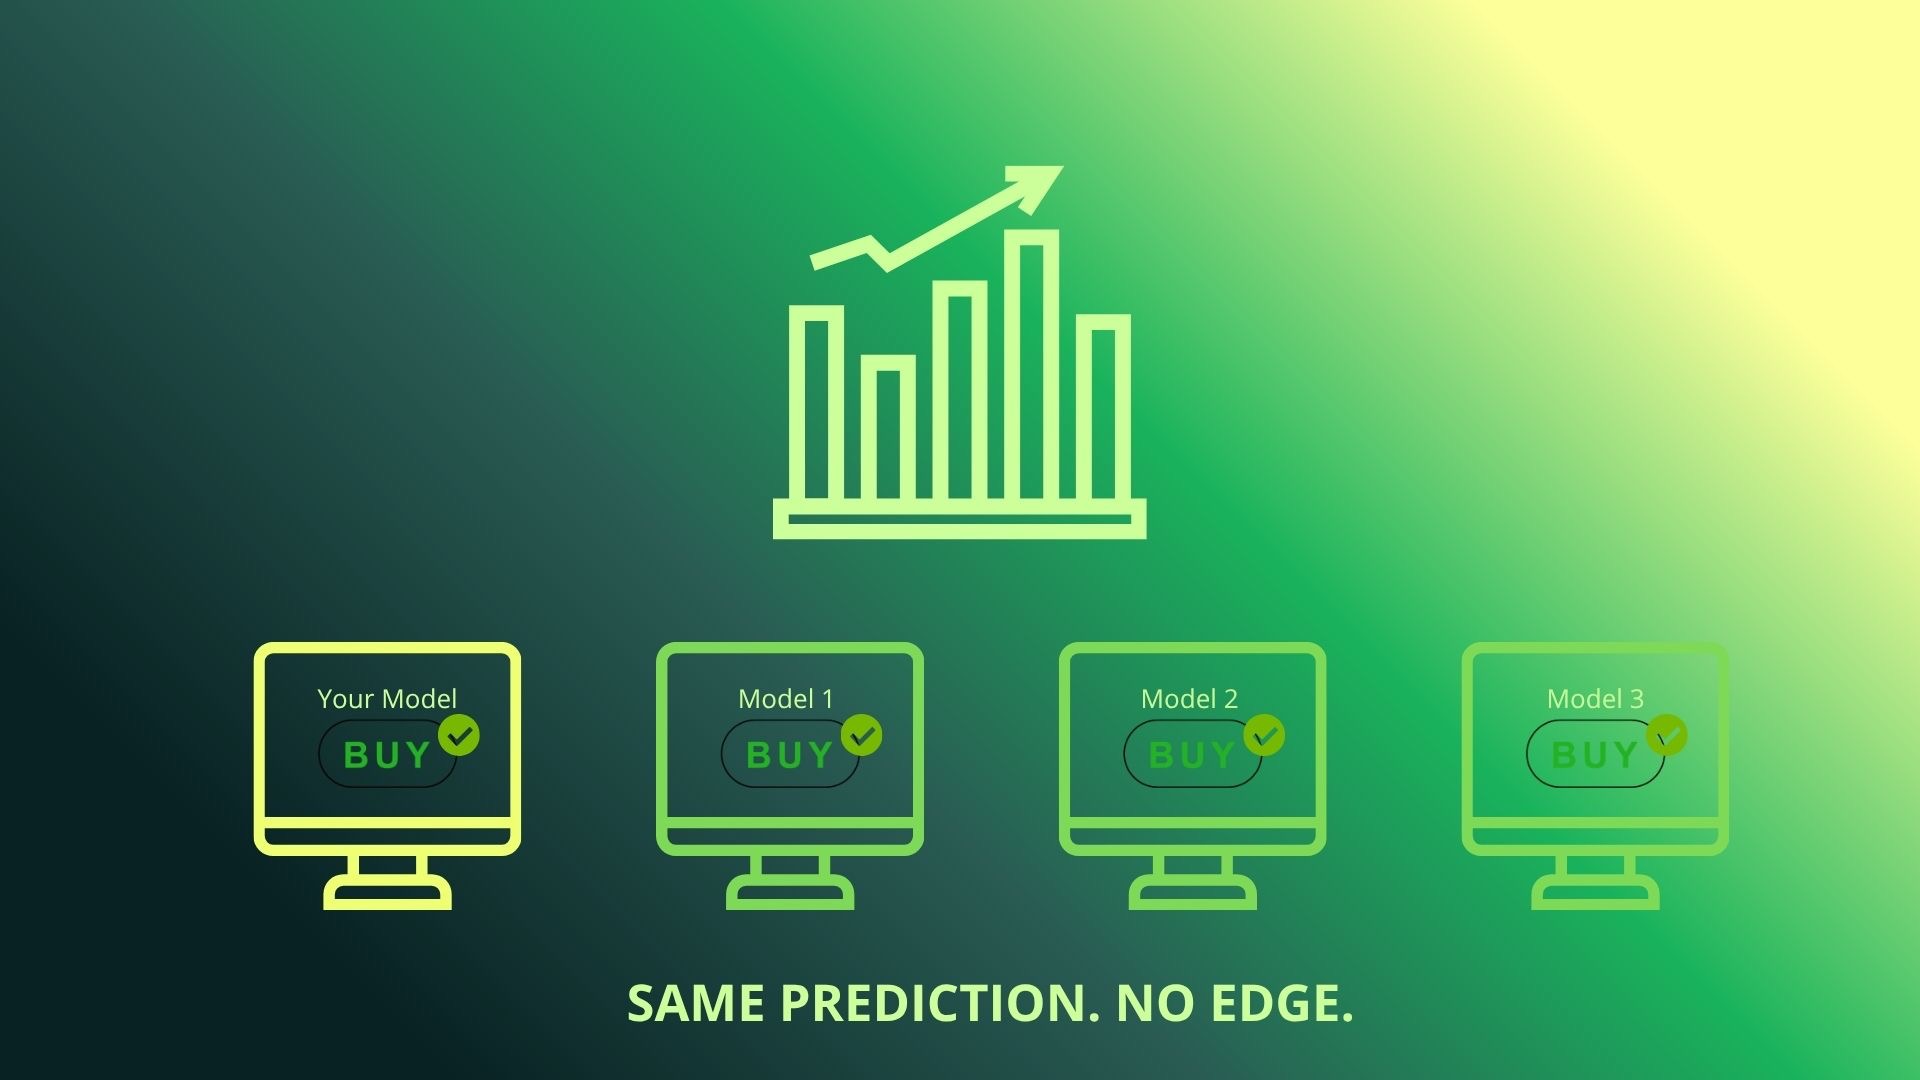
In the world of financial machine learning, a model's success is not solely determined by its accuracy in predicting market outcomes. The real value of such a model lies in the information it possesses, which other competing models have not yet priced into the market. This turns financial ML into a relative game, where the focus should be on what sets a model apart from its competitors.
Game theory offers a useful framework for understanding this dynamic. In a strategic environment, the payoff from a strategy depends on the actions of other participants. As more models discover the same signal, their collective actions alter the payoff itself, ultimately eroding its original edge.
The market does not reward purely accurate predictions; instead, it rewards models that uncover scarcity. A pattern may still be predictive even if it becomes widely known, but its economic value diminishes as more participants try to exploit it. Alpha, or the excess return generated by a model, is not just about useful information; it's about information that remains scarce.
A simple trading signal, such as a market event leading to a directional move, may initially be profitable. However, as more participants recognize the same signal, their reactions can transform the opportunity into a fleeting one, lasting only seconds or minutes. The problem is not with the model's decay but with the spread of knowledge about the pattern.
The presence of more competitors also affects liquidity and strategy capacity. With limited liquidity available, the first strategy to execute at a given price level gains the entire opportunity, while others may miss out entirely. Execution speed becomes crucial, as late entries can result in paying prices that no longer align with the initial prediction.
In extreme cases, the competition for alpha can lead to losses. If a signal predicts a 0.5% price move, but there is only $10,000 of available liquidity, an early entrant captures the full opportunity, leaving later entrants with minimal profits or losses. This highlights the importance of not only considering a model's predictive power but also its ability to execute efficiently.
Even with larger liquidity pools, the first model to react to a signal still enjoys an advantage in execution. The more models that respond simultaneously to the same information, the smaller the expected payoff becomes for each participant. At this point, competition for alpha becomes a race against time and execution speed.
Financial ML is not just about predicting market movements; it's about understanding the strategic game being played. A model must not only be correct in its predictions but also anticipate how other participants interpret and react to that prediction. The value lies in the difference between what is known and what is common knowledge.
Written by urgent.news from HackerNoon's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.