The math behind Databricks' $190B price doesn't add up—yet
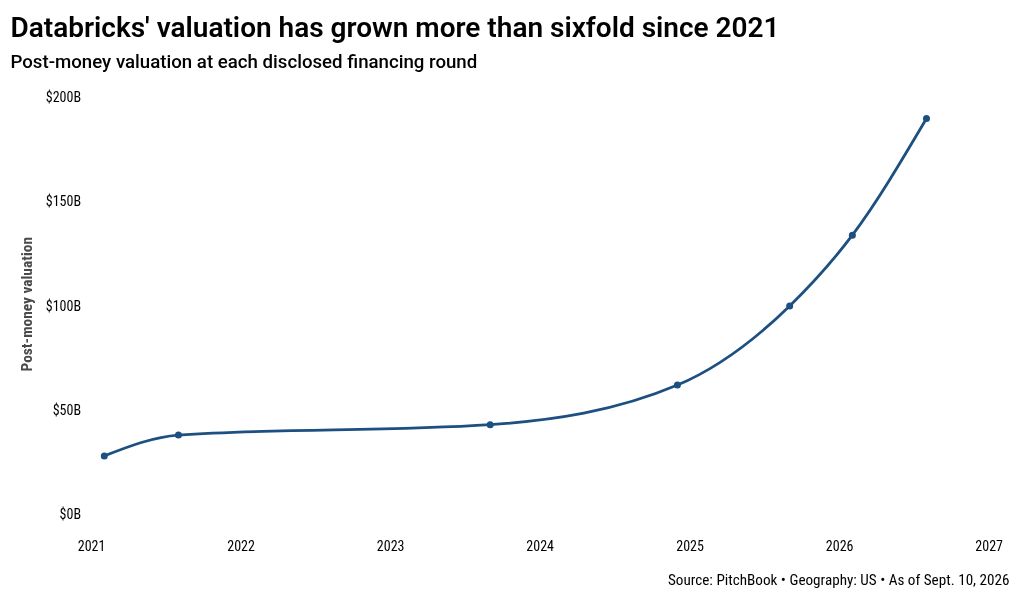
A new PitchBook report questions the justified nature of Databricks' $190 billion valuation. Databricks, a highly regarded private software company, raised $5 billion in August to reach a $190 billion valuation, a 41.8% increase from its previous $134 billion valuation in February. The company reported a 29.6% increase in its annualized run rate from $5.4 billion to $7 billion over the same period.
However, the report estimates the actual operating value of the business is closer to $68.7 billion, which is 64% lower than the $190 billion valuation. The gap stems from how the report projects Databricks' future profits. Analyst Harrison Rolfes forecasted Databricks' revenue and cash flow over the next decade, then discounted them to present day values to account for the changing value of money.
According to Rolfes' projections, Databricks could generate $9.3 billion in cash annually by 2035. While profitable, this figure is insufficient to validate the $190 billion valuation. As a point of comparison, Snowflake, Databricks' primary competitor, was valued at approximately $124 billion in early September, trading at around 20 times its expected annual revenue. Databricks' valuation is based on its $7 billion run rate, equivalent to a 27x valuation multiple.
Rolfes acknowledges that Databricks is a strong business, but argues that the price may not offer a satisfactory return for future investors. The key question now is whether the price leaves enough upside for the next investor.
Written by urgent.news from Yahoo Finance's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.