Personal loan for home renovation: Costs and benefits
Subtitle: A Personal Loan for Home Renovation can be used for painting, repair work, or home upgrades. The good news is there are tonnes of lenders willing to offer this loan. Here is all you need to know. Personal Loans are multi-faceted and can be utilised to pay for various kinds of expenses
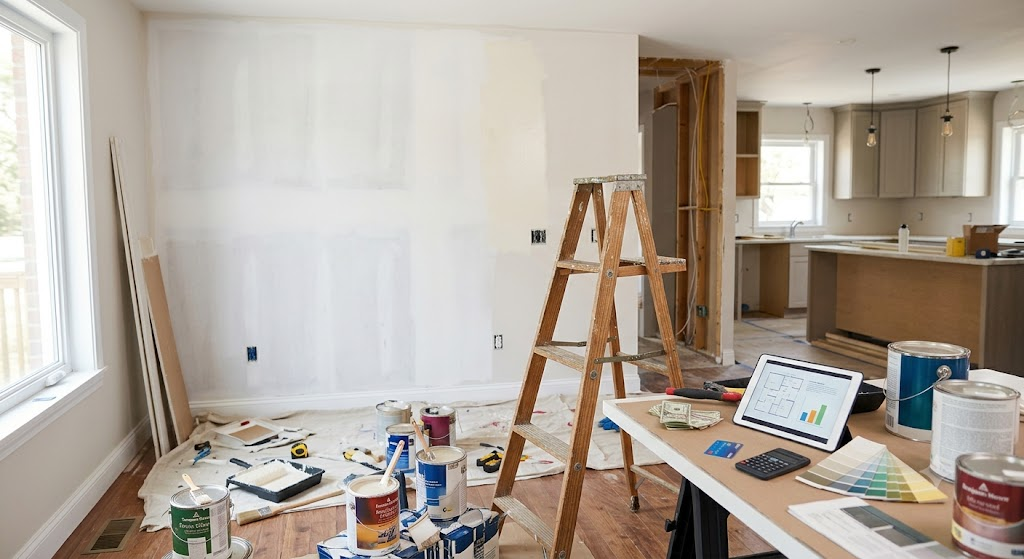
Personal loans offer a versatile way to finance home renovation expenses, with no end-use restrictions on the funds disbursed. Whether your property needs minor updates or significant upgrades, a personal loan can cover all aspects of the renovation process. In this article, we will examine the costs and benefits associated with using a personal loan for home renovation.
**Costs**
Lenders charge various fees and taxes on personal loans for home renovation. These costs may be incurred upfront or throughout the loan process. Some fees are mandatory, while others depend on the specific circumstances of the loan. Here's what to expect:
1. Processing Fees: Lenders charge an administrative fee to process your loan paperwork, typically ranging from 0.5-3% of the sanctioned loan amount. This fee is usually deducted from the loan amount disbursed, but you will still need to repay the full sanctioned loan amount.
2. Taxes and Statutory Charges: A 18% Goods and Services Tax (GST) is levied on the sanctioned amount, including processing charges, stamp duty, and loan registration fees. GST rates may vary by state in India.
3. Incidental and Third-Party Charges: Additional costs may include documentation, statement, and certificate fees, as well as mortgage guarantee charges. These fees are typically passed on to the borrower.
4. Interest: The most significant portion of the loan's cost is the interest payable, which is repaid through Equated Monthly Installments (EMIs). A lower interest rate results in higher EMIs but a shorter loan tenure, while a higher interest rate leads to lower EMIs over a longer loan period.
5. Prepayment and Foreclosure Charges: Some lenders charge a fee, ranging from 2-5%, if you choose to repay and close the loan before the end of its tenure. However, these fees are often waived for floating-rate loans.
6. Late Payment and EMI Bounce Charges: Borrowers who fail to make timely EMI payments may incur penal interest rates of up to 18% on overdue EMIs and additional bounce fees if the EMI cheque or auto-debit fails.
**Benefits**
Despite the associated costs, personal loans for home renovation offer several advantages:
1. Collateral-free: Personal loans are generally unsecured, meaning you do not need to pledge your property as collateral. This reduces the risk of losing your home if you face financial difficulties.
2. Quick disbursal: Most lenders disburse personal loans rapidly, often within 48 hours. This faster access to funds compared to other home improvement loans is beneficial when time is of the essence.
3. Flexible usage: With no restrictions on the loan amount, you can use the funds for a wide range of renovation expenses, including new furniture, appliances, interior decoration, wiring, and repairs.
4. Customizable tenure: Lenders allow you to choose your desired repayment period, typically ranging from 12 to 84 months. You can select a tenure that aligns with your repayment capacity and financial goals.
5. Fixed EMIs: Lenders provide an amortization schedule that outlines each EMI, making the loan and monthly cash outflow predictable and easier to budget.
6. Prepayment option: You can repay your personal loan early without incurring hefty penalties. If you have surplus funds, you can utilize this option to reduce the overall cost of the loan.
7. No project estimates required: Unlike specialized renovation loans, personal loans do not require detailed project estimates. You simply need to provide the loan amount you require.
In conclusion, personal loans can be an excellent option for financing home renovations, offering collateral-free financing, quick access to funds, and flexible usage. However, it is crucial to consider the associated costs, such as processing fees, taxes, interest, and potential prepayment charges. Adding a contingency of around 15% to contractor quotes can help account for unforeseen renovation expenses.
With numerous lenders available, including banks, NBFCs, and mobile loan apps, borrowers have a range of options to choose from when seeking a personal loan for home renovation.
Written by urgent.news from YourStory's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.