Howmet Aerospace (HWM) Faces New Competitive Pressure after GE’s $11.75 Billion CPP Deal
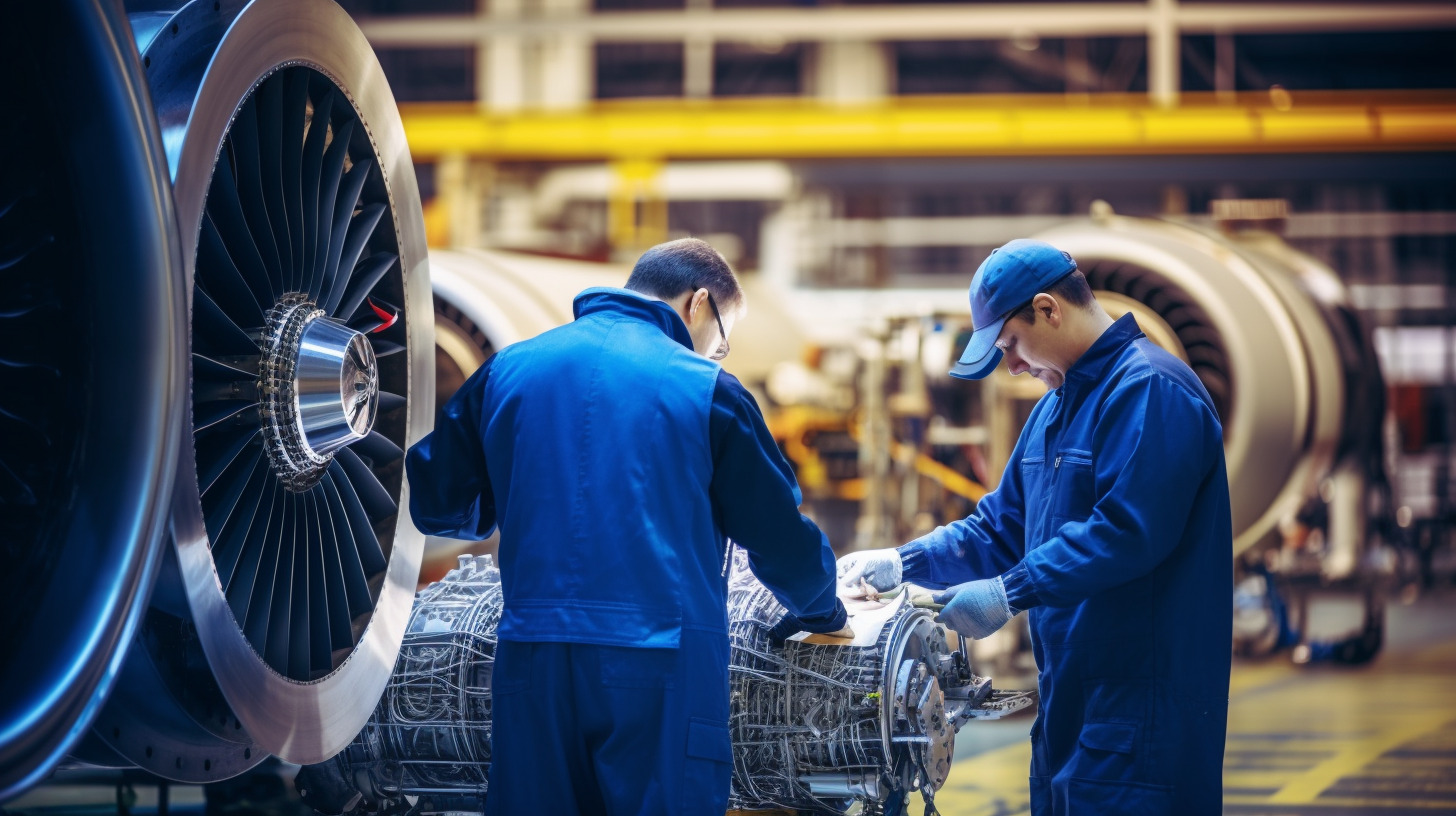
Howmet Aerospace Inc. (NYSE:HWM) is currently facing competitive pressure after GE Aerospace's acquisition of Consolidated Precision Products (CPP) for approximately $11.75 billion. The deal, aimed at securing more control over critical engine castings and expanding production capacity, initially caused a 10% decline in Howmet shares as investors worried that GE might rely less on external suppliers like Howmet.
However, Howmet's CEO, John Plant, remains confident in the company's growth potential. The primary issue for Howmet is its capacity to increase production to meet the growing demand, which includes commercial aircraft production, defense activity, and aftermarket demand. Additionally, Howmet benefits from the rising demand for turbine components used in data centers. Plant noted that the scale of capital expansion required is testing the company's limits.
The acquisition of CPP by GE is seen as validating the strategic importance of aerospace castings and engine components, as airfoil demand is expected to rise by more than 30% through 2030. GE anticipates that aircraft manufacturers and defense customers will continue to increase production. Consequently, Howmet's existing manufacturing footprint and expertise could provide it with significant pricing power and support further investment if demand outpaces available casting capacity.
However, there are concerns about GE's increasing vertical integration through the acquisition of CPP. By integrating a critical casting supplier, GE plans to increase CPP's output, potentially reducing Howmet's share of high-margin engine business with GE. If GE gradually shifts its requirements toward CPP, Howmet may lose market share and face increased pressure to invest heavily in its own factories to maintain its position.
This expansion would require significant capital, which could impact free cash flow and returns if demand does not develop as expected.
Customer concentration is another risk, as GE is a significant customer for Howmet. While existing contracts may protect some business in the short term, a gradual reduction in GE's dependence on external suppliers could become a more substantial headwind over the long term. The aerospace industry has previously experienced production disruptions due to supplier bottlenecks, emphasizing the operational risk involved in scaling highly specialized manufacturing rapidly.
Despite these risks, Howmet's long-term outlook remains positive, provided it can scale capacity quickly enough and retain key customers. While the article acknowledges that other AI stocks may offer greater upside potential and less downside risk, it suggests that Howmet could still be an extremely undervalued investment if it benefits significantly from the Trump-era tariffs and the onshoring trend.
Written by urgent.news from Yahoo Finance's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.