Eco-Shop's 16pct valuation premium justified but upside limited: Analyst
KUALA LUMPUR: Eco-Shop Marketing Bhd's 16 per cent valuation premium over Bursa Malaysia-listed discretionary consumer peers leaves limited room for further upside, CIMB Securities Sdn Bhd said.
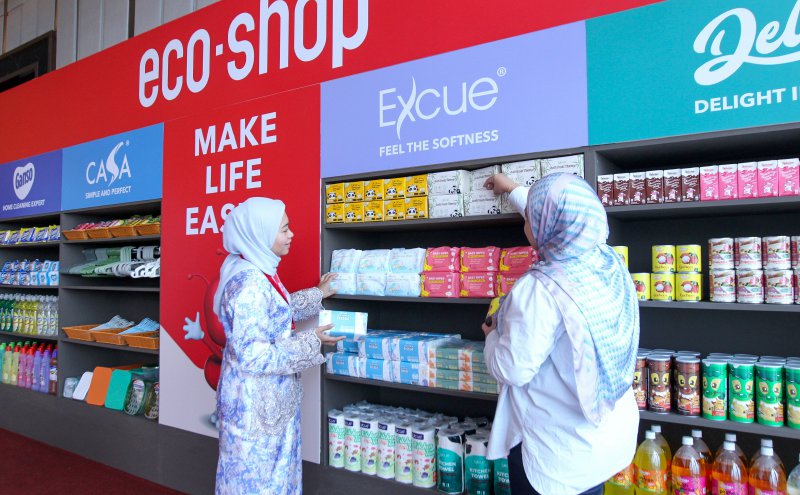
Eco-Shop Marketing Bhd's valuation premium of 16 percent over Malaysian-listed discretionary consumer peers may be justified, but further upside is limited, according to CIMB Securities Sdn Bhd. The brokerage firm initiated coverage on the fixed-price retailer with a "Hold" rating and an RM1.50 target price, stating that the stock is fairly priced as its growth prospects have largely been accounted for.
Eco-Shop, valued at RM8.35 billion, trades at a premium of 24.1 times its forecast earnings for 2027, significantly higher than peers in the discretionary sector. While Eco-Shop is expected to deliver stronger earnings growth than its peers, with a forecast of 22.2 percent growth in 2026 and 18.4 percent growth in 2027, near-term upside may be capped by execution risks in its expansion plans, potential slowdown in same-store sales growth, and margin pressure from rising sourcing requirements and operating expenses.
Written by urgent.news from New Straits Times's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.