Could L3Harris Technologies (LHX)’a Stability Outweigh Intuitive Machines. (LUNR)’s Explosive Growth?
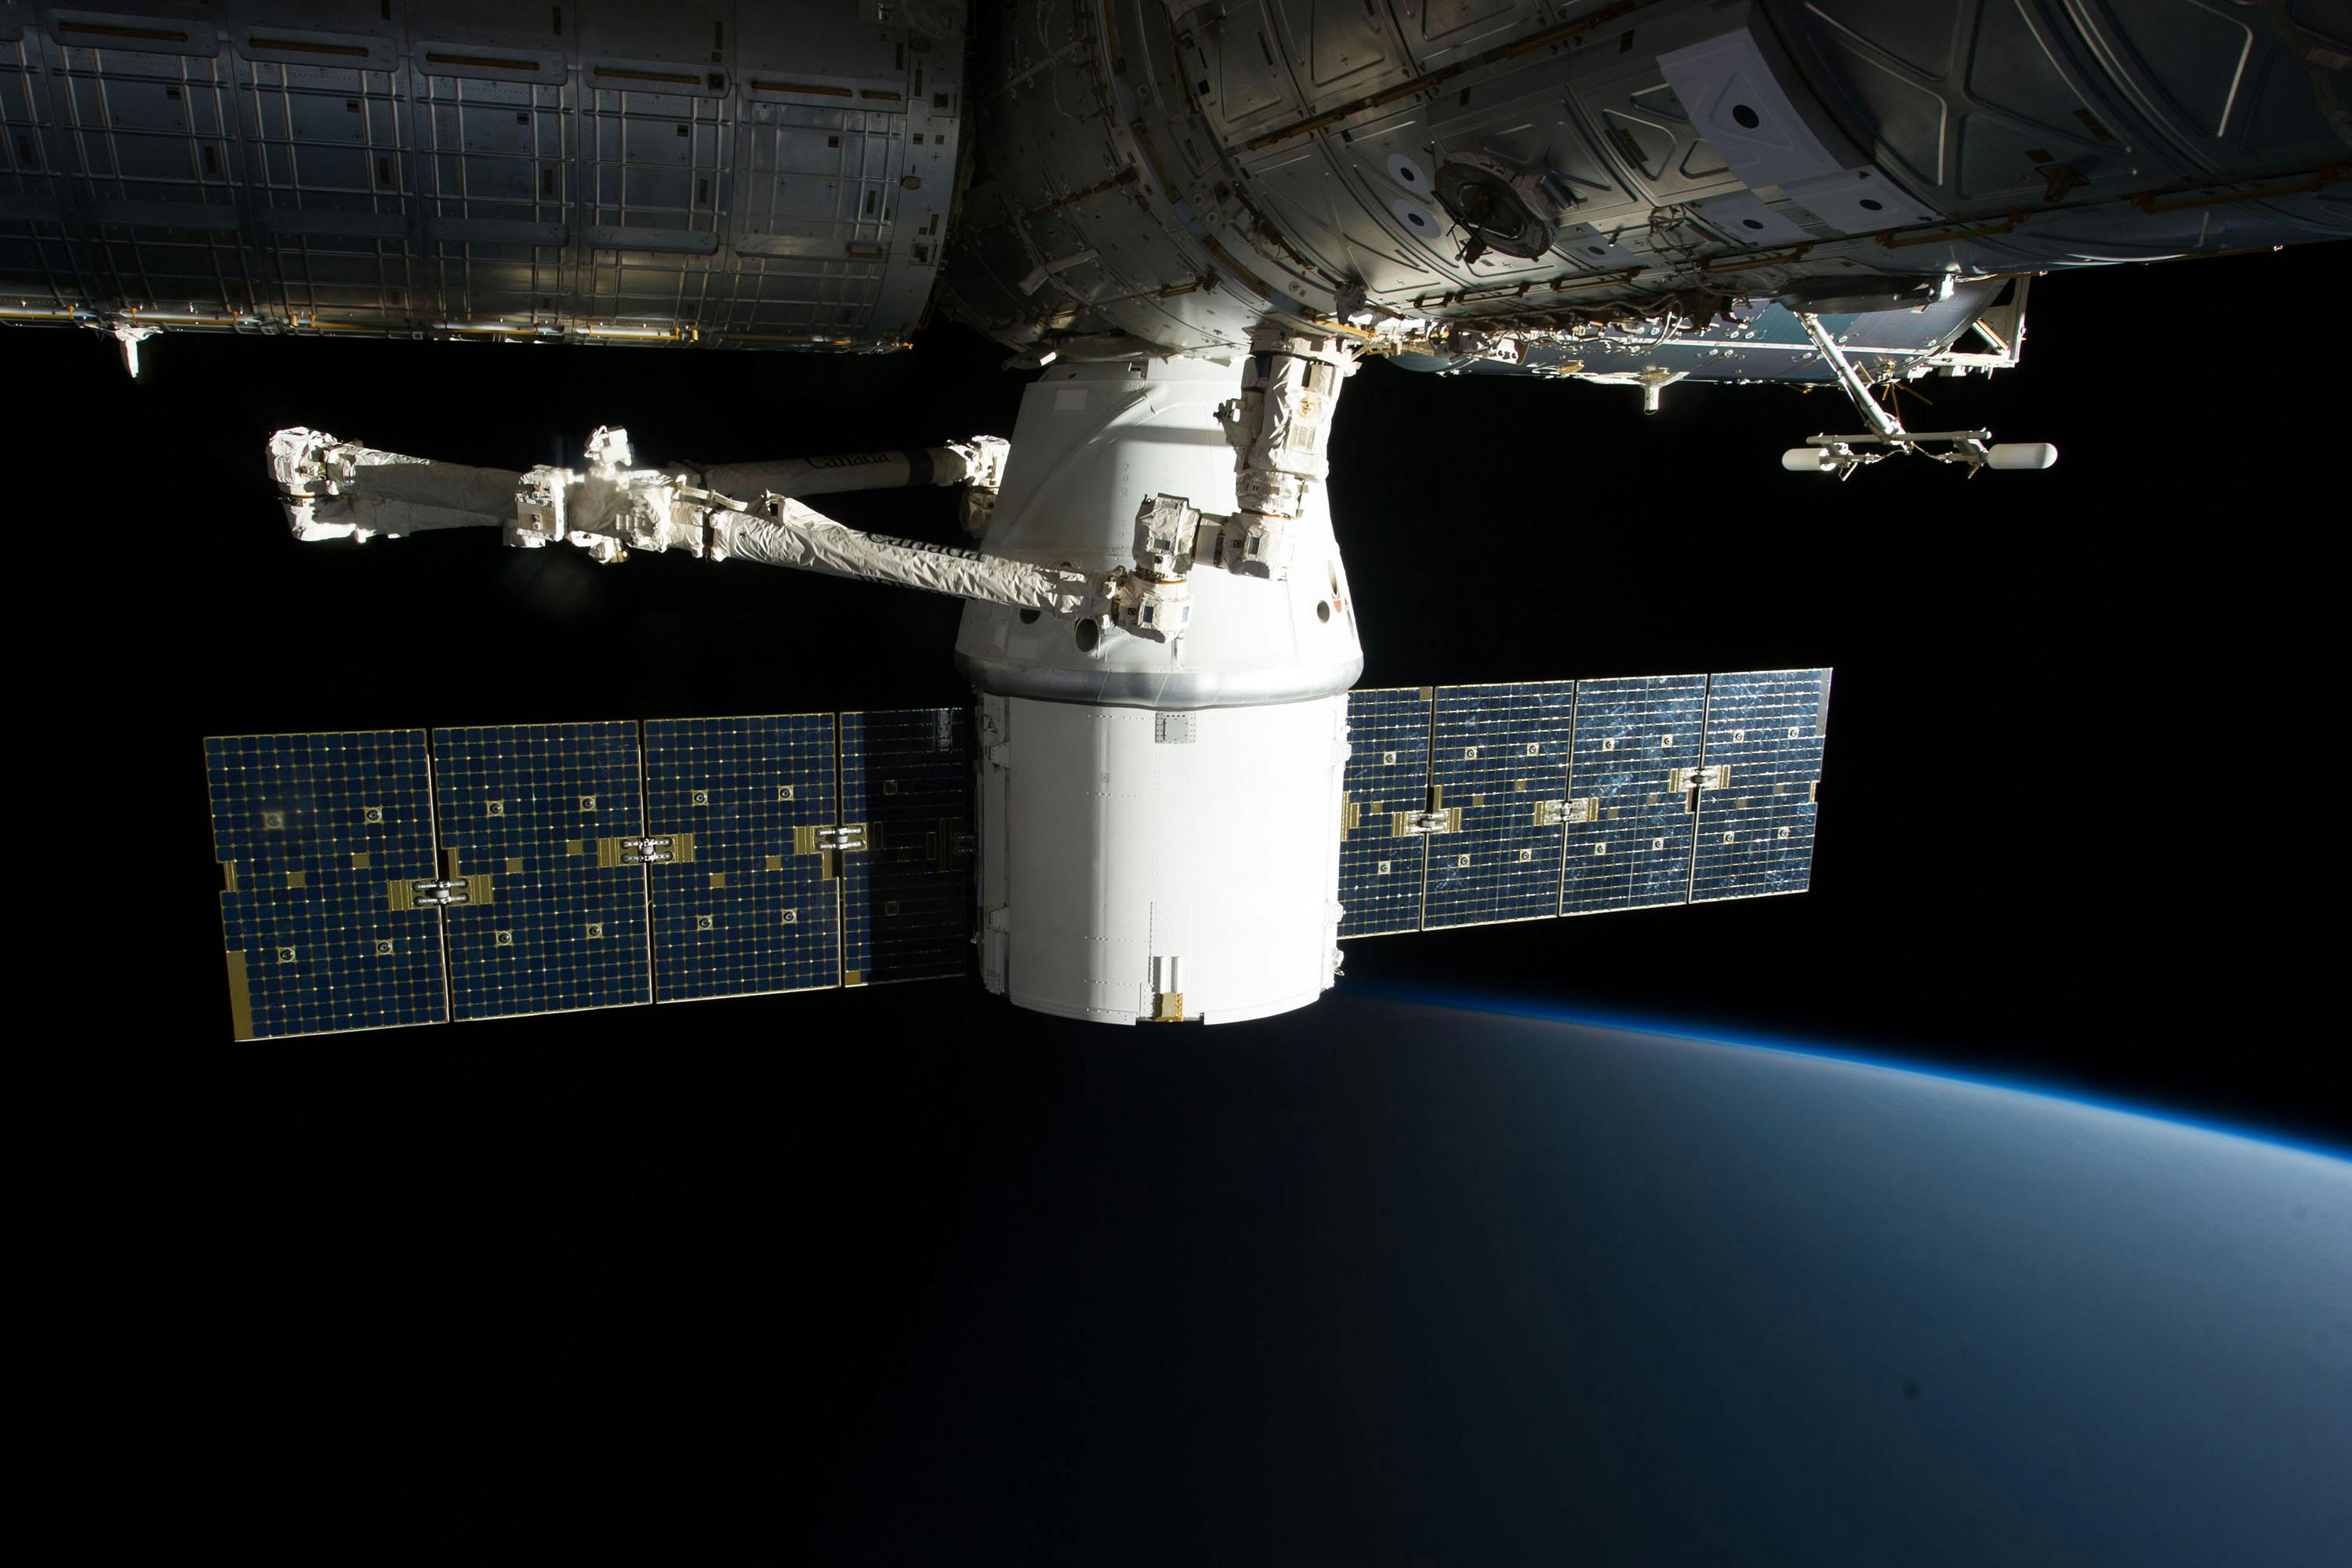
On August 4, L3Harris Technologies, Inc. (NYSE:LHX) selected Intuitive Machines, Inc. (NASDAQ:LUNR) to construct 18 advanced spacecraft platforms for the Space Development Agency's Accelerated Missile Defense Tranche 3 (AMDT3) mission. This partnership exemplifies a growing trend of large defense primes collaborating with agile commercial space firms to develop missile tracking infrastructure.
For Q2 2026, L3Harris reported revenue of $5.9 billion, a 8% year-over-year increase, and net income of $600 million, resulting in a diluted EPS of $3.13. They have a $42.0 billion backlog and generated strong free cash flow of $771 million. Management raised their full-year 2026 revenue guidance to $23.2 billion–$23.7 billion.
Conversely, Intuitive Machines experienced rapid growth, reporting $206 million in revenue in Q2 2026, more than quadruple its prior-year earnings. Although they had a gross profit of $36 million, the company posted an operating loss of $47 million and Adjusted EBITDA loss of $14 million. They burned $84 million in cash during the quarter, leaving $367 million in cash reserves, but their backlog expanded to a record $1.8 billion.
Management expects full-year 2026 revenue between $900 million and $1 billion and a positive Adjusted EBITDA.
LHX demonstrates stronger balance sheet stability, profit margins, and reliable cash generation. LUNR, however, is scaling rapidly with impressive revenue growth, yet remains unprofitable on a net income basis. Intuitive Machines' bullish case centers on massive commercial momentum and a potential multi-satellite communications infrastructure program valued at over $600 million.
Bearish factors for Intuitive Machines include capital intensity and profitability execution risks due to current operating losses and cash deployment. For L3Harris Technologies, the bullish scenario hinges on sustained defense spending, a $42 billion backlog, and increased full-year guidance. The bearish case may result from valuation re-ratings and leadership transitions.
Deutsche Bank analyst Scott Deuschle lowered LHX price target to $268 from $285 and assigned a Hold rating following the Q2 report and CEO change. Institutional sentiment revealed increased accumulation for both companies in Q1 2026, with LHX seeing 59 hedge funds holding the stock, up from 48 in Q4 2025, and D.E. Shaw holding 1.05 million shares, a 5,204% increase in activity. AQR Capital Management also increased its position by 248% to 849,424 shares.
Written by urgent.news from Yahoo Finance's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.