How India turned payments into participation
A vegetable seller in a small town in Rajasthan scans a QR code taped to her cart, and the money reaches her account before the customer has even walked away. Hours later, a few thousand kilometres west, an Indian tourist in a Dubai mall uses the same app to pay for a handbag, and the transaction clears just as quickly. Neither person thinks about what is happening underneath, and that is the…
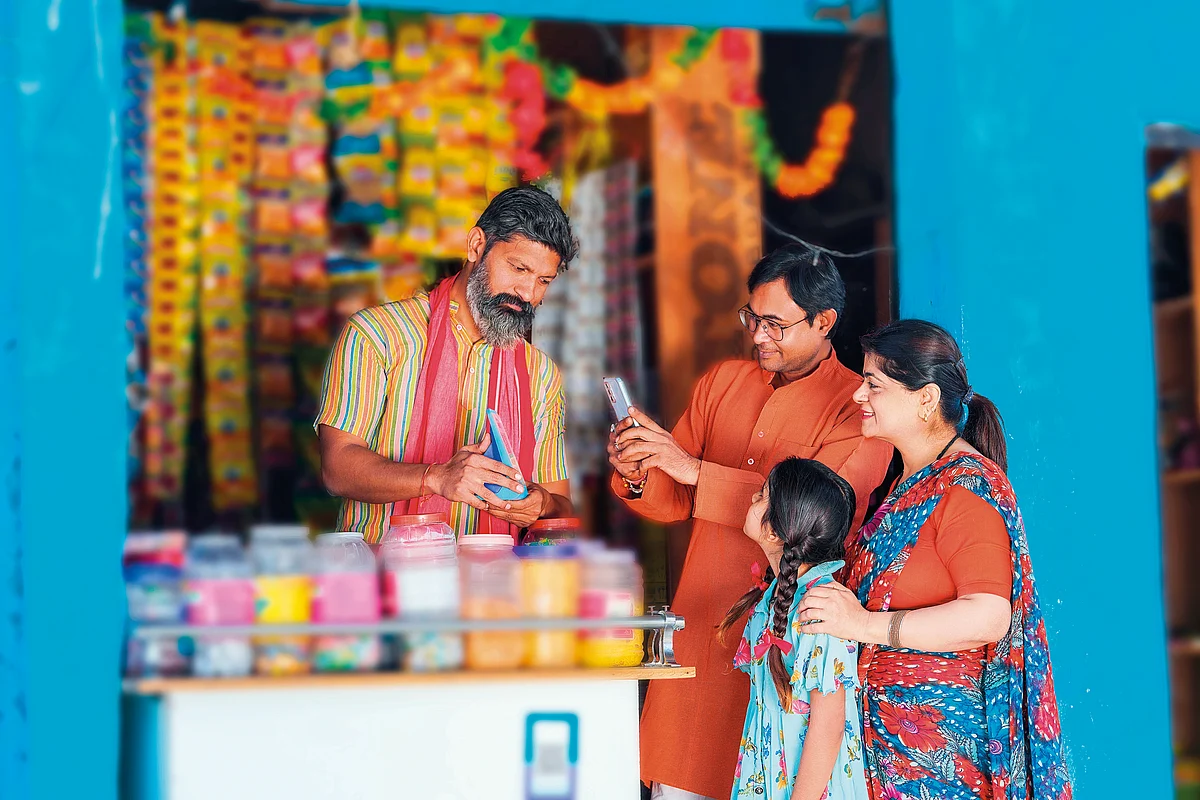
India's Unified Payments Interface (UPI) has revolutionized the way people make payments, turning a once cumbersome process into a seamless experience. Launched in 2016 by the National Payments Corporation of India (NPCI), UPI has become the world's busiest real-time payments network, with billions of transactions occurring each year.
What started as a simple way to transfer money between bank accounts has evolved into a critical component of India's digital economy, connecting consumers, merchants, banks, and fintech companies through a single, interoperable system.
The success of UPI can be attributed to its ease of use and interoperability across banks and payment apps. Users no longer need to remember complex bank account details; instead, they can send and receive money using a virtual payment address. This has significantly reduced the friction that had previously limited digital payments, making it accessible to millions of Indians who were previously unbanked or underbanked.
The UPI system was built on the foundations of the JAM Trinity – Jan Dhan bank accounts, Aadhaar, and mobile connectivity – as well as the broader India Stack, which includes digital identity, payments, consent-based data sharing, and other digital services. These initiatives created the necessary infrastructure for digital financial services to reach a larger population, enabling faster and more transparent access to public benefits for citizens and fostering innovation among banks, fintech companies, and merchants.
Today, UPI serves over 550 million users and 65 million merchants through more than 730 million interoperable QR codes. Its impressive growth, from 20 million transactions in 2017 to over 241.62 billion in 2026, demonstrates the transformative impact of open, trusted, and interoperable digital infrastructure. UPI now accounts for nearly half of the world's instant digital payments by volume, highlighting its significance in the global payments landscape.
The widespread adoption of UPI has not only made financial services more accessible but has also encouraged the formalization of economic activity. Street-food vendors, home-based entrepreneurs, and small shopkeepers can now accept payments digitally, creating a verifiable record of their economic transactions. This shift towards digital payments reduces dependence on cash, provides a transparent transaction history, and strengthens financial visibility, which can be crucial when individuals or businesses seek access to formal credit and other financial services.
Moreover, UPI has proven to be an inclusive platform, extending its benefits to users with feature phones, limited internet connectivity, and varying levels of digital literacy through innovations like UPI 123PAY and UPI Circle. By providing a low-cost way to accept payments without the need for traditional point-of-sale equipment, UPI has enabled the formalization of economic activity and strengthened financial transparency.
In conclusion, India's UPI has transformed payments into an engine of broader economic participation, demonstrating how trusted, interoperable public infrastructure can change the way an economy operates. As India marks its 80th year of independence and UPI celebrates its 10th anniversary, the platform's journey offers valuable lessons on the power of digital public infrastructure to expand access to financial services, foster private sector innovation, and reshape the landscape of modern commerce.
Written by urgent.news from Gulf News's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.