Broker’s call: Sansera Engg (Add)
Choice Broking
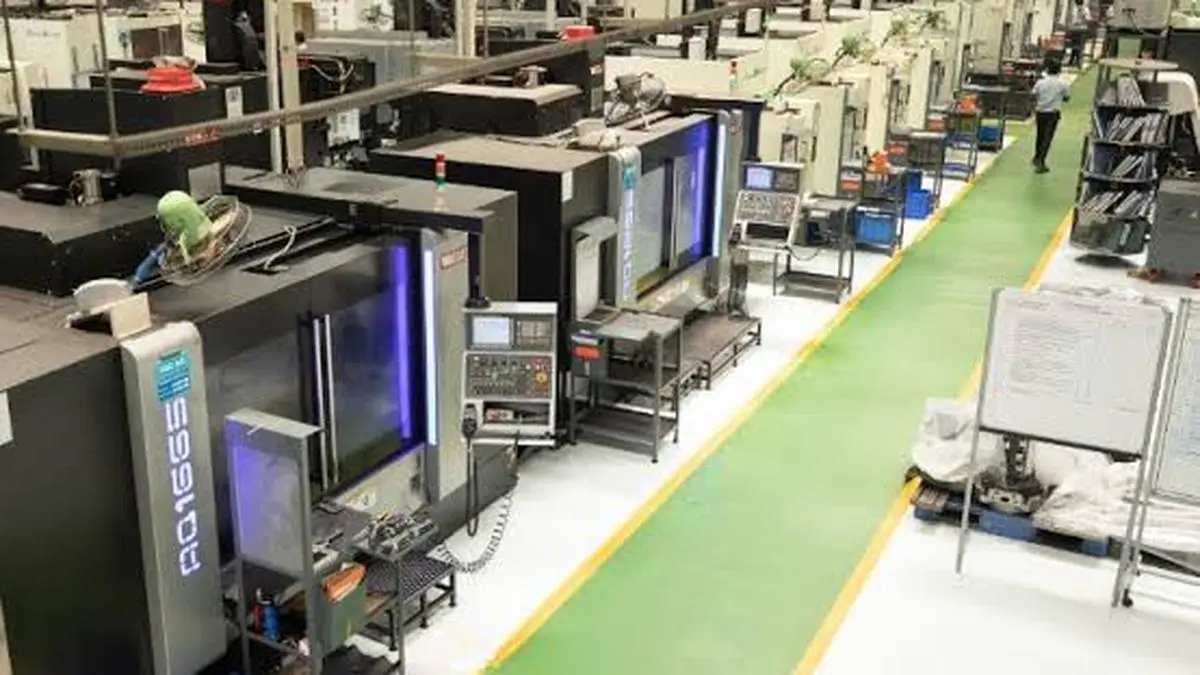
In Q1-FY27, Sansera Engineering achieved its highest quarterly performance ever, with revenue expanding 33% year-over-year and EBITDA/PAT rising 48% and 39% year-over-year. The growth was driven by robust performance in both automotive and non-automotive sectors. EBITDA margin expanded by 196 basis points year-over-year to reach 19.2%, bolstered by operating leverage, a favorable product mix, and higher contribution from ADS (Advanced Design Services).
Normalized PAT surged 59% year-over-year, underscoring solid earnings momentum. The significant milestone was the sharp scaling-up of ADS, with revenue tripling year-over-year to ₹145.40 crore, fueled by robust demand in aerospace and semiconductors. The analysts have revised their FY27E/FY28E EPS estimate upwards by 9.5% and 9.6%, respectively, considering strong order inflows and an optimistic growth outlook.
They have raised their PE multiple to 42x from 35x for FY28E EPS, reflecting the growing contributions from high-growth ADS and semiconductor businesses, heightened order visibility, and improving margins. Consequently, the target price is set at ₹3,880, and the stock is maintained with an 'Add' rating.
Written by urgent.news from Hindu BusinessLine's reporting — not their text. Machine-written — may contain errors; check the original before relying on it.